Can You Get a 10-Year Car Loan? Pros and Cons
Yes, a 10-year car loan is technically possible, but it is rare and usually limited to expensive vehicles, specialty lenders, or very specific financing structures. Used badly, it can leave you underwater for years and cost far more in interest than the car is worth. This guide explains when 10-year financing exists, why it usually fails the total-cost test, and the few cases where it may be the least risky option.
Where 10-year loans are more likely to appear
Yes, but only in narrow cases. A 10-year auto loan means 120 months, and that term is uncommon for standard passenger vehicles. Most lenders cap auto loans at 72 or 84 months, and some specialized lenders may offer 96-month terms under specific conditions.
What a 120-month loan usually looks like
For a normal sedan, SUV, or pickup, 120-month financing is hard to find because the vehicle loses value too fast for most lenders to stay comfortable. The longer the term, the more time there is for depreciation to outrun the loan balance. That weakens the collateral.
That is why 10-year financing shows up more often in specialty setups than in everyday car loans. It may be easier to find on vehicles with different underwriting rules, such as certain luxury or specialty purchases, but that does not make it common for ordinary used or new cars.
Why standard cars differ from specialty vehicles
Standard passenger vehicles are judged as depreciating collateral. Specialty financing can be structured around different risk assumptions, so terms can stretch farther. That does not mean a 120-month auto loan is standard; it means the lender is pricing a different kind of risk.
| Term | Monthly payment pressure | Total interest exposure | Negative-equity risk | Best fit borrower profile |
|---|---|---|---|---|
| 72 months | Moderate | Lower than longer terms | Lower, though still present early on | Buyer who can handle a midrange payment and wants less interest drag |
| 84 months | Lower than 72 months | Higher than 72 months | Higher, especially on fast-depreciating cars | Buyer who needs more room in monthly cash flow and can keep the car longer |
| 120 months | Lowest | Highest | Highest for most passenger cars | Buyer with a strong reason to keep payment pressure very low and a plan to hold the vehicle a long time |
Why lenders set term limits
Lenders cap term length because time changes the loan-to-value relationship. Cars lose value rapidly, so the collateral can weaken faster than the balance falls. Longer terms raise the chance of default over time, and they increase the odds that the loan stays above the vehicle’s value for much of its life.
Loan-to-value and collateral value
Loan-to-value matters because the car secures the loan. If the vehicle depreciates quickly, the lender has less cushion if the borrower stops paying. That is why 96-month financing is easier to find than 120-month financing: it still stretches the loan, but it leaves the lender with less exposure than a full 10-year term.
Used-car age limits matter
Used-car financing is more constrained than new-car financing. On an older vehicle, a 10-year term may be unrealistic because the car may age out before the loan does. A lender may reject the term outright, shorten the available payoff period, or ask for a larger down payment to offset the risk.
Suppose you are buying a five-year-old compact car with modest mileage. A 120-month term would mean the note could still be active when the car is very old, while the value keeps sliding each month. That is the sort of mismatch many lenders try to avoid.
Is a 10-year car loan a bad idea?
Often, yes for a standard car, but not always. The main problem is that a long term lowers the monthly payment while pushing more interest into the deal. If the vehicle depreciates faster than the balance falls, you can spend years upside down. Still, a longer term can be the least risky option if the alternative is missing payments.
The monthly payment trap
Longer repayment periods naturally create smaller monthly payments. That is the attraction. The trap is that the payment can make an expensive car seem affordable even when the total loan cost is much higher. A lower payment can hide a larger cost over the full loan.
Picture a shopper who is trying to keep the payment under a fixed budget cap. Stretching from 72 months to 120 months can make the same vehicle fit. The payment problem may go away, but the financing burden does not. It often just moves from the monthly bill to total interest and equity risk.
Total interest over the full term
One downside of 10-year financing is much higher total interest. Interest compounds over more months, so each extra year adds cost even when the payment feels easier. A longer term can mean more affordable monthly repayments, but more interest overall.
To compare offers, look at total loan cost, not only the monthly payment. If the longer term cuts the payment but adds years of interest, the loan may be less affordable in the broad sense, even if the monthly number looks better.
When a longer term can be the least risky choice
A longer term can be defensible when cash flow is tight and the borrower needs the payment to stay manageable to avoid delinquency. That is especially true if the alternative is taking on too much payment pressure and ending up in default. A longer term is not ideal, but it can be the safer path in a narrow set of cases.
- Compare 72-, 84-, and 120-month quotes for the same vehicle.
- Check the total interest paid, not only the monthly amount.
- Review how much equity remains after the first year and second year.
- Ask whether a larger down payment can shorten the term.
- Reject the 10-year option unless the payment relief solves a real budget problem.
What happens if you go upside down?
Negative equity means the loan balance exceeds the vehicle value. With a long term, that can happen early and last for a long stretch. If you trade in the car or it is totaled, the payoff can exceed the insurance or trade value, leaving you with a gap to cover.
How negative equity starts
Because cars lose value rapidly, the balance on a long loan can stay ahead of the car’s market value. That is especially common on rapidly depreciating cars. The problem is not only the first month; it is the slow pace of principal reduction compared with the faster pace of depreciation.
A common first-timer mistake is to assume equity starts building as soon as payments begin. On a long loan, that is often false. The early payments can go mostly to interest, while the car keeps dropping in value in the background.
What it means at trade-in or total loss
If you trade the car before the loan is far along, you may owe more than the dealer offers. If the car is totaled, insurance pays the actual value, not the loan balance. That is where a long term can become expensive in a way that is easy to miss when you only look at the payment.
Down payment and credit tradeoffs
A larger down payment lowers the amount you borrow and usually reduces monthly payment size. It can also help offset long-term risk by shrinking the balance before depreciation has time to do its work. Credit profile matters too: stronger credit generally makes longer terms more accessible, while weaker credit can require more cash up front.
How down payment changes the math
For new cars, a down payment above 20% is considered large. For used cars, a large down payment is often 10% to 15%. Subprime auto lenders typically require a $1,000 down payment or 10% of selling price. Those numbers matter because they reduce lender exposure and may make a shorter term more realistic.
If you can put more money down, you may not need a 120-month term at all. The smaller loan can fit a 72- or 84-month structure with less interest and less time spent underwater.
Why credit quality affects approval and rate
Creditworthiness affects approval odds and rates. A strong profile can improve access to longer terms and better pricing. A weaker profile can narrow options, raise the rate, and push the deal toward larger upfront cash or a shorter vehicle choice. Lender criteria vary, so one approval path does not guarantee another.
What are the alternatives to a 10-year car loan?
The best alternatives are usually simpler than stretching the loan to 120 months. Choose a less expensive vehicle, add more money down, or compare 72- and 84-month financing first. If the vehicle type truly calls for different financing, such as a specialty purchase, use the rules for that market instead of treating it like a standard auto loan.
Best alternatives in order
Start with the vehicle price. If the payment is too high, a cheaper car often solves the problem faster than a longer note. Next, increase the down payment if possible. Only after that should you stretch to 84 months. A 96-month or 120-month term should be the exception, not the starting point.
- Pick a lower-priced vehicle.
- Increase the down payment.
- Compare 72 months first.
- Compare 84 months if the shorter term is too tight.
- Consider 96 months only if a lender offers it and the car’s value profile supports it.
- Use 120 months only when the budget case is strong and the collateral risk is acceptable.
When a longer term is defensible
| Question | Yes or no |
|---|---|
| Do you need the lower payment to avoid missing payments? | Yes if the alternative is unaffordable |
| Does the vehicle’s value hold up well enough for the term? | Yes if depreciation is manageable |
| Can you make a meaningful down payment? | Yes if it shrinks the balance enough to matter |
| Is the car likely to be kept for the long haul? | Yes if you plan to hold it well past the early equity phase |
| Have you compared 72- and 84-month quotes first? | Yes before stretching to 120 months |
| Is this a standard passenger vehicle? | No if you are assuming specialty rules will apply |
Frequently asked questions
Are there 10 year car loans?
Yes, but they are rare for typical passenger vehicles. Most lenders cap auto loan terms at 72 or 84 months, and some specialized lenders may offer 96-month terms. A true 120-month loan usually appears only in narrow situations, not as a standard car-financing offer.
What lenders offer 10-year auto loans?
They are more likely to appear through specialized or niche lenders than through mainstream auto financing. The exact offer depends on the vehicle, the borrower’s credit profile, the down payment, and the lender’s risk rules. Criteria vary, so a long term from one lender does not mean another will approve it.
How much more interest do you pay on a 10-year car loan?
Usually a lot more, because interest is charged over more months. The exact difference depends on the rate, loan amount, and down payment, but the direction is clear: a 120-month loan almost always costs more in total interest than a 72- or 84-month loan on the same vehicle.
Can you finance a used car for 10 years?
Sometimes, but it is less realistic than on a newer vehicle. Older cars may run into lender age limits before the term is approved, and depreciation can make the collateral too weak for comfort. Used-car financing usually works better with shorter terms and a stronger down payment.
What happens if I go upside down on a car loan?
Your loan balance is higher than the vehicle’s value. That matters if you sell, trade, or total the car, because the payoff can exceed the car’s worth. With a long term, this risk is higher and can last for much of the loan.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
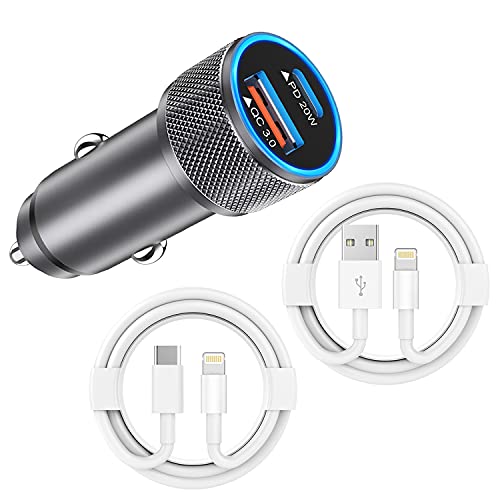 iPhone Car Charger,USB C Fast Car Charger[Apple MFi Certified] Apple Car Charging 38W Dual Port CarCharger Cigarette Lighter Adapter 2x3ft PD&QC 3.0 Lightning Cable for iPhone 14/13/12 Pro/11/Airpods
 Hail Protector Car Cover for Sedan(Length:Length:186"-203") + Gift Windshield Sunshade, Multi-Layered EVA Hail Proof Car Cover, Padded Car Hail Protector Blanket for Camry, Model 3, Accord, K5 etc.