Does A Bent Frame Total A Car? What Insurers Really Say
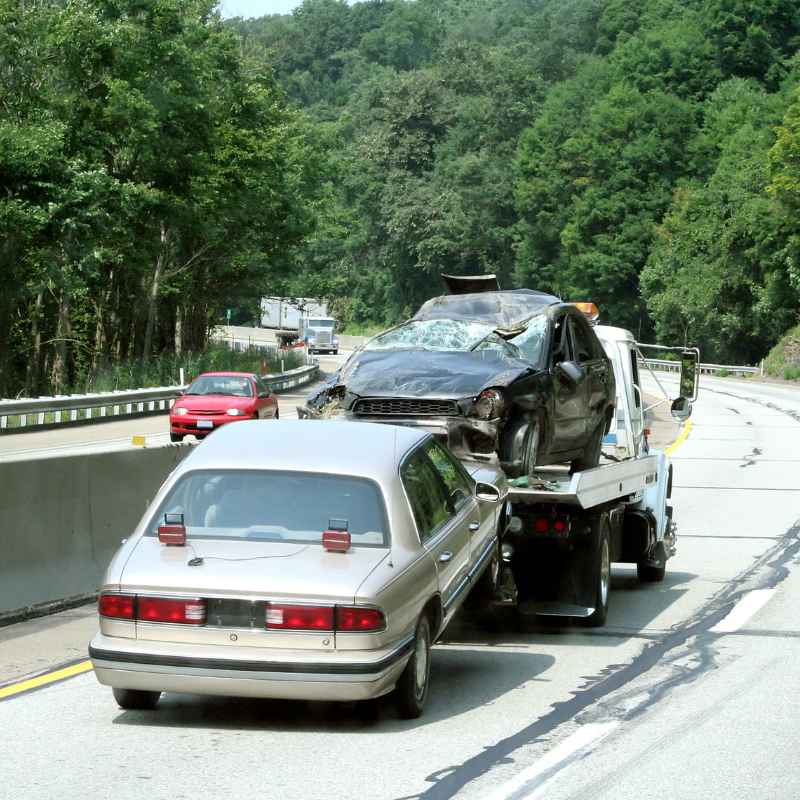
A bent frame can total a car when repair cost, salvage value, and state total-loss rules push the claim past an insurer’s threshold, which is often reported as being around 70% to 80% of actual cash value. Miss that cutoff and you can end up with an underpaid repair or spend time contesting a total-loss decision. This guide breaks down insurer math step by step and shows which structural damage and line items usually push a bent frame from repairable to totaled.
Bent frame and total loss
A bent frame does not automatically total a car. Insurers compare the repair estimate, the vehicle’s actual cash value, and the rules in the state where the claim is handled. On one car, a straightening job plus parts may stay under the limit. On another, the same damage can cross it quickly.
Why the same damage can produce different outcomes
Actual cash value is the pre-accident market value basis adjusters use, and it reflects age, mileage, condition, and local demand. That means a newer SUV with expensive safety gear can have a high repair estimate and still be repairable, while an older sedan with a low ACV can total with less visible damage.
Frame damage can involve rails, unibody sections, subframes, or floor pan areas. Those parts do not all carry the same repair risk. A straight rail pull on a body-on-frame truck is not the same claim as a crushed unibody rail on a late-model crossover with driver-assist sensors.
How insurers decide total loss
Insurers decide total loss by comparing the claim math against the car’s value, not the original sticker price. They start with ACV, then add the projected repair cost. If the number crosses the state threshold or the formula result, the carrier can declare a total loss.
Actual cash value and repair estimate
ACV is the baseline. Repair cost is the other side of the equation. The estimate may include structural labor, parts, paint, alignment, suspension work, scans, and calibration. When hidden damage appears during teardown, the number can rise fast.
Threshold rules versus total loss formula
State total-loss percentages can range from 60% to 100%. The most common fixed threshold mentioned is 75%. About half of U.S. States use a formula instead of a fixed percentage. California can total a car using repair-cost-versus-value math rather than a fixed rule.
The total loss formula compares repair costs plus salvage value against the car’s worth. That matters because a vehicle can total at a lower repair estimate if salvage value is high enough or if the state uses formula math instead of a simple percentage cap.
Where salvage value fits
Salvage value is the amount the insurer expects to recover by selling the damaged vehicle after the claim. In formula states, that value is part of the calculation. A higher salvage value can move a borderline repair into total-loss territory even when the body damage seems manageable.
Can a bent frame still be repaired?
Yes, a slightly bent frame can still be repaired if the structure can be measured, pulled, and verified within specification. The key question is not whether the metal moved. It is whether the damage can be returned to factory limits without compromising crash protection, alignment, or sensor function.
When straightening is possible
Frame straightening Uses hydraulic frame racks and laser measuring systems that are commonly described as highly precise. If the damage is mild and the structure remains within the repair window, a shop may be able to pull it back and confirm the dimensions.
When replacement is the safer call
High-strength steel changes the decision. The shop page cited in the proof set says it refuses to pull torn or kinked high-strength steel and treats replacement as the correct choice in those cases. That is common with modern structural zones where heat can alter material properties.
Crumple zones matter here. They are designed to absorb crash energy by collapsing, so they cannot simply be hammered back safely. If a damaged section was built to deform in a crash, the repair plan may shift from straightening to replacement.
How modern safety design changes the answer
Newer cars can carry radar, camera, and airbag-related parts close to the damaged structure. Suppose a compact crossover gets a front-right hit that bends the rail and throws off the bumper beam mount. The metal may be repairable, but the scan and calibration work can add enough cost to push the claim over the insurer’s line.
Which damage types drive total-loss risk?
Some damage locations are more likely to create a total loss because they trigger structural labor, suspension work, and electronic checks all at once. Rail damage is often the most expensive. Unibody and floor pan damage can be worse than they look. Subframe damage can also add hidden cost fast.
Rails and unibody damage
Rails are part of the car’s core structure. If a rail is buckled, torn, or displaced, the estimate can include structural pulls, replacement sections, measuring time, and related parts. On a unibody car, rail damage can ripple into door gaps, suspension pickup points, and body alignment.
Subframe and floor pan damage
Subframe damage can affect engine mounts, steering geometry, and suspension alignment. Floor pan damage may involve seat mounts, exhaust routing, and underbody reinforcement. These repairs often need more labor than a quick look suggests, especially if the impact reached several layers of the structure.
Suspension, airbag, scan, and calibration add-ons
Even if the frame pull itself looks moderate, the claim may grow because of suspension replacement, airbag parts, post-repair scans, and calibration. Those line items are common on vehicles with modern driver-assist systems. A front-end hit can turn into a structural and electronics repair at the same time.
Picture a midsize sedan with a bent front rail after a low-speed collision. If the front wheel is pushed back, the estimate may need control arms, a wheel alignment, a scan, and a camera calibration in addition to the rack time. The frame issue is only one part of the bill.
Bent frame decision matrix
This table shows how damage location, hidden-cost add-ons, and vehicle value band usually affect claim risk. It is not a promise. It is a practical way to see why one bent frame becomes a repair and another becomes a total loss.
| Damage location | Likely extra repairs | Claim risk | Documents to request from the adjuster |
|---|---|---|---|
| Rail | Suspension, alignment, scans, calibration, possible rail section replacement | High on low-value cars; medium on higher-value cars | Valuation report, repair estimate, measurement sheet, photos, supplement rules |
| Unibody | Door fit checks, suspension, scans, calibration, body labor, possible section replacement | High across most age bands | Valuation report, structural measurement records, teardown photos, OEM repair steps |
| Subframe | Alignment, suspension parts, steering components, scans, calibration | Medium on newer cars; high on older low-ACV cars | Estimate line-item breakdown, subframe inspection notes, supplement process, scan report |
| Floor pan | Seat mounts, exhaust, underbody braces, alignment, possible airbag-related checks | Medium to high depending on depth of intrusion | Photos of intrusion points, measuring data, repair-versus-replace notes, salvage-value basis |
For a car in the lower ACV band, any structural hit can become a total loss faster because the repair estimate only has to reach a smaller number. For a newer vehicle, the risk often comes from the add-ons: electronics, diagnostics, and OEM structural steps that cannot be skipped.
Can insurance total a car later?
Yes. A claim can move from repair approval to total loss after teardown if supplements push the final number above the insurer’s limit. The first estimate is often incomplete because hidden damage stays out of view until panels come off and the shop measures the structure closely.
Supplements after teardown
Supplements are added when the shop finds damage beyond the first estimate. That may include bent brackets, damaged mounts, extra labor, or parts that only show their failure after disassembly. Hidden damage can also mean extra scans, alignment time, or calibration work that was not obvious at intake.
What to watch for in a revised claim
Ask whether the insurer is using a fixed threshold or formula math, and ask how supplements are counted. If the revised estimate crosses the carrier’s line, the claim can flip to total loss even after initial repair approval. That is common when teardown exposes frame or rail damage that looked minor from the outside.
Title branding after total loss
Once a vehicle crosses the threshold, the title gets branded as salvage. That brand stays with the vehicle through later sale and tells future buyers that the car suffered serious prior damage. It affects resale, financing, and insurance options.
Salvage title basics
A salvage title does not always mean the car is unusable. It means the insurer declared it a total loss under the applicable rules. The vehicle may later be repaired and sold, but the brand remains on the title record.
How a nonrepairable brand differs
A nonrepairable brand is separate from salvage branding and is state-specific. It is used for vehicles damaged beyond reasonable restoration. In plain terms, salvage usually means a vehicle can be rebuilt under state rules, while nonrepairable means the state treats it as beyond normal road return.
Why title branding matters for resale
Buyers will see the brand later, and many lenders and insurers treat branded titles more cautiously. That does not just affect sale price. It can also affect whether the next owner can insure the car on the same terms as an unbranded one.
Should you push back on the valuation?
If the ACV looks low, push back. An understated valuation can turn a repairable car into a total loss on paper, especially when the estimate is near the threshold. An independent appraisal can help when the insurer’s number misses the local market or ignores options and condition.
When the ACV looks low
Look for errors in mileage, trim level, equipment, prior condition, and comparable vehicles. Because adjusters use ACV as the market-value basis, a small valuation miss can change the claim result. That matters most when repair cost is already close to the insurer’s cutoff.
What an independent appraisal can do
An independent appraisal can challenge an undervalued settlement and support a borderline total-loss dispute. It is most useful when the repair-versus-total-loss call depends on a small gap between the insurer’s value and the estimate. A different market analysis can change the outcome.
What to dispute first
Start with the valuation report, the full repair estimate, and the supplement process. Request photos and measurement records from the adjuster. If the carrier skipped a calibration, omitted a structural operation, or used weak comparable sales, that is where the dispute should begin.
- Ask for the ACV report and every comparable vehicle used.
- Request the full repair estimate with each line item visible.
- Get the teardown, measurement, and scan records in writing.
- Check whether the claim uses a threshold or a total loss formula.
- Compare the carrier’s numbers with an independent appraisal if the gap is small.
Frequently asked questions
Does a bent frame automatically total a car?
No. A bent frame can be repairable if the structure can be measured and returned to spec, and if the repair cost stays below the insurer’s limit. The car totals when the numbers cross the applicable threshold or formula result, not just because the metal bent.
How do insurers decide if a car is totaled after frame damage?
They compare the repair estimate, salvage value, and the car’s actual cash value under the state rule in play. If the final number crosses the threshold or the formula says the vehicle is worth less than the claim cost, the insurer can total it.
Can a slightly bent frame still be repaired?
Yes, if the damage is minor enough to measure, pull, and verify within spec. The decision depends on whether the shop can restore the structure safely and whether the materials can be repaired under OEM guidance. High-strength steel or torn structure can change that answer quickly.
What percentage of a car’s value totals it?
State total-loss percentages can range from 60% to 100%, and the most common fixed threshold mentioned is 75%. Some states use a total loss formula instead of a fixed percentage, so the answer depends on location and on how the insurer calculates the claim.
Can insurance total my car after initially approving repairs?
Yes. Supplements from teardown can raise the estimate after hidden damage appears, and the claim can cross the insurer’s limit later. That often happens when structural damage, extra suspension work, or calibration needs show up only after the car is partially disassembled.
What is actual cash value in a total loss claim?
Actual cash value is the pre-accident market value basis the adjuster uses. It reflects age, mileage, condition, and local demand. The insurer compares that number to the repair estimate and, in some states, to salvage value as well.
Does frame damage mean salvage title?
Not by itself. Salvage branding usually follows when the vehicle crosses the applicable total-loss threshold or formula result. If the car can be repaired without crossing that line, the title may stay clean. If it is declared a total loss, the brand is triggered.
Should I get an independent appraisal for frame damage?
If the valuation looks low or the claim is close to the total-loss line, yes. An independent appraisal can support a challenge to the ACV, compare local market evidence, and show whether the insurer left out repair items that matter to the math.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 VEYFIY High-Strength Steel Car Flip Key Pin Removal Clamp Tool for Folding Key Blade Repair Disassembly Fits Most Models 1mm or 1.5mm(1.25mm Pin)
 Kalttoy Car Dent Repair Body Damage Fix Tool Pulling Bridge Puller Dent Removal Glues Tabs Hand Repair Tools Car Puller Auto Body Kit Glues Sticks Suction Cup Metalhammers T-bar