Does a Car Payment Affect Food Stamps? SNAP Vehicle Rules Explained
No — a car payment itself is not counted as income or an allowable expense when SNAP (food stamps) calculates your benefit. What can matter is your vehicle’s value, and only in the minority of states that still apply an asset test.
This trips up a lot of applicants because the rules sound like they should be connected. You’re paying several hundred dollars a month for a car, so it seems obvious that should lower your countable income the way rent does. It doesn’t. SNAP’s deduction list is fixed by federal rule, and a personal auto loan payment isn’t on it. What actually decides whether your car matters is a separate test: whether your state still counts vehicle value as a resource at all, and if it does, whether your car is worth more than the federal exclusion amount of $4,650.
Below is exactly how SNAP treats a car payment versus a car’s value, which states still run an asset test in 2026, the real list of expenses that do lower your countable income, and what to bring when you apply.
The Direct Answer: How SNAP Actually Treats a Car Payment
SNAP net income is calculated using a specific, closed list of deductions set by federal regulation. A car loan payment is not one of them. It doesn’t matter whether the payment is $150 a month or $700 a month — caseworkers don’t subtract it from your income the way they subtract rent, utilities, or child care.
The deductions SNAP is actually allowed to apply are:
- A standard deduction (a flat amount based on household size)
- A 20% deduction off earned income (wages, self-employment)
- A dependent care deduction for child care or adult care that lets you work or look for work
- A medical expense deduction, but only for household members who are 60+ or disabled, for costs above $35/month
- An excess shelter deduction for rent/mortgage and utilities above half your income after other deductions, capped at $744/month for federal fiscal year 2026 in most states (no cap if the household has an elderly or disabled member)
- In some states, legally owed child support you pay
Notice what’s missing: car payments, credit card minimums, and most other consumer debt. This is also why the article you might see elsewhere claiming “higher car payments lower your food stamps, lower payments raise them” is inaccurate — that logic simply isn’t part of the SNAP formula. The payment amount doesn’t move your benefit up or down at all.
Keep Your SNAP Paperwork Together
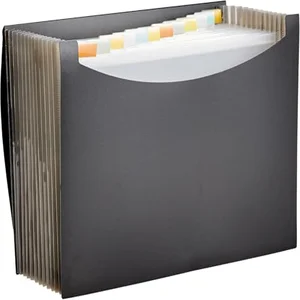 |
Amazon Basics Expanding Accordion File Organizer – $6.81 SNAP applications require proof of income, residency, and household expenses all at once — this keeps pay stubs, your car loan statement, and utility bills sorted by category instead of loose in a folder.
|
When Your Vehicle’s Value Can Affect SNAP Eligibility
While the payment doesn’t matter, the car itself can — but only through the SNAP resource test (also called the asset test), and only in states that still use one. Where it applies, the federal resource limit is $3,000 for most households, or $4,500 if at least one household member is age 60 or older or has a disability. Resources include things like cash, money in checking or savings accounts, and, in some states, vehicle value.
Under federal vehicle rules, one vehicle per adult household member is automatically excluded from resources no matter what it’s worth — the same rule applies to SSI, see our guide on can you own a car on SSI for the full resource-limit breakdown. If a household owns an additional vehicle beyond that, only the portion of its fair market value above $4,650 counts toward the resource limit. A car that’s fully paid off and worth $9,000, for example, would add $4,350 in countable resources in a state that still tests for it. A vehicle that’s financed and only worth $3,000 in equity typically wouldn’t push a household over the limit at all.
A vehicle is also excluded from the resource count regardless of value if it’s used to produce income (a rideshare or delivery vehicle, for example), needed for long-distance travel to a job, used to transport a household member with a disability, or used to haul the household’s primary source of fuel or water.
Which States Still Apply a Vehicle Asset Test
Most of the country has stopped testing vehicle value entirely. 39 states plus Washington, D.C. use a federal option called Broad-Based Categorical Eligibility (BBCE), which waives the standard SNAP resource test altogether — in those states, your car’s value (and your car payment) simply doesn’t enter the eligibility math at all.
| State Group | Vehicle/Asset Test Status |
|---|---|
| 39 states + D.C. (most of the country) | No asset test at all (BBCE) — vehicle value and car payments don’t affect eligibility |
| Kansas | Applies the federal vehicle/resource test |
| Mississippi | Applies the federal vehicle/resource test |
| Missouri | Applies the federal vehicle/resource test |
| South Dakota | Applies the federal vehicle/resource test |
| Tennessee | Applies the federal vehicle/resource test |
| Utah | Applies the federal vehicle/resource test |
| Wyoming | Applies the federal vehicle/resource test |
A few states in this second group set their own, higher vehicle exclusion amount instead of the $4,650 federal figure — Texas, for instance, excludes a higher value per vehicle under its own state rule. State SNAP policy also changes from year to year, so if you live in one of the seven states above, call your local SNAP office or check your state’s Department of Human/Social Services website before assuming a vehicle will count against you.
What Actually Lowers Your Countable Income for SNAP
Since a car payment can’t be deducted, it helps to know what genuinely can be, so you don’t under-report and lose benefits you’re entitled to.
- Shelter costs: rent or mortgage, property taxes, homeowners insurance, and utilities (heating, cooling, electricity, water, phone) that exceed half of your income after other deductions
- Dependent care: what you pay for child care or care for an adult dependent so you can work, look for work, or attend training/school
- Medical expenses: out-of-pocket costs above $35/month, but only for household members who are elderly or disabled
- Child support: legally owed payments you make, deductible in states that allow it
One nuance worth knowing: if you’re self-employed and use your vehicle for the business — delivery driving, rideshare, a mobile trade — the actual business costs of operating that vehicle (not the loan payment itself, but things like gas, maintenance, and mileage tied to work use) can be subtracted from your self-employment income before SNAP calculates your benefit. That’s a completely different mechanism than a personal car payment and applies only to the business-use portion.
How to Apply and What Documents to Bring
Reporting your finances accurately matters more than the car payment itself. You’ll apply through your state’s SNAP agency, either online or at a local office, and most states require a phone or in-person interview as part of the process.
Bring or upload:
- Proof of identity (ID, driver’s license)
- Proof of residency
- Proof of income for every working household member (pay stubs, self-employment records)
- Proof of shelter and utility costs
- Vehicle registration or title, if you live in one of the seven asset-test states above
- Proof of any dependent care or medical costs you want deducted
You don’t need to bring car loan paperwork specifically for the payment amount, since it isn’t part of the calculation — but your caseworker may still ask about the vehicle itself if your state runs an asset test, so having the title or registration handy speeds things up.
Frequently Asked Questions
Do Car Payments Count for SNAP Benefits?
No. A car loan payment is not on SNAP’s list of allowable deductions, so it does not lower your countable income or change your benefit amount. SNAP only deducts specific costs: a standard deduction, 20% of earned income, dependent care, medical expenses for elderly or disabled members, excess shelter costs, and in some states child support.
Can You Own a Car and Still Get SNAP?
Yes. Owning a car does not disqualify you from SNAP. In 39 states plus D.C., vehicle ownership doesn’t factor into eligibility at all because those states have waived the asset test. Even in the seven states that still test vehicle value, one car per adult household member is automatically excluded regardless of what it’s worth.
Does a Car Count as a Resource for SNAP?
Only in states that still apply the SNAP asset test (Kansas, Mississippi, Missouri, South Dakota, Tennessee, Utah, and Wyoming, as of current federal guidance). In those states, a household’s first vehicle per adult is excluded, and any additional vehicle only counts above $4,650 of fair market value. In the other 39 states plus D.C., a car is never counted as a resource because there’s no asset test to begin with.
What Is the SNAP Vehicle Value Limit?
Under the federal SNAP rule, one vehicle per adult in the household is excluded no matter its value. For any additional vehicle, only the fair market value above $4,650 counts as a resource. This threshold applies only in the states that haven’t adopted Broad-Based Categorical Eligibility; some of those states, like Texas, have set their own higher exclusion amount instead.
What Bills Count Toward SNAP Deductions?
Eligible deductions include rent or mortgage, utilities, property taxes and homeowners insurance (as part of the shelter deduction), dependent care costs, out-of-pocket medical expenses above $35/month for elderly or disabled household members, and, in some states, legally owed child support. Car payments, credit card debt, and most other consumer loans are not included.
Does Buying a New Car Affect My SNAP Benefits?
It depends on your state and how you pay for it. In BBCE states (most of the country), buying a car has no effect on SNAP eligibility. In one of the seven asset-test states, financing the purchase (rather than paying cash) generally has less impact on your resource count, since a financed vehicle’s equity is usually low, and cash spent on a down payment reduces the savings that would otherwise count as a resource. The safest move is to report the purchase to your caseworker and let them run the numbers for your specific household.
Conclusion
A car payment, by itself, does not affect your SNAP eligibility or benefit amount — it isn’t part of the deduction formula in any state. What can matter is your vehicle’s value, and only if you live in one of the seven states that still run a SNAP asset test, and only above the $4,650 exclusion for any vehicle beyond your first. Report your car, your income, and your actual bills accurately, and let your caseworker confirm which rules apply in your state.
If you’re unsure how your state handles this, the fastest way to know for certain is to ask your local SNAP office directly — rules on vehicle exclusions and BBCE status do change over time.