Compare Car Insurance by State: 2026 Rate Guide
Car insurance rates can differ by more than double depending on which state you live in, even with the identical driving record and coverage level. In 2026, the national average sits around $205–$210 a month for full coverage, but that ranges from about $128 a month in Vermont to more than $335 a month in Nevada.
That gap adds up to roughly $2,000–$2,500 a year between the cheapest and priciest states, driven mostly by factors you cannot control from behind the wheel: whether your state has no-fault insurance laws, how much coverage the state legally requires, how often severe weather generates claims, and how crowded and litigious the roads are.
This guide compares average rates across states, explains why the differences exist, breaks down full coverage versus state-minimum coverage, and covers the personal factors that move your own rate no matter where you live.
National Car Insurance Rate Overview (2026)
Based on 2026 industry rate studies, the average full coverage car insurance policy in the U.S. costs roughly $205 to $210 a month, or about $2,450 to $2,500 a year. That figure covers liability, collision, and comprehensive coverage for a driver with a clean record. State-minimum liability-only coverage is dramatically cheaper — Forbes Advisor puts the national average for state-minimum coverage at about $703 a year, roughly 71% less than full coverage.
These are averages built from a standardized driver profile (typically a 30-to-40-year-old with a clean record and good credit), so your actual quote will move up or down based on your age, driving history, vehicle, location within the state, and the coverage limits you choose. Treat state averages as a starting point for comparison, not a quote.
DASH CAM FOR CLAIMS & ACCIDENT PROOF
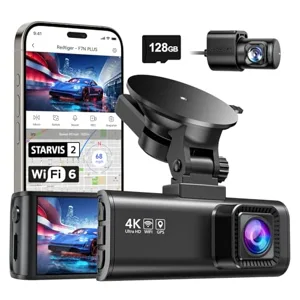 |
REDTIGER F7NP 4K Dash Cam Front Rear – $129.99 In no-fault and at-fault states alike, your own footage can speed up a claim and back up your side if fault is ever disputed after an accident.
|
Cheapest States for Car Insurance in 2026
The cheapest states for car insurance tend to share a pattern: lower population density, fewer congested cities, and lower rates of uninsured drivers and litigation. Vermont, Idaho, and Hawaii consistently rank at or near the bottom in 2026 rate studies, with Maine, Wyoming, and New Hampshire also landing in the bottom tier.
| Rank | State | Approx. Monthly (Full Coverage) | Why Rates Run Low |
|---|---|---|---|
| 1 | Vermont | ~$128 | Low population density, few big-city traffic claims |
| 2 | Idaho | ~$120 | Low cost of living and a low litigation rate |
| 3 | Hawaii | ~$127 | Lower average commute distances and traffic volume |
| 4 | Maine | Under $150 | Rural driving patterns, low uninsured-driver rate |
| 5 | Wyoming / New Hampshire | Under $150 | Very low traffic density statewide |
Figures are 2026 averages for full coverage compiled from multiple industry rate studies (ValuePenguin, Forbes Advisor); exact rankings shift slightly depending on the driver profile and methodology each study uses. Always get a personal quote — a young driver or someone with a recent claim will pay more than these averages in any state.
Most Expensive States for Car Insurance in 2026
Nevada, Louisiana, Florida, Connecticut, and Delaware are consistently the five most expensive states for car insurance, with average full coverage rates over $300 a month. Nevada tops the list at roughly $335 a month, more than 2.5 times what drivers pay in Vermont for the same coverage.
| Rank | State | Approx. Monthly (Full Coverage) | Why Rates Run High |
|---|---|---|---|
| 1 | Nevada | ~$335 | High urban traffic density and a high rate of uninsured drivers |
| 2 | Louisiana | Over $300 | High litigation rate and frequent weather-related claims |
| 3 | Florida | Over $300 | No-fault system, hurricane risk, and high uninsured-driver rate |
| 4 | Connecticut | Over $300 | Dense population and high vehicle repair costs |
| 5 | Delaware | Over $300 | Small state with high traffic density and high liability payouts |
Michigan deserves a mention even outside the current top five: its no-fault system historically produced some of the highest premiums in the country, largely tied to unlimited personal injury protection benefits before a 2019 reform capped them. If you are specifically weighing coverage requirements there, see our Michigan car insurance requirements guide.
Why Car Insurance Rates Vary So Much by State
State-by-state rate differences almost never come down to a single cause. A handful of structural factors stack on top of each other:
- No-fault vs. at-fault laws. Twelve states — Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania, and Utah — use no-fault systems where your own insurer pays your medical bills through Personal Injury Protection (PIP) regardless of who caused the crash. That usually means higher required coverage and higher premiums than a pure at-fault state.
- Minimum coverage requirements. States set their own legal minimums for liability coverage, and some require additional coverage like PIP or uninsured motorist protection. Higher mandatory minimums push the average premium up.
- Weather and catastrophe exposure. States that see frequent hurricanes, hail, flooding, or wildfire tend to have higher comprehensive claims, which raises rates for everyone in that state.
- Population density and traffic. More cars on the road in a smaller area means more accidents and more claims, which is a major reason urban states and states with dense metro areas skew expensive.
- Uninsured driver rates. States with a high percentage of uninsured drivers push up the cost of uninsured motorist coverage for everyone else.
- Litigation and repair costs. States with higher rates of lawsuits over accident claims, or higher average vehicle repair and medical costs, see that reflected directly in premiums.
Full Coverage vs. State-Minimum Coverage
Every state requires some form of liability coverage to legally drive (New Hampshire is the one notable exception, though most drivers there carry insurance anyway to cover financial responsibility requirements). What counts as the legal minimum, and how much it costs, varies a lot by state.
| Coverage Level | National Avg. Annual Cost (2026) | What It Actually Covers |
|---|---|---|
| State-minimum liability only | ~$703 | Bodily injury and property damage you cause to others; does not pay to repair or replace your own vehicle |
| Full coverage (liability + collision + comprehensive) | ~$2,450–$2,500 | Liability plus repairs or replacement for your own vehicle after a collision, theft, vandalism, or weather damage |
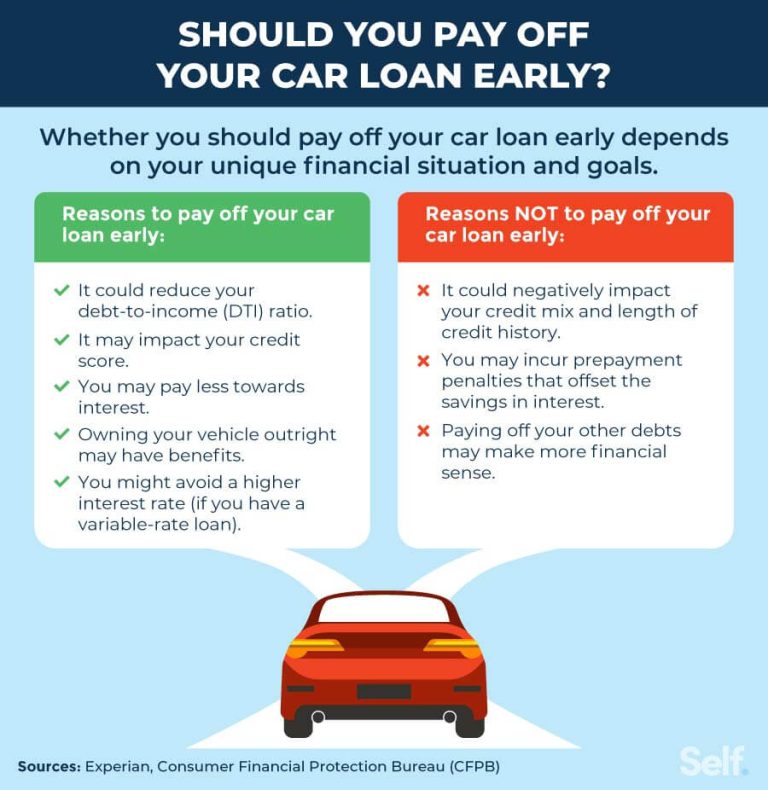
Minimum coverage is legal, but it is a financial gamble: if you cause a serious accident, you are personally on the hook for any damages beyond your liability limits, and minimum coverage will not pay a cent toward your own car. Most drivers with a car loan are required by the lender to carry full coverage anyway; if you own your car outright, weigh the cost of full coverage against what you could actually afford to pay out of pocket after a total loss. Because legal minimums change over time and by state, confirm your state’s current requirement with your state’s Department of Insurance or DMV before you buy.
Personal Factors That Move Your Rate Regardless of State
State averages only tell part of the story. Insurers price your individual policy using a mix of personal factors that matter just as much as your zip code:
- Age and experience. Drivers under 25 pay significantly more everywhere; rates typically level off by your late twenties to early thirties with a clean record.
- Driving record. A single at-fault accident or DUI can raise your premium by a large margin for three to five years, depending on the state and insurer.
- Credit-based insurance score. Most states allow insurers to factor in a credit-based insurance score, though California, Hawaii, and Massachusetts ban the practice entirely.
- Vehicle type. Expensive-to-repair vehicles, high-theft models, and high-performance cars cost more to insure than an economy sedan.
- Coverage limits and deductible. Higher liability limits and lower deductibles raise your premium; raising your deductible is one of the fastest ways to lower it.
- Annual mileage. Fewer miles driven generally means a lower rate, and some insurers offer usage-based programs that track mileage directly.
How to Compare Car Insurance by State and Actually Save
Whether you are relocating, renewing a policy, or just shopping around, the same process works everywhere:
- Get quotes from at least three to five insurers. Rates for the identical driver profile can vary by hundreds of dollars a year between companies in the same state.
- Compare identical coverage limits and deductibles across every quote, not just the bottom-line price.
- Ask each insurer about every discount you qualify for, including bundling, safe-driver, good-student, low-mileage, and defensive-driving-course discounts.
- Confirm your state’s legal minimum coverage, then decide honestly whether minimum coverage or full coverage fits your financial situation.
- Check the insurer’s complaint ratio through your state’s Department of Insurance before you buy — a cheap rate from a company that fights claims is not actually a good deal.
- Re-shop at every renewal, and especially after a move, a paid-off loan, or a few years of a clean driving record.
Looking for State-Specific Details?
This guide is built as a national comparison to show you how and why rates differ across state lines. For a deeper look at requirements and typical costs in a specific state, see our Massachusetts car insurance cost guide, which breaks down that state’s no-fault system and average premiums in more detail, or our Michigan car insurance requirements guide.
Frequently Asked Questions
What state has the cheapest car insurance in 2026?
Vermont has the cheapest average car insurance in 2026, at roughly $128 a month for full coverage. Idaho and Hawaii are close behind, with Maine, Wyoming, and New Hampshire also ranking among the five cheapest states in most 2026 rate studies.
What state has the most expensive car insurance in 2026?
Nevada has the most expensive average car insurance in 2026, at roughly $335 a month for full coverage. Louisiana, Florida, Connecticut, and Delaware round out the top five, all averaging more than $300 a month.
Why do car insurance rates vary so much by state?
Rates vary because each state sets its own minimum coverage requirements, uses either a no-fault or at-fault claims system, and has a different mix of population density, weather risk, litigation rates, and uninsured drivers. These factors combine to push average premiums up or down independent of your personal driving record.
Does my credit score affect my car insurance rate?
In most states, yes. Insurers are allowed to use a credit-based insurance score as one factor in pricing your policy, and drivers with poor credit typically pay more. California, Hawaii, and Massachusetts are the three states that ban this practice entirely, so credit history has no effect on your rate there.
Is state-minimum coverage enough, or should I buy more?
State-minimum coverage satisfies the law, but it typically only covers damage you cause to others and will not pay to repair or replace your own vehicle. If you have significant assets to protect or could not afford to pay for a serious accident out of pocket, full coverage with higher liability limits is worth the added cost.
How often should I compare car insurance rates?
Compare rates at every renewal, which is typically every six or twelve months, and any time your situation changes significantly — after a move, a paid-off car loan, a new vehicle, or a few years without a claim. Insurers frequently adjust pricing, so the cheapest company two years ago is not guaranteed to be the cheapest today.
Conclusion
Where you live is one of the biggest factors in what you pay for car insurance, but it is far from the only one. Vermont, Idaho, and Hawaii consistently offer the lowest average rates in 2026, while Nevada, Louisiana, Florida, Connecticut, and Delaware sit at the top. Whatever state you are in, the fastest way to actually lower your bill is the same everywhere: compare quotes from several insurers with matching coverage, ask about every discount you qualify for, and re-shop at renewal instead of letting your policy auto-renew year after year.