Do Car Dealerships Take Credit Cards? Fees, Limits & Surcharges
Some car dealerships take credit cards, but whether a card works for the full price, a down payment or only a service bill is the dealer’s own decision, and policies vary from one dealership to the next. If a surcharge is added, Visa’s published rules cap it at the merchant’s card cost or 3%, whichever is lower, and several states restrict it. This guide covers what a card can pay for, how surcharge rules work, which states restrict them, what card protections do and do not cover, and questions to ask before you pay. It is general information, not financial or legal advice.
Can You Really Buy a Car with a Credit Card?
Sometimes, yes, but the card is rarely the whole story. A dealership decides which payments it accepts by card, for what amounts and in which departments, so the only reliable answer comes from the dealer you plan to use. Three limits can apply at once: the dealer’s policy, any fee or surcharge allowed where the dealer is located, and your own card’s credit limit.
Money Basics Book Pick
 |
I Will Teach You to Be Rich: No Guilt. No Excuses. Just a 6-Week Program That Works (Second Edition)
|
As an Amazon Associate we earn from qualifying purchases. Spec-based pick from the listing, not a hands-on test.
The table sorts the common ways to pay and names each source and date.
| Payment method | What the sources say | Risk or note | Source and date |
|---|---|---|---|
| Credit card | A merchant may add a surcharge to credit cards in most states, capped at its card cost or 3%, whichever is lower | Dealer policy, state law and your credit limit all apply | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Debit or prepaid card | Visa says debit and prepaid cards cannot be surcharged, even if you choose “credit” at the terminal | The card still draws on your own account balance | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Cash discount offered by the dealer | Visa allows a merchant to display a card price, or card and cash prices side by side | A fee added at the bill may be treated as a surcharge | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Wire transfer | The FTC lists wiring money through a transfer company among payment methods scammers insist on | Confirm payment instructions with a phone number you looked up yourself | FTC, How To Avoid a Scam, July 2023 |
| Check or cashier’s check | The FTC warns that some scammers send a check that later turns out to be fake | Ask the dealer which check types it accepts and how long a deposit takes to clear | FTC, How To Avoid a Scam, July 2023 |
| Auto loan | The FTC says its credit card dispute process does not cover loans to buy cars | Terms come from the lender, not from the card network | FTC, Using Credit Cards and Disputing Charges |
What Part of the Bill Goes on the Card?
People search this question for four different payments, and the answer can differ for each one. A dealer that takes a card for a small service bill may handle a down payment or a full purchase differently, and no source cited here sets a standard limit for any of them. Treat each row below as a question to ask, not as a promise.
| What you want to pay | What to confirm with the dealer | Why it matters |
|---|---|---|
| Full purchase price | Maximum card amount, any fee, and what other payment type covers the rest | Your card limit must cover the whole amount at once |
| Down payment or deposit | Card limit, whether the deposit is refundable if financing falls through, and any fee | A deposit paid by card can be hard to unwind if the deal changes |
| Service and repairs | Whether the service department takes cards and whether a fee applies | Service and sales desks may follow different policies |
| Parts and accessories | Same questions as service, plus whether returns go back to the same card | Ask where a refund would be sent before you pay |
Our guide to what percent to put down on a car covers deposits, and how to pay for car repairs covers other ways to pay a service bill.
Why a Dealer May Limit or Pass On Card Costs
Visa explains that merchants pay a merchant discount to their own financial institution, typically calculated as a percentage of each transaction. Whatever the actual rate is, a percentage of a car-sized payment is a much larger dollar amount than the same percentage of a small bill, which is why a dealer may want a cap on card payments or may pass the cost on where the law allows. The rates in the table are hypothetical, chosen only to show the arithmetic. They are not any dealer’s actual rate.
| Amount charged (example) | At 1% | At 2% | At 3% |
|---|---|---|---|
| $500 service bill | $5 | $10 | $15 |
| $5,000 down payment | $50 | $100 | $150 |
| $30,000 purchase | $300 | $600 | $900 |
The 3% column matters because it is the ceiling in Visa’s surcharge rule: the surcharge cannot exceed the merchant’s card cost, or 3% if that cost is higher. On a $30,000 purchase that ceiling would be $900 at most. A real surcharge could be lower, and in some states it is not allowed at all.
State Laws and Credit Card Surcharges
Surcharge law is state by state. Per Visa’s merchant Q&A, the merchant outlet’s location decides which state law applies, so a dealership group with stores in several states can surcharge in one and not another. Visa’s own list, dated February 15, 2024 and described by Visa as possibly containing errors, is summarized below. Visa also says to consult a lawyer for legal questions.
| State or territory | What Visa says it understands | Source and date |
|---|---|---|
| Connecticut | Prohibits surcharging | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Maine | Prohibits surcharging; the statute (9-A M.R.S. section 8-509) bars a seller from imposing a surcharge on a cardholder who uses a credit or debit card instead of cash, check or similar means, and says a discount from the regular price is not a surcharge | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024; Maine Legislature statute page, extracted Oct. 2026 |
| Massachusetts | Prohibits surcharging | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Oklahoma | Prohibits surcharging | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Puerto Rico | Prohibits surcharging | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
| Colorado, Minnesota, New Jersey, New York | Have requirements for surcharging (details not given in the Q&A) | Visa U.S. merchant surcharge Q&A, version dated Feb. 15, 2024 |
Laws change, so confirm your state on its attorney general’s or legislature’s website. You can read the Visa’s U.S. merchant surcharge Q&A for the network rules behind this table.
Surcharge, Cash Discount or Convenience Fee: Know the Difference
Visa defines a surcharge as an additional fee a merchant adds to a bill for using a particular form of payment. According to Visa’s Q&A, a merchant that wants to offer a cash discount must display prices either only as the card price or as both card and cash prices side by side, and the total on a card cannot be reached by adding a fee at the end, because that may be treated as a surcharge under Visa’s rules.
- Notice: the merchant must notify its acquirer at least 30 days before it starts surcharging, and must disclose the practice at the point of entry, at the point of sale, and as a separate line on the receipt.
- Ask for both totals: if a quote rises only because of the card, ask whether it is a surcharge or a lower price for another payment type, and get both totals in writing.
For a related look at how a price can change on the way to signing, see the mark-up on a new car.
What Card Protections Do and Do Not Cover
The main reason people want to pay a dealer by card is protection, so it helps to know the limits. The FTC page on using credit cards and disputing charges says federal law limits your responsibility for unauthorized charges to $50. It also describes a billing error process: write to the issuer so the letter arrives within 60 days after the first bill with the error was sent, expect a written acknowledgment within 30 days, and a resolution within 90 days. The same page says this process does not cover loans to buy cars, so it does not reach a financing agreement you signed.
For a complaint about quality, the CFPB page on refunds for card purchases (last reviewed May 15, 2024) says to contact the seller first, then ask your card company about a chargeback. It lists conditions for refusing to pay the rest of a card purchase: a good-faith attempt to resolve the problem with the seller, a purchase in your home state or within 100 miles of your home address, a price over $50, and not yet having fully paid. Neither page promises a refund. Our guide to whether car dealerships accept credit cards goes deeper on dispute rights and documenting your payment, while this page focuses on what can be charged and what fees can apply.
Alternatives to Credit Cards for Buying a Car
If a card will not cover the amount, the options are other payments, financing or a mix. Each has its own risks, so compare them on the dealer’s written terms rather than on assumptions.
- Auto loan: cost and terms come from the lender; see our 0% interest on a new car page for how promotional rates work and what percentage of income should go to a car payment for budgeting rules.
- Cash: see our page on paying cash for a car at a dealership for how that process works.
If you sign a loan and then change your mind, see whether you can cancel a car loan after signing. For paying down a loan with a card, see how to pay a car loan with a credit card.
Questions to Ask the Dealer Before You Pay
- Do you take cards for this payment: a deposit, the purchase, service or parts?
- What is the largest card amount you accept, and what do you do with the rest?
- Is there a fee or surcharge for a credit card, and is it a percentage or a flat amount? Is there a cash price?
- Is the fee the same for debit? (Visa says debit cannot be surcharged.)
- Is a card deposit refundable if financing falls through, and to which payment method does a refund go?
- Can you put the policy, the total both ways and the refund terms in writing?
- Does my card issuer need a heads-up for a large charge, and what is my available credit today?
Common Mistakes
| Mistake | Why it matters | What the sources say |
|---|---|---|
| Assuming every department takes cards | Sales and service may follow different policies | Policies vary by dealer; ask each desk |
| Ignoring the surcharge until the bill | A fee can add hundreds on a large charge | Visa caps it at the merchant cost or 3%, lower in some states |
| Expecting a surcharge on debit | Visa says debit and prepaid cannot be surcharged | Visa Q&A, Feb. 15, 2024 |
| Treating a car loan like a card purchase | Card dispute rules do not cover loans to buy cars | FTC credit card page |
| Paying by wire to an unverified account | Scammers often ask for wire transfers | FTC, How To Avoid a Scam, July 2023 |
FAQs
Can I use a credit card to pay for a car in full?
It depends on the dealer. Card acceptance, the largest amount allowed and any added fee are the dealer’s own policy, and your card’s credit limit also has to cover the amount. Ask the finance office for its maximum card amount before you plan around a card.
Are there extra fees for using a credit card at a dealership?
Possibly. Under Visa’s rules a merchant may add a surcharge to credit cards only, never debit or prepaid cards, capped at the merchant’s card cost or 3%, whichever is lower, and some states prohibit surcharges. A posted cash discount is treated differently from a surcharge. Ask for the total both ways.
Do car dealerships take credit cards for service and repairs?
Many businesses take cards for smaller bills, but each dealership sets its own policy for its service and parts departments. State surcharge law and Visa’s surcharge rules apply to any merchant location, so ask the service desk whether a card fee applies before you authorize the work.
Can you pay off a car loan with a credit card?
That is a separate question from buying the car, and it depends on the lender. The FTC notes its credit card dispute process does not cover loans to buy cars.
Does paying by card protect me if something goes wrong with the car?
It can help in some situations. The FTC describes a billing error process with set deadlines, and the CFPB lists conditions for refusing to pay the rest of a card purchase, including a price over $50 and a purchase in your home state or within 100 miles of your home address. Neither page promises a refund.
Which states do not allow credit card surcharges?
Visa’s Q&A, in a version dated February 15, 2024, says Visa understands that Connecticut, Maine, Massachusetts, Oklahoma and Puerto Rico prohibit surcharging, and that Colorado, Minnesota, New Jersey and New York have requirements for it. Check your state attorney general’s page.
Conclusion
Do car dealerships take credit cards? Some do, with limits that differ by dealer and by payment type. Before you plan around a card, confirm the maximum amount, any fee and the refund terms, and check your state’s surcharge rules.
What this guide does not cover: your personal finances, your card’s terms, or the policy of a particular dealership. It is general information and not financial or legal advice. Figures and rules are as published by each source on the dates given.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 Portable Car Heater Car Heater, Portable Electronic Auto Heater Fan Fast Heating Defrost 12V 120W Car Defrost Defogger, 2 in 1 Heating/Cooling Function 3-Outlet, Plug Adjustable
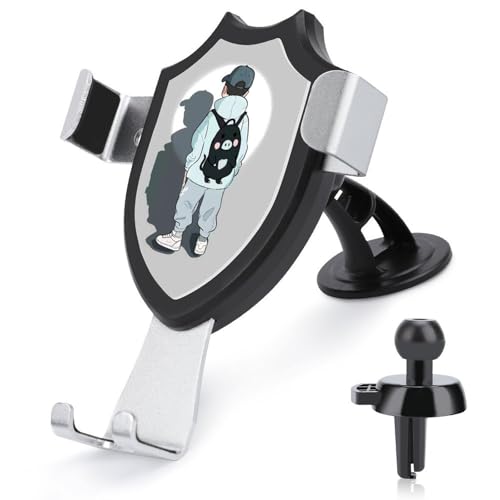 Falynth Back View Boy Car Phone Holder Vent Mount – Universal Dashboard Air Outlet Cell Stand, Adjustable Hands-Free Cradle for All Smartphones