Do Car Dealerships Check Equifax or TransUnion?
Car dealerships often pull the credit bureau tied to the lender or financing program they plan to use, so the pull may hit one bureau or more than one. A surprise hard inquiry can trim your score, add more pulls, and make rate shopping harder. This guide explains how dealers choose a bureau, how to ask before you apply, and how to verify the pull afterward.
Do car dealerships check Equifax or TransUnion for loans?
Yes. The dealer usually follows the lender’s program rules instead of picking a bureau on its own. In many auto deals the pull is Equifax, TransUnion, or Experian, and the finance partner decides which file gets accessed. The showroom is only one part of the decision.
The lender program usually decides
Dealerships may pull whichever bureau their financing partner defaults to. That is the simplest way to think about it. If the dealer sends your application to a lender that prefers TransUnion, that is the file likely to be checked first. If the loan is bank-backed, Equifax may be the file pulled instead.
TransUnion is often the default first hard pull in many dealer workflows, but that is not universal. Franchise dealers often use TransUnion through lender contracts, while independents and buy-here-pay-here lots often start with Equifax. Some dealers use both bureaus when shopping multiple lenders, and some may involve Experian as well.
Why the showroom is not the whole story
Dealers do not all follow one credit rulebook. Their finance affiliation, captive lender ties, and loan software can point them toward one bureau or another. A dealership tied to a manufacturer finance arm may work differently from an independent lot using a local bank or credit union.
Captive finance arms such as Ford Motor Credit and GM Financial can steer bureau use through long-standing contracts. Some dealers prefer TransUnion because lenders feed loan-approval software with it. Others may query Equifax through bank-backed programs or sub-prime auto channels.
Which credit bureau do car dealerships use most often?
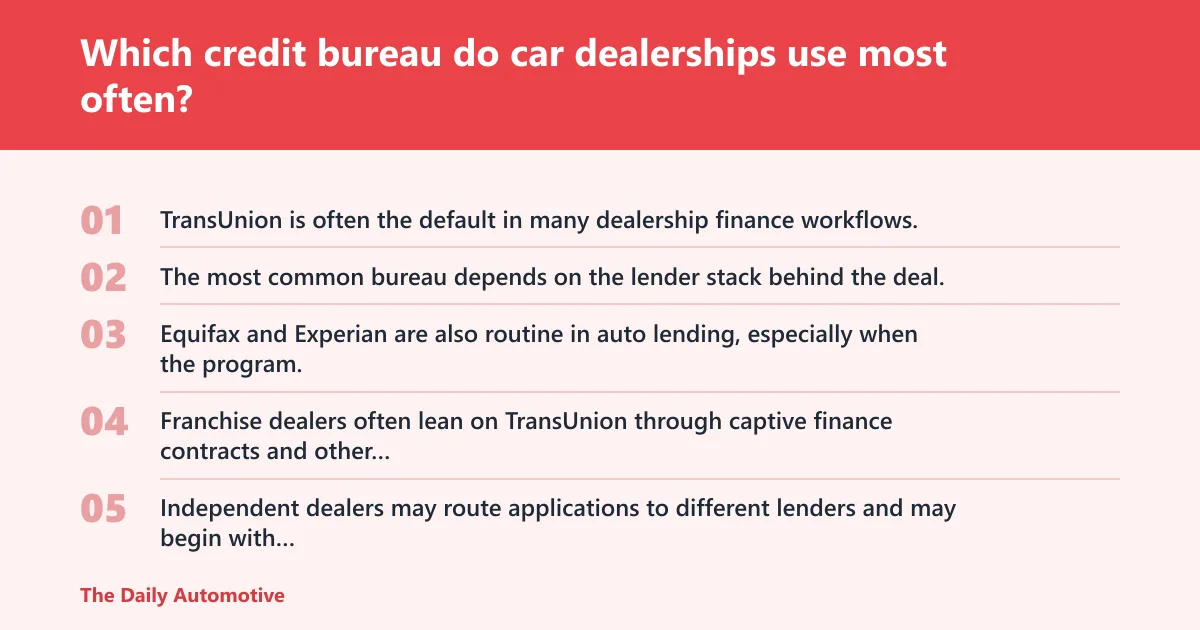
TransUnion is often the default in many dealership finance workflows, but there is no single bureau every dealer uses. The most common bureau depends on the lender stack behind the deal. Equifax and Experian are also routine in auto lending, especially when the program, software, or lender contract points that way.
How lender type shifts the likely bureau
Franchise dealers often lean on TransUnion through captive finance contracts and other manufacturer-linked programs. Independent dealers may route applications to different lenders and may begin with Equifax more often. Credit unions and banks can be even more variable because each institution sets its own pull policy.
FICO Auto Score versions can also be bureau-specific, which matters because a consumer may score differently at each bureau. A lender may see one auto score at TransUnion and a different one at Equifax or Experian. That is one reason the same shopper can get different rate quotes from different finance paths.
What if one bureau file is thin or frozen?
If one bureau is frozen, missing, or thin, the dealer may switch to another bureau or lender. That can produce a different score and a different rate decision. A file can also be present at one bureau and sparse at another, which is why a clean pre-shop review matters.
Suppose your TransUnion file is frozen before you visit a franchise store. The finance office may either ask you to lift the freeze or send the application to a different lender that can work from another bureau. That change can create a second inquiry if the first submission already hit one bureau.
Will a dealer pull all 3 credit bureaus for an auto loan?
Sometimes, but not always. Some dealerships and lenders request a tri-merge credit report, which combines the three major credit bureaus. Others pull only one bureau first and expand to a second or third bureau only if the initial lender review needs more information or if the dealer is shopping multiple lenders.
When a tri-merge report matters
A tri-merge credit report helps compare differences across bureaus, especially when one file has more recent payment data or a score gap. It is more common in some mortgage settings, but it can appear in auto finance workflows too. The key point is that a tri-merge report is not the same thing as three separate hard inquiries.
Multiple lender submissions can create more than one inquiry
The article says multiple dealer inquiries may be bundled within a short window, and the bundling window is usually 14-45 days. That matters because a dealer might submit your application to more than one lender. Even if the process starts with one bureau, a second lender submission can add another hard inquiry.
Hard pulls are still real pulls. They can affect score, even if scoring models often treat shopping-related auto inquiries as a cluster instead of a string of separate mistakes. Bundling does not erase the inquiry; it changes how scoring systems may count it.
Can I ask a dealer which bureau they will use before they run my credit?
Yes, and you should. The easiest way to avoid surprises is to ask the salesperson or finance office which bureau and which lender they plan to use before they submit the application. The article says you can ask the salesperson which bureau they plan to use, and that question belongs early in the conversation.
Ask for the bureau and the lender name
Do not stop at “Which bureau do you use?” Ask which lender program the dealer is sending the application to. That gives you the real answer because the lender often determines the bureau. It also tells you whether the pull is likely to be a bank, captive finance arm, credit union, or sub-prime route.
What to say at the finance office
- Ask which lender they plan to submit to first.
- Ask which bureau that lender usually pulls.
- Ask whether the application will go to more than one lender.
- Ask whether they expect a hard pull or a soft prequalification.
- Ask which documents they need to quote accurately without extra submissions.
How do I see whether a dealer pulled Equifax or TransUnion?
You confirm the bureau by reading the hard inquiries section on your credit report. That is the clearest post-application clue. A hard inquiry appears on the bureau report itself, and the wording usually identifies the creditor or finance source that accessed the file. The bureau name is often visible there too.
Where to look on the report
Check the hard inquiries section of free reports from each bureau. The article says you can request free reports from all three bureaus via annualcreditreport.com. Review Equifax, TransUnion, and Experian separately because the dealer may have pulled only one of them.
How to read the inquiry line quickly
The inquiry entry usually lists the creditor or dealer name, the date, and the type of pull. Look for wording tied to auto financing, a bank, a captive lender, or the dealer’s finance company. If the entry sits in the hard inquiries section, it is the line that most directly tells you which bureau was accessed.
| Dealer type | Likely bureau behavior | What to check in the report |
|---|---|---|
| Franchise dealer | Often TransUnion through lender contracts; may use Experian or another bureau depending on the finance program | Hard inquiries section for the lender name and bureau-specific pull |
| Independent dealer | Often Equifax first, but may route to different lenders or use more than one bureau | Look for multiple inquiries if the dealer shopped more than one lender |
| Credit union | Uses its own lending policy; bureau choice varies by institution | Match the inquiry to the credit union or its loan partner |
| Bank | May query Equifax or another bureau based on bank policy | Check for a direct bank inquiry in the hard inquiries section |
| Buy-here-pay-here dealership | May use different reports, often Equifax or regional bureaus | Confirm whether the pull came from a standard bureau or a specialty file |
How to tell a dealer pull from a lender pull
A dealer pull is often just the front end of a lender application. The inquiry line may show the financing company rather than the showroom name. That is normal. What matters is the creditor listed in the hard inquiries section, because that is the entity that actually accessed the file.
How to protect your credit before the dealership visit
Start by checking all three reports at AnnualCreditReport.com before shopping. That lets you spot errors, freezes, thin files, and existing inquiries before a dealer submits anything. If a bureau is frozen, you can lift it in advance so the application does not stall or trigger a second submission.
Pre-shop checklist
- Pull Equifax, TransUnion, and Experian reports.
- Review the hard inquiries section on each report.
- Check for freezes, thin files, or outdated address data.
- Dispute obvious errors before applying if time allows.
- Bring proof of income, insurance, residence, and trade-in payoff details if needed.
Documents that help the finance office quote accurately
Bring recent pay stubs or other income proof, a government ID, proof of residence, and insurance information if available. If you have a trade-in, bring the title, lien payoff amount, and registration. Clear documents can reduce repeated lender submissions and help the office choose the right program sooner.
Do multiple dealer credit pulls hurt my score?
Hard inquiries can affect score, but auto shopping has a special rule in many scoring models. Multiple dealer inquiries may be bundled within a short window, which helps limit damage when you are rate shopping. Even so, separate applications outside that window can still create separate inquiries and more score pressure.
Hard inquiry versus soft inquiry
A hard inquiry is a credit check tied to a real loan application. It appears in the hard inquiries section and can impact your score. A soft inquiry is often used for prequalification, identity review, or account monitoring, and it does not carry the same score risk as a hard inquiry.
When repeated applications still matter
If a dealer submits your application to several lenders, each lender may place its own inquiry. That is especially relevant when the dealer starts with one bureau and then asks another lender to review the deal through a different bureau. A short window helps with scoring treatment, but it does not make the inquiries disappear.
Why would one dealership pull TransUnion and another pull Equifax?
The difference usually comes down to lender contracts, software workflows, and the dealership’s finance affiliation. TransUnion is common in many dealer systems, but Equifax is also routine, especially in bank-backed or independent-lot financing. Experian may be first at some stores, particularly where a lender or scoring platform prefers it.
Lender contracts and scoring tools
Some lenders seem to feed auto-approval software with one bureau more than another, so the dealer uses the file that the system reads most cleanly. Captive finance arms often have long-standing TransUnion contracts. Bank-backed loans may query Equifax. That is why the bureau choice is a program decision, not a showroom preference.
How bureau gaps can change the result
Cross-bureau score gaps happen when one bureau has stronger, newer, or cleaner data than another. A shopper may qualify at one bureau and miss the mark at another because the FICO Auto Score version or account data differs. If one file is thin, the lender may see less history and price the deal differently.
A common first-timer mistake is assuming a preapproval at one bureau guarantees the same result everywhere. It does not. If the lender uses another bureau, the file may look older, thinner, or more volatile, and the quote can change.
What’s the difference between an auto hard inquiry and a soft inquiry?
An auto hard inquiry is a formal credit pull tied to a loan application, and it can affect score. A soft inquiry is a less formal review used for prequalification or account checks. In dealership finance, the hard inquiry is the one that matters for bureau tracking because it appears in the hard inquiries section.
Why shoppers should care
Hard inquiries are the clue you use to identify which bureau was accessed. They also tell you that the application moved past casual screening. Soft pulls can help with initial estimates, but a real auto loan decision usually ends with a hard inquiry once the finance office submits the deal.
Do buy-here-pay-here dealerships use different credit bureaus?
Yes. Buy-here-pay-here dealerships are a major exception because they often operate outside standard lender workflows. They may use one major bureau, a regional bureau, or a different report entirely. That means the bureau logic can change faster than it does at a franchise store tied to one lender ecosystem.
Why this segment is different
These lots often make in-house credit decisions or work with specialty finance channels. As a result, the report they rely on may not match what a bank or captive lender would pull. If you are shopping there, ask directly which report they use and whether the inquiry will appear on one of the three major bureaus.
How can I check my credit before visiting a car dealership?
Pull all three credit reports before you shop, then review each hard inquiries section and any score differences. AnnualCreditReport.com is the standard place to request those free reports. Checking ahead also helps you spot errors, frozen files, and bureau-specific gaps before the dealer sends an application.
What to look for before you go
Focus on payment history, open balances, recent inquiries, and any collection or address errors that could confuse an auto lender. Dealers also review debt-to-income ratio, income stability, and the rest of the application package. The cleaner your files, the easier it is to predict which bureau and lender path will be used.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.