Do You Get a Title When You Finance a Car? Who Holds It
When you finance a car, the lender usually controls the title record until the loan is paid off; you may have possession of the car, but the lender typically keeps the lien and may hold the paper or electronic title record. If you miss this, you can delay registration, selling, or payoff processing, and you may not know who must release the lien. This guide explains who holds the title, how paper and electronic titles work, and what changes after payoff. Reviewed against state DMV/MVD guidance, AAMVA resources, and lender payoff servicing instructions where applicable.
Title decision table
This table separates the car, the paper or electronic record, and the next document you should expect. That split matters because ownership, registration, and title control do not always sit with the same party during the loan term.
| Financing scenario | Who controls the title record | What document the buyer should expect next |
|---|---|---|
| Standard finance | Lender | Loan paperwork and later a lien release after payoff |
| Electronic Lien and Title state | DMV | Electronic title notice or lien release confirmation |
| Refinance | New lender or DMV, depending on state system | New payoff statement and updated lien record |
| Lease | Lease company | Lease-end instructions or purchase option paperwork |
| Payoff failure case | Lender until the lien is cleared | Proof of payoff, then a corrected lien release request |
Do you get the title when you finance a car?
Usually, no. While the loan is active, the lender typically keeps control of the title record because it has a security interest in the car. In many states, you may not receive a clean, lien-free title until the loan is paid off and the lien release is recorded.
What a car title shows
A car title is the state-issued document tied to the vehicle identification number, the owner name, and any lien information. It is the DMV’s proof-of-ownership record for the vehicle, not a receipt for your loan payment. A clear title shows no liens. A liened title shows a lender.
The DMV is commonly the record keeper for title status. If the title is paper-based, the state may issue a paper certificate. If the title is electronic, the record exists in the DMV system and may never be printed while the lien is active.
In practice, the person driving and registering the car is the registered owner. That person may be listed on the title record, but the lender can still appear as lienholder until the debt is satisfied.
Who holds the title on a financed car?
The lender usually holds the title record or controls it through the DMV, and the borrower is the registered owner. Those are related but not identical roles. The lender’s name appears as lienholder because the loan creates a security interest in the vehicle until payoff.
Registered owner versus lienholder
The registered owner is the person or business allowed to register and drive the car. The lienholder is the lender that has a legal claim on the vehicle as loan collateral. If the borrower defaults, that security interest gives the lender the right to repossess, subject to state law and contract terms.
That is why “who owns the car” and “who holds the title” are different questions. A financed buyer can own the vehicle in the practical sense of using it, insuring it, and registering it, while the title record still shows a lender’s lien.
Say your sedan is financed through a local credit union and the title shows both your name and the lender’s lien. You still register and insure the car, but you should not expect a clean title in your hand until the loan balance is paid and the lien release is filed.
What the lender can do after default
If payments stop, the lender can act on its security interest. That does not mean the lender “owns” the car in the casual sense, but it does mean the lender can repossess the vehicle if the contract and state law allow it. The lien is the mechanism that protects the lender’s claim.
How electronic lien titles work
ELT systems keep the title record electronically while a lien is active. In those states, neither the borrower nor the lender may hold a paper title, because the DMV stores the title data and records the lien release electronically when the loan is paid off. AAMVA’s ELT materials describe ELT as a state-administered system that replaces paper title handling for liened vehicles in participating jurisdictions.
What ELT changes for paper titles
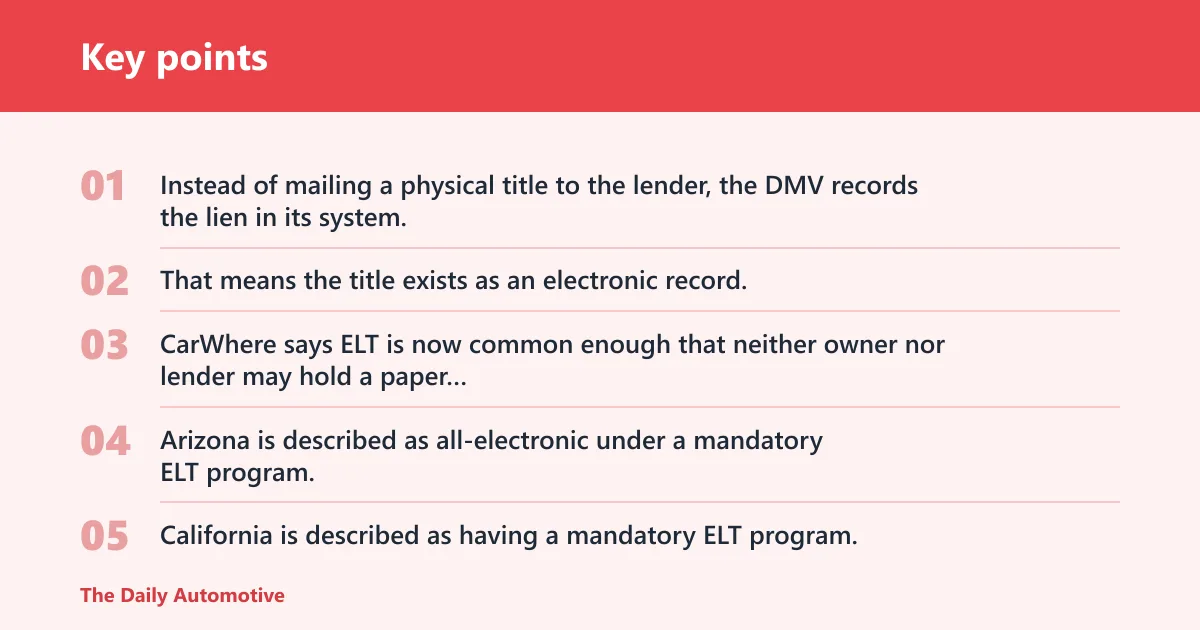
ELT changes the old paper-shuffling model. Instead of mailing a physical title to the lender, the DMV records the lien in its system. That means the title exists as an electronic record, and state procedures determine whether any paper document is issued at all during the loan.
CarWhere says ELT is now common enough that neither owner nor lender may hold a paper title. Arizona is described as all-electronic under a mandatory ELT program. California is described as having a mandatory ELT program. Florida is described as an ELT state.
Those state-specific adoption claims should be verified directly with the applicable DMV/MVD or title bureau before relying on them, because state program rules, mandatory-participant thresholds, and county-level procedures can change. For current title-holding rules, use the state DMV or MVD site for the vehicle’s titled state rather than a secondary summary.
What the DMV does in an ELT state
The DMV records the lien, updates the title data, and processes the release when the loan is paid. That is why a payoff can be complete before any paper appears. In an ELT system, the lender’s release goes straight into the state record rather than into a mailed certificate.
How do state title-holding rules vary?
State rules differ on two separate questions: who can hold a physical title during the loan, and how the lien is recorded. Some states use paper titles with the lender as physical holder, some use ELT for at least part of the lending market, and some require electronic recording for certain lienholders only. That means a borrower in one state may receive a mailed title after payoff, while a borrower in another state may only see an electronic status change in the DMV record.
Examples of state variation
Examples from state systems include ELT or electronic-title programs administered through DMV/MVD systems, such as Arizona, California, Florida, Georgia, Illinois, Maryland, Michigan, and Oklahoma. The exact rule can depend on whether the vehicle was titled there, whether the lienholder is enrolled in ELT, and whether the state requires paper titles to be converted to electronic records.
Because title-holding and lien-recording rules can differ by state, always verify the current process with the state DMV or MVD before attempting a sale, refinance, duplicate title request, or payoff follow-up. AAMVA’s ELT guidance and state DMV pages are the best starting points for current procedure.
What changes after payoff?
After payoff, the lender must release the lien so the title can become clear. The payoff statement shows the exact balance needed to close the loan. Once that amount is paid and posted, the lender sends a lien release or updates the electronic record, and the DMV can issue or update the title.
Payoff statement and final balance
The payoff statement is the amount needed to satisfy the loan on a specific date. It matters because the balance can differ from the regular monthly statement. Use the payoff figure when selling, refinancing, or closing a financed sale so the lender can release the title cleanly.
Picture a pickup with a trade-in offer that is only valid through Friday. You need the payoff statement before the dealer can close the deal, because the dealer must know the exact amount needed to clear the lender’s lien and finish the title transfer.
How long title delivery takes after payoff
Title delivery after payoff is not always immediate. In many states, the lender must first post the payoff, then transmit the release or clear the electronic lien, and only then can the DMV issue the next title status or mailed certificate. Some lenders’ servicing guides describe release processing as taking additional business days after payoff posting, and state DMV processing can add more time.
What affects the timing
Processing time depends on whether the title is paper or ELT, whether the payoff was submitted by the borrower or dealer, whether the lender batches releases, and whether the DMV mails a new title or updates the electronic record first. Common failure points include an incorrect payoff amount, a payoff received after the quote expiration, a payment sent to the wrong lockbox, or a name/address mismatch on the account.
If the payoff was made correctly but the title has not arrived, that delay can still be normal for a short period. The key check is whether the lender has actually released the lien in the DMV record and whether the account shows paid in full on the lender’s system.
What if the title never arrives after payoff?
If the title does not arrive after payoff, start by confirming that the lender posted the final payment and transmitted the lien release. Then check whether the DMV issued the document to an outdated address, whether the account was transferred to a new servicer, or whether the vehicle is in an ELT state and the updated title is only visible in the state record.
Common reasons for a missing title
Common causes include an unposted payoff, a lien release sent to the DMV but not yet processed, a lender merger or servicing transfer, a name change on the loan file, or a state requiring a separate paper-title request. In some cases, the release is correct but the borrower still needs to request a duplicate or corrected title from the DMV.
If the lender says the lien was released and the DMV still shows a lien, contact both the lender and the state title office with the payoff confirmation, account number, VIN, and any release reference number. If the lender cannot locate the release, ask for a reissue or corrected release package. If the DMV shows a clean record but no paper title has arrived, verify the mailing address and ask whether the state issues the title automatically or only upon request.
Selling, refinancing, or leasing with a lien
You can sell or refinance a financed car, but you need payoff coordination. The buyer, dealer, or new lender needs the payoff amount and the lien release process must be handled correctly. Leasing is different: the lease company usually holds title, while the driver is typically the registrant rather than the owner.
Selling a financed car
If the lender holds the title, you can still sell the car, but the sale must close around the payoff. Private-party buyers usually want a clean title, so you may need to pay the loan from the sale proceeds or arrange payment directly with the lender. The title cannot transfer cleanly until the lien is released.
Refinancing before the title clears
Refinancing replaces one lender with another. The old lender must receive its payoff and release its lien, and the new lender then records its own security interest. The borrower should not assume the old title record will update instantly; the DMV and the lenders have to complete the handoff.
Lease company title control
A leased car is not the same as a financed purchase. The lease company usually keeps title control because it is the vehicle’s titleholder, while the consumer is usually the registrant and driver. At lease end, a purchase option can transfer title if the lessee buys the car.
A common first-timer mistake is trying to treat a lease payoff like a loan payoff. They are not identical. With a lease, the path to title depends on the lease contract and the buyout process, not on simple loan satisfaction alone.
- Get the payoff statement before you list, sell, trade, or refinance the car.
- Confirm whether your state uses a paper title or ELT.
- Ask who will send the lien release and how it is recorded.
- Check the DMV record after payoff, especially if the lender merged or changed names.
- Do not finalize a private sale until the title can transfer cleanly.
Frequently asked questions
Does the bank keep the title until the loan is paid off?
Often yes, but state procedure matters. In many states the bank or lender keeps the paper title, while in ELT states the title may never be printed during the loan. Either way, the lender controls the lien until the account is satisfied.
What happens to the title after I pay off my car loan?
The lender releases the lien, and the DMV updates the title record. Depending on the state, you may receive a clear paper title by mail or an electronic confirmation that the title record is now free of the lender’s claim. Timing can vary.
Can I sell a car if the lender holds the title?
Yes, but the payoff has to be handled as part of the sale. The buyer or dealer needs the exact payoff amount, and the lender must release the lien before the title can transfer cleanly. Private-party sales are easiest when you coordinate the payoff first.
How do electronic lien titles work?
ELT means the DMV stores the title record electronically while the lien is active. The lender records the lien in the system, and the release is filed the same way after payoff. In those states, there may be no paper title in circulation during the loan.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.