Does American Express Cover Car Rental Insurance?
American Express can cover rental-car damage or theft on many U.S. cards, but only if your card includes the benefit, you charge the rental to that card, and the car, country, and rental type fit the program rules. Miss one condition and you may owe the deductible, the full repair bill, or face a denied claim. This guide shows how to check your card, country, and rental before you decline the counter’s coverage.
Does American Express cover car rental insurance?
Sometimes, yes. American Express rental-car benefits may help cover damage or theft on eligible cards, but the protection is not universal and is often secondary rather than primary. The exact answer depends on the card family, the benefits terms, the rental agreement, and where the car is picked up.
What Amex coverage can do, and what it usually cannot
Amex’s standard rental-car benefit is aimed at damage and theft to a rental vehicle, not every loss tied to the trip. It generally does not replace liability insurance, personal accident coverage, or roadside add-ons sold at the counter. Exclusions often apply for certain vehicles, certain countries, and unauthorized drivers.
That means “covered” does not mean “anything that happens at the rental desk or on the road will be reimbursed.” A scratched bumper may qualify under one card’s terms and fail under another card’s terms, even if both cards are issued by Amex. The benefit wording decides the claim.
Why the answer depends on the exact card and trip details
Coverage is tied to the cardmember guide and benefits terms, not to the Amex brand alone. Some cards include rental-car damage coverage automatically; others may require separate enrollment in a rental-car protection option. Trip details matter because the benefit can narrow by country, vehicle class, rental length, and whether the car comes from a traditional rental agency or a peer-to-peer platform.
Which Amex coverage applies to rental cars?
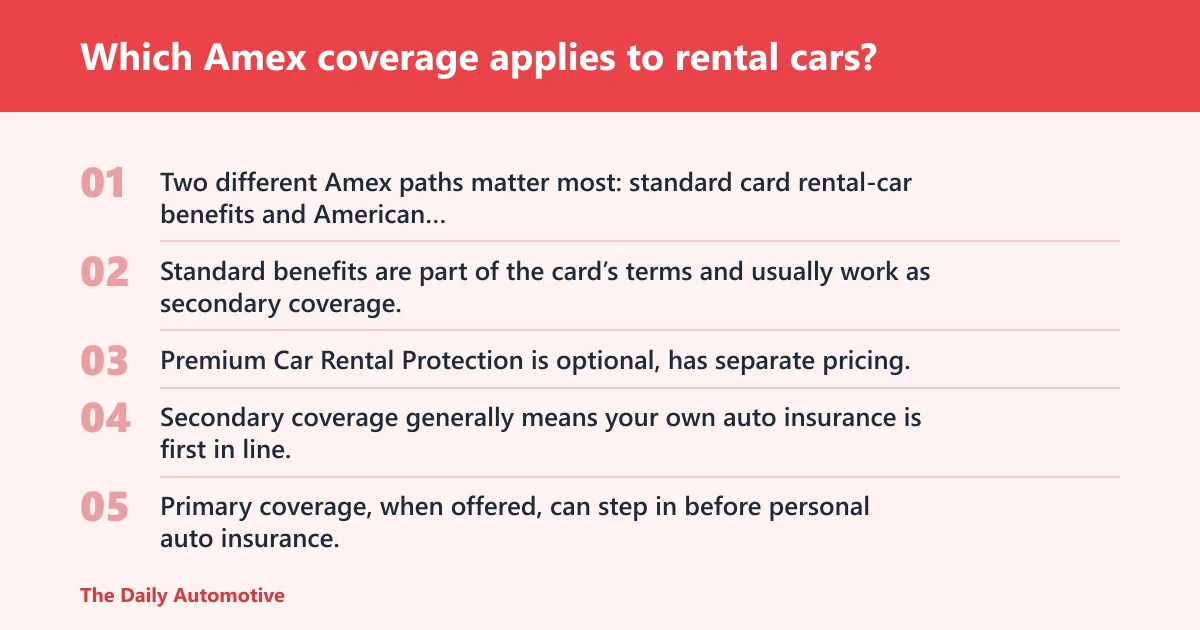
Two different Amex paths matter most: standard card rental-car benefits and American Express Premium Car Rental Protection. Standard benefits are part of the card’s terms and usually work as secondary coverage. Premium Car Rental Protection is optional, has separate pricing, and adds its own deductible and coverage cap rules.
Secondary coverage, optional enrollment, and deductibles
Secondary coverage generally means your own auto insurance is first in line, then the card benefit may cover eligible remaining damage after deductibles and limits. Primary coverage, when offered, can step in before personal auto insurance. The difference affects whether a claim starts with your insurer or with Amex.
Premium Car Rental Protection is not the same as the standard card benefit. It is an enrolled product available only on eligible cards, and pricing can vary by rental period or by annual enrollment, depending on the plan offered to the cardmember. The program also includes a coverage cap and deductible, so it is not open-ended protection.
How collision damage waiver language works
Collision damage waiver, or CDW, is the rental-agency term for protection against damage to the rental vehicle. Credit-card benefits may use CDW-like language, but the card benefit is still governed by the Amex program terms. The rental company can still ask you to accept or decline its own CDW or similar waiver.
That is where travelers get tripped up. The card may offer secondary rental-car coverage, yet the counter agent may sell a separate loss-damage waiver that is not required by the card benefit. If you buy duplicate coverage, the card may not reimburse that charge unless the terms explicitly allow it.
How do you know if your card is eligible?
Start with the cardmember guide and benefits terms for the exact card in your wallet. That document tells you whether rental-car protection exists, whether it is secondary or primary, whether Premium Car Rental Protection is available, and what activation steps are required. If the guide is silent, verify before declining the counter coverage.
Check whether the rental type and driver meet activation rules
Eligibility usually depends on charging the rental to the qualifying card, signing the rental agreement, and listing only authorized drivers. The rental period must fit the program’s time limits, and the vehicle class must fall within the covered categories. A card benefit can fail even when the card itself is eligible if any activation rule is missed.
- Read the cardmember guide for the exact card name.
- Confirm whether the benefit is standard coverage or Premium Car Rental Protection.
- Check the country where the rental begins.
- Verify the vehicle class and rental length.
- Make sure every driver is authorized on the contract.
- Keep the signed rental agreement and all damage paperwork.
What rental details can change the answer?
Country, vehicle class, rental length, and the rental platform can change the result fast. A card that covers a sedan in one country may exclude a luxury SUV, a van, or a rental picked up in a restricted region. Cross-border itineraries can also change eligibility once the car leaves the original rental country.
Country, region, and cross-border restrictions
International rentals can differ from U.S. rentals because some countries are excluded or treated under special rules. Europe, Ireland, Italy, and Mexico are common search terms because travelers often assume blanket coverage applies. That assumption is risky. The card terms may allow some rentals abroad while excluding others, or may require a separate review of local rules.
Cross-border travel can also matter. If the rental agreement allows travel from one country to another, the benefit terms may still narrow coverage once the vehicle crosses a border. Read the benefits guide first, then the rental agreement, because both documents can affect the final answer.
Vehicle class, rental length, and authorized-driver rules
Many card programs exclude certain vehicle classes such as exotic cars, large passenger vans, trucks, or specialty vehicles. Rental period limits also matter. A coverage period that works for a short business trip may fail on a long vacation rental. If the contract names a driver who is not authorized, the claim can be denied.
Picture a seven-day rental of a midsize sedan in Paris that is booked on an eligible card. If the car is on the covered vehicle list and the contract is signed correctly, the claim path looks much cleaner. Now picture the same trip with a luxury SUV or an extra driver added at pickup who never appears on the contract. Eligibility can change immediately.
Why Turo and similar platforms need separate review
Turo and other peer-to-peer rentals are often treated differently from traditional rental agencies. Some card benefits exclude them outright, while others require a separate written review of the benefit terms. Do not assume a normal car-rental benefit applies just because a vehicle is booked through an app.
A common first-timer mistake is treating a peer-to-peer booking like a standard airport rental. The platform may have its own insurance structure, but the Amex benefit may still exclude the transaction. Check whether the platform is named in the exclusion list before you rely on the card.
Coverage decision checklist by card, country, and rental type
Use this table as a fast eligibility screen before you decline counter coverage. The “likely eligibility” column is intentionally cautious. The cardmember guide and rental agreement remain the final authority.
| Amex card type | Rental country | Vehicle type | Rental platform | Likely eligibility | First document to request from the rental counter |
|---|---|---|---|---|---|
| Most U.S. Amex cards with standard rental-car benefit | United States | Compact, midsize sedan | Traditional airport or neighborhood agency | Often eligible if the card guide lists the benefit and the driver is authorized | Signed rental agreement showing the named driver and damage waiver choices |
| Eligible card enrolled in Premium Car Rental Protection | United States | Covered passenger vehicle class | Traditional agency | Often eligible, subject to the enrollment terms, cap, and deductible | Enrollment confirmation and rental contract |
| Amex Platinum or similar premium card with rental benefit | Ireland | Standard rental car, not specialty vehicle | Traditional agency | Possible, but only if Ireland is not excluded and the contract matches the benefit rules | Country-specific rental terms and the signed agreement |
| Eligible Amex card | Italy | Standard sedan or hatchback | Traditional agency | Possible, but verify Italy-specific terms before relying on coverage | Benefits guide page covering international rentals |
| Eligible Amex card | Mexico | Small SUV or sedan | Traditional agency | Possible, but local rules and country exclusions may apply | Country rules in the cardmember guide |
| Any Amex card | Any country | Exotic, luxury, oversized van, or specialty vehicle | Traditional agency or app-based platform | Often ineligible because of vehicle-class exclusions | Vehicle-class exclusion list |
| Any Amex card | Any country | Covered or excluded depending on terms | Turo or other peer-to-peer platform | Frequently ineligible or unclear without explicit benefit review | Written platform exclusion language |
What happens if you file a claim?
The claim path depends on whether the benefit is primary or secondary, what you bought at the counter, and which documents you saved. Secondary coverage usually comes after personal auto insurance, while primary coverage may pay first for eligible losses. If you miss paperwork, the claim can stall or fail.
Primary versus secondary claim order
With secondary coverage, your personal auto insurance is generally the first payer, then Amex may consider covered remaining loss. With primary coverage, the card benefit may start the claim process first. Premium Car Rental Protection has its own deductible and limits, so the payout math can differ from standard card benefits.
That sequence matters because duplicate add-ons can muddy the claim. If the rental desk sold a loss-damage waiver and the card benefit is also in play, the documents must show what was purchased, what was waived, and what damage occurred. The cleaner the contract trail, the better the claim review.
Documents you should keep from the rental counter and accident report
Keep the signed rental agreement, the pickup and return inspection sheets, the final receipt, photographs of damage, any police report, and the benefits guide page that shows the relevant coverage rules. If the claim involves a foreign rental, keep translated documents or the original language version if that is what the agency issued.
Say your rental gets a cracked taillight in Rome on day three. If the contract lists you as the driver, the vehicle class is covered, and the country is allowed, the claim may move forward. If the agreement names a second driver who was never authorized, that single detail can trigger a denial.
Does American Express include car rental insurance?
Some American Express cards include rental-car protection, but not all do, and the benefit may come through standard card coverage or a separate enrollment option. The exact cardmember guide controls eligibility, exclusions, and claim rules. Do not assume inclusion based on card prestige or annual fee alone.
Does American Express pay for car rental insurance?
American Express may pay for covered damage or theft tied to a qualifying rental, but it does not automatically reimburse every insurance charge at the counter. If the rental company sold duplicate coverage, Amex may not refund it. Payment depends on the benefit terms, the claim facts, and the paperwork.
Does American Express cover rental car insurance overseas?
American Express can cover some overseas rentals, but the answer depends on the country, the vehicle class, and the card’s international terms. Some regions have exclusions or special rules, and cross-border travel can change eligibility. The cardmember guide is the first place to check before you book.
Does American Express cover car rental insurance in Europe?
Sometimes, but not by default for every card and every European country. Europe is a common edge case because local rental rules, national insurance requirements, and country exclusions can all affect the result. Check the benefits guide for the pickup country and read the rental contract before declining coverage.
Does American Express cover car rental insurance in Ireland?
Coverage in Ireland is card-specific, not automatic. Some Amex cards may cover rentals there if Ireland is included in the benefits terms and the vehicle, driver, and contract meet the program rules. Other cards may exclude Ireland or limit what counts as a qualifying rental.
does american express cover car rental insurance in ireland
Check the exact cardmember guide for your card, then verify whether Ireland appears in the covered countries list. If the guide is unclear, treat the rental as ineligible until you confirm the terms. A signed rental agreement and the coverage section of the guide are the two documents that matter most.
Does American Express cover car rental insurance in Italy?
Italy is another country where the answer depends on the specific card and its international rental rules. Some Amex benefits can apply, but country exclusions, vehicle-class limits, and rental-agency terms still control the claim. Read the international coverage section before you accept or decline the agency’s waiver.
does american express cover car rental insurance in italy
Do not rely on a blanket yes or no for Italy. Use the benefits guide to confirm that Italy is allowed, then check whether the car type and rental platform qualify. If the rental is through a peer-to-peer platform or involves a specialty vehicle, separate review is necessary.
Does American Express cover rental car insurance in Mexico?
Mexico can be more complicated than a domestic U.S. rental because local rules and card exclusions may affect what is covered. Some cards may offer protection, but others may not. Before pickup, confirm whether Mexico is listed as a covered country and whether the rental agency requires a local waiver.
Does American Express cover rental car insurance for Turo?
Often, not in the same way as a traditional rental. Turo and similar platforms are commonly treated differently in card benefits, and some Amex terms exclude peer-to-peer rentals. Review the exact benefit language and platform rules before assuming the card will cover damage or theft on that booking.
Does Amex Platinum cover car rental insurance in Ireland?
Possibly, but the card name alone is not enough. The Amex Platinum card’s rental benefit still depends on the benefits guide, the pickup country, the vehicle class, and the rental agreement. Ireland-specific eligibility should be checked before travel, especially if you plan to decline the agency’s coverage.
Frequently asked questions
Does American Express cover car rental insurance?
Many Amex cards can cover rental-car damage or theft, but only when the specific benefit is included in the card terms and the rental meets the program rules. Coverage may be secondary, may exclude certain vehicles or countries, and may not apply to peer-to-peer rentals. The cardmember guide is the controlling document.
Does American Express include car rental insurance?
Some cards do, some do not. Inclusion depends on the exact card family and benefits package, not on the Amex brand alone. Check the cardmember guide for the rental-car section, the country list, and any exclusions before you rely on it at pickup.
Does American Express pay for car rental insurance?
Amex may pay for covered damage or theft tied to an eligible rental, but it does not automatically pay every waiver charge sold at the counter. If you bought duplicate coverage or rented a vehicle that falls outside the program rules, reimbursement may be denied or reduced.
Does American Express cover rental car insurance overseas?
It can, but overseas coverage is more sensitive to country rules, vehicle type, and trip structure than a domestic rental. Some countries are excluded, some require special handling, and cross-border travel can change eligibility. Verify the benefits guide for the pickup country before you travel.
Does American Express cover rental car insurance in Europe?
Sometimes, but Europe is not a single yes-or-no region for card benefits. Country-specific exclusions, local insurance practices, and rental-agency rules can all change the answer. Check the exact pickup country and the cardmember guide rather than assuming a Europe-wide benefit.
Does American Express cover rental car insurance for Turo?
Often, no, or at least not under the same rules as a traditional rental agency. Turo and similar peer-to-peer platforms are frequently excluded or treated separately in card benefits. Read the explicit benefit language before counting on Amex for that booking.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.