If I File Bankruptcy Will I Lose My Car? Chapter 7 vs 13 Rules
In most bankruptcy cases, you will not lose your car. If the equity in your vehicle falls under your state or federal exemption limit, and you keep making any required loan payments, you keep driving it.
The federal motor vehicle exemption is currently $5,025 per filer (in effect through March 31, 2028), and most states set their own limit instead — some far higher, a few lower. Your car is only at real risk when its equity (what it’s worth minus what you still owe) is larger than the exemption you’re allowed to claim, or when you fall behind on loan payments after filing.
This guide breaks down exactly how Chapter 7 and Chapter 13 bankruptcy treat a car you own outright versus one you’re still financing, what the motor vehicle exemption actually protects, and the specific tools (reaffirmation, redemption, and cram down) that can keep you driving even if you owe more than the car is worth.
Will Filing Bankruptcy Take My Car?
Usually not. Bankruptcy law separates your property into exempt and non-exempt assets. Exempt property, up to a dollar limit set by your state (or the federal exemption, in states that allow it), is protected from being sold to pay creditors. A car with equity under that limit is exempt — the bankruptcy trustee has no reason to touch it.
Equity is the key number, not the car’s sticker value. If your car is worth $12,000 but you still owe $10,000 on the loan, your equity is only $2,000 — comfortably under the federal $5,025 motor vehicle exemption. A car that’s paid off is where people most often run into a real risk of losing it, because 100% of its value counts as equity.
PROTECT YOUR CASE PAPERWORK
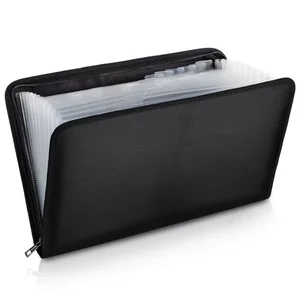 |
ENGPOW Fireproof Expanding File Organizer – $21.98 Your bankruptcy petition, exemption schedules, reaffirmation agreement, and court notices are documents you cannot afford to lose track of during a case that runs three to five years.
|
Chapter 7 vs Chapter 13: How Each Affects Your Car
The chapter you file under changes how your car is handled. Chapter 7 is a faster liquidation process; Chapter 13 is a repayment plan. Here’s how they compare on the points that matter most for a vehicle.
| Factor | Chapter 7 | Chapter 13 |
|---|---|---|
| Timeline | Typically 3-6 months | 3 to 5 years |
| How it works | Non-exempt assets can be sold to pay debts | You repay debts through a court-supervised plan |
| Non-exempt car equity | Trustee may sell the car and pay you the exemption amount | You keep the car but must pay non-exempt equity value to unsecured creditors through the plan |
| Behind on loan payments | Must catch up, reaffirm, or redeem to keep the car | Missed payments can often be rolled into the repayment plan |
| Reduce loan balance to car’s value | Not available (see redemption instead) | Available via cram down, with conditions (below) |
In practice, most people who file Chapter 7 with an average car and a normal amount of equity keep their vehicle without incident. The car only becomes a target for the trustee when its equity clearly exceeds what your exemption covers.
The Motor Vehicle Exemption, Explained
Every state lets you protect a set amount of car equity from creditors during bankruptcy — this is the motor vehicle exemption. The federal exemption, available in states that permit filers to choose it, is currently $5,025 per filer and is set to remain at that amount through March 31, 2028, before the next scheduled adjustment.
Several important caveats: about a third of states require you to use their own state exemption instead of the federal one, and those amounts vary widely — some states protect just a few thousand dollars of car equity, others protect far more. Many states, and the federal system, also offer a separate wildcard exemption that can be applied to any property, including extra car equity that goes over the motor vehicle limit. Married couples filing jointly can often double both exemptions.
Because these limits are state-specific and change periodically, don’t rely on a number you saw somewhere else online without confirming it for your state and filing date. A bankruptcy attorney (many offer a free initial consultation) or a local legal aid clinic can tell you the exact figure that applies to your case.
What Happens If You Still Owe Money on the Car
If you’re still financing your car, the exemption is only half the picture — you also have to deal with the loan itself. Bankruptcy gives you a few different tools, and which ones are available depends on which chapter you file.
Reaffirmation Agreement (Chapter 7 Only)
A reaffirmation agreement is a new, legally binding promise to keep paying your car loan under its original terms in exchange for keeping the car, even though the debt would otherwise be wiped out. It must be signed and filed with the bankruptcy court before your case closes. This option exists only in Chapter 7 — in Chapter 13, your repayment plan itself controls how secured debts like a car loan are handled, so there’s no separate reaffirmation step.
Redemption (Chapter 7 Only)
Redemption lets you keep the car by paying the lender its current replacement value in a single lump sum, rather than the full remaining loan balance. This is useful if you owe significantly more than the car is worth, but it requires cash upfront, so it’s less common than reaffirming or, in Chapter 13, using a cram down.
Cram Down (Chapter 13 Only, With Conditions)
A cram down lets you reduce your loan’s principal balance to match the car’s current market value, if that value is lower than what you owe. The catch: it’s only available in Chapter 13, and only if you bought the car at least 910 days (about two and a half years) before filing. The loan splits into a secured portion, equal to the car’s value, and an unsecured portion for the rest — the unsecured part gets treated like your other unsecured debt and can be significantly reduced or discharged through the plan.
If your car isn’t running or isn’t worth keeping at all, Chapter 13 also lets you simply surrender it as part of your plan instead of using any of the tools above — see our guide on what happens if you surrender a non-running car in Chapter 13 for how that process works.
Missing Payments After You File
Filing bankruptcy triggers an automatic stay, which temporarily stops repossession and other collection actions. It does not erase your obligation to keep paying a car loan you intend to keep. If you fall behind after filing — whether or not you signed a reaffirmation agreement or have a Chapter 13 plan — the lender can ask the court for permission to repossess.
State Laws Make a Real Difference
Because so much of this comes down to your state’s specific exemption amount and whether you’re allowed to choose the federal exemption instead, two people with an identical paid-off car can have completely different outcomes depending on where they live. Some states protect several times more car equity than the federal amount; others protect less and lean more heavily on a wildcard exemption to make up the difference.
Before you file, confirm three things with an attorney or your state’s official exemption statute: whether your state uses its own exemption or lets you pick the federal one, the current dollar amount for a motor vehicle, and whether a wildcard exemption is available to cover any equity above that limit.
How to Protect Your Car During Bankruptcy
- Talk to a bankruptcy attorney before you file. They can tell you your exact exemption amount and whether reaffirmation, redemption, or cram down makes sense for your situation.
- Get your car appraised or check a valuation site. Knowing the actual market value, not just what you assume it’s worth, is what your exemption calculation depends on.
- Keep paying the loan on time both before and after filing if you intend to keep the car — a bankruptcy filing doesn’t pause your loan obligations the way it pauses collection calls.
- Don’t transfer or sell property to a friend or relative right before filing to try to protect it — this can be treated as fraud and can backfire badly, including losing the exemption entirely.
- Ask about a reaffirmation agreement in writing if you’re filing Chapter 7 and want to keep a financed car, and make sure you understand and can genuinely afford the terms before signing.
- Build a realistic budget that includes the car payment, insurance, and maintenance — the court will want to see that you can actually sustain the payments going forward.
Frequently Asked Questions
Will I lose my car if I file Chapter 7 and it’s paid off?
Only if the car’s value is higher than your available exemption (the motor vehicle exemption plus any wildcard exemption you can apply to it). A paid-off car with modest value is usually fully protected. If it’s worth significantly more than your combined exemptions, the trustee could sell it and pay you the exempt portion in cash — though this is uncommon for an ordinary used car.
Can I keep my car if I still owe money on the loan?
Yes, in most cases. In Chapter 7 you can sign a reaffirmation agreement and keep paying under the original terms, or redeem it with a lump-sum payment. In Chapter 13, your repayment plan handles the loan directly, and you may qualify for a cram down that lowers the balance to the car’s current value if you bought it more than 910 days before filing.
What is the difference between an exempt and non-exempt car?
Exempt means your car’s equity falls at or below the dollar limit your state (or the federal system, where allowed) lets you protect from creditors. Non-exempt means the equity exceeds that limit, which is what puts a car at real risk of being sold by a Chapter 7 trustee to pay unsecured debts.
Is it worth fighting to keep my car in bankruptcy?
For most filers, yes — a car is often essential for getting to work, medical appointments, and daily responsibilities, and losing it can make recovering from bankruptcy harder rather than easier. That said, if your car costs more to insure and maintain than it’s worth, and it’s not covered by your exemption anyway, surrendering it can sometimes be the financially smarter move. An attorney can help you weigh the two.
What debts are not wiped out by bankruptcy?
Most student loans, child support and alimony, recent tax debts, and debts from fraud typically survive bankruptcy and still have to be paid. A secured car loan you want to keep the car under also has to keep being paid, whether through reaffirmation or your Chapter 13 plan, even though the underlying obligation could otherwise be discharged.
Does bankruptcy stop a car repossession?
Filing triggers an automatic stay that immediately stops most collection actions, including a scheduled repossession, the moment your case is filed. It’s temporary, though — if you stop making payments on a car you’re keeping and don’t work out an arrangement through reaffirmation, redemption, or your Chapter 13 plan, the lender can ask the court to lift the stay and proceed.
Conclusion
Filing for bankruptcy does not automatically mean losing your car. What actually matters is your car’s equity relative to your exemption, whether you’re still making loan payments, and which chapter you file. Chapter 7 protects exempt equity but requires you to stay current on any loan you want to keep. Chapter 13 gives you more built-in flexibility, including the ability to reduce an underwater loan balance through a cram down in the right circumstances.
Because exemption amounts and eligibility rules are state-specific and change over time, the single most useful step you can take is confirming your numbers with a bankruptcy attorney before you file, not after.