Trends Shaping the Future of the Car Industry Today
In 2026, the main commercially real auto-industry trends are likely EV cost-down, hybrids, software-defined vehicles, ADAS, and fleet connectivity; solid-state batteries, Level 4 autonomy, and flying cars still look pilot-stage. Miss that split and you risk betting on products, suppliers, and regulations that will not pay off on schedule. This guide ranks each trend by near-term business impact and separates real 2026 adoption from still-theory hype by segment and region.
Which car-industry trends matter most right now?
How to read the time-to-scale versus industry-impact matrix
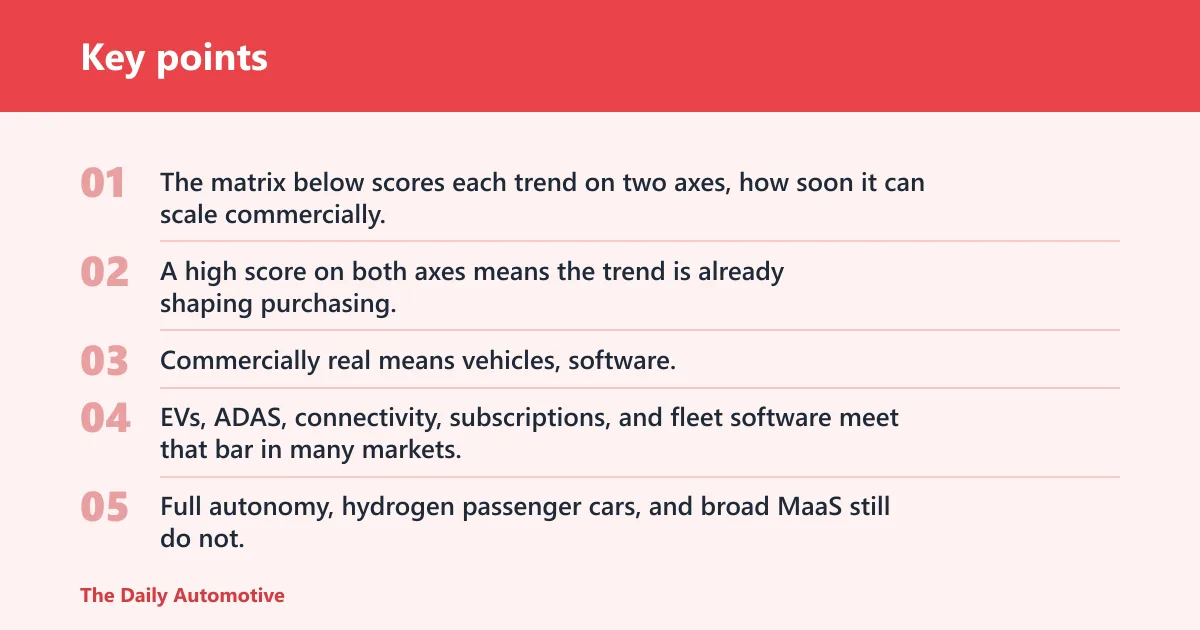
The matrix below scores each trend on two axes, how soon it can scale commercially, and how much it can move revenue, margins, or operating models. A high score on both axes means the trend is already shaping purchasing, platform choices, and capex plans.
| Trend | Time to scale | Industry impact | 2026 status | Readiness note for OEMs, suppliers, dealers |
|---|---|---|---|---|
| Electric vehicles | 5 | 5 | Scaling now | OEMs should keep lowering pack cost; suppliers should secure cells and power electronics; dealers need charging and service training. |
| ADAS and partial automation | 4 | 4 | Scaling now | OEMs should tighten validation and liability controls; suppliers must prove sensor fusion and software updates; dealers need clear feature explanations. |
| Software-defined vehicles and connected services | 4 | 5 | Scaling now | OEMs need OTA and cybersecurity plans; suppliers should shift to software and compute stacks; dealers should adapt to recurring-service sales. |
| Smart city integration | 3 | 3 | Pilot and local rollout | OEMs need standards-based V2I support; suppliers should focus on communications modules; dealers can treat it as fleet and municipal business. |
| Shared mobility | 3 | 3 | Mixed maturity | OEMs should watch fleet demand; suppliers can target high-duty components; dealers may gain fleet maintenance volume, lose retail conquest. |
| Servitization | 4 | 4 | Scaling now | OEMs should design subscription pricing carefully; suppliers should enable connected features; dealers need better contract and retention tools. |
| MaaS | 2 | 3 | Localized pilot | OEMs should target urban fleets; suppliers need fleet integration; dealers will see little retail change unless they support fleet access. |
| Hydrogen fuel cells | 2 | 2 | Limited commercial use | OEMs should reserve it for heavy or long-range use cases; suppliers face infrastructure risk; dealers should not count on passenger-car volume. |
What counts as commercially real in 2026
Commercially real means vehicles, software, or services can be sold at scale with known costs, clear regulation, and a working support network. EVs, ADAS, connectivity, subscriptions, and fleet software meet that bar in many markets. Full autonomy, hydrogen passenger cars, and broad MaaS still do not.
Why pilot-stage ideas should stay separate
Pilot-stage ideas can absorb capital without creating near-term volume. They may matter later, but in 2026 the business question is simple: can the technology ship, be insured, be serviced, and be financed at scale?
Electric vehicles: where adoption is real and where it is uneven
EV adoption keeps climbing worldwide, but the pace is uneven. China and parts of Europe still lead, while North America moves more steadily and many emerging markets run into price, grid capacity, and charging access limits.
Battery technology gains are lowering cost, extending range, and cutting charge times, which matters more than slogans. Charging stations support EV growth, but downtime, queueing, and uneven home-charging access still shape buyer decisions. Premium buyers can absorb those frictions more easily than mass-market households can.
Battery technology gains that affect cost, range, and charging time
The practical gains are familiar: better cell chemistry, more efficient thermal management, and improved pack integration. Those changes reduce cost per kilometer and shorten charging stops, which helps OEMs move EVs from compliance products toward mainstream lineups.
Mass-market EV adoption is still more sensitive to sticker price and charging convenience. Premium buyers will pay for longer range and faster charging, but volume growth depends on smaller packs, lower lease costs, and public charging that does not turn routine travel into a planning exercise.
Charging network expansion and the remaining bottlenecks
Charging buildout is real, but it is not the same as charging reliability. A highway corridor with enough plugs still fails if stations are offline, payment systems break, or high-power chargers are blocked by slower vehicles.
Suppose a suburban dealer sells a compact EV to a commuter with no garage outlet and one public charger within ten minutes. The sale looks fine on paper. The customer experience breaks the first week if evening charging queues make the car hard to use on a normal schedule.
Will self-driving cars become mainstream in the next decade?
Not in the full sense most people mean. Driver-assist systems will keep spreading, and some geo-fenced autonomous services will expand, but true self-driving at broad consumer scale faces sensor cost, software validation, liability, and regulation. The safety case is promising, yet deployment remains uneven and tightly constrained.
Driver-assist systems versus true self-driving
ADAS is already mainstream in many trims: lane centering, adaptive cruise control, automatic emergency braking, and parking aids are widely sold. Full self-driving sits on a different rung. It requires much higher confidence in edge cases, bad weather, roadwork, and unexpected human behavior.
The autonomous vehicle section ties the trend to road safety, and that is the key business argument. Self-driving cars may reduce human error, but only if the software stack, sensor suite, and operational design domain are controlled closely enough to satisfy regulators and insurers.
Safety performance, sensor stacks, and software dependency
Autonomy depends on cameras, radar, lidar in some systems, mapping, compute, and constant software refinement. Remove one layer, and reliability can drop fast. That makes the technology more like a managed operating system than a simple vehicle feature.
Weather, road markings, and construction zones remain hard problems. So do liability and update management. OEMs cannot treat autonomy as a one-time launch. Every software revision can change the risk profile.
Regulation, liability, and deployment timelines
Regulators will continue allowing partial automation faster than they will allow broad hands-off driving. That means the next decade likely belongs to supervised systems, commercial pilots, and limited robotaxi corridors rather than universal private ownership of fully autonomous cars.
How will smart cities affect future cars?
Smart cities will shape future cars through vehicle-to-infrastructure links, traffic management, and coordinated transit planning. Cars can communicate with city systems, but the near-term value is operational, not futuristic: fewer delays, better signal timing, cleaner fleet routing, and more predictable urban movement.
Vehicle-to-infrastructure connectivity and traffic signals
Smart city integration starts with traffic lights, road sensors, and connected intersections. Vehicle-to-infrastructure connectivity can improve signal timing, reduce idling, and help fleets avoid bottlenecks. Smart city infrastructure also supports congestion reduction and, in some cities, lower local air pollution from smoother traffic flow.
Real-time data exchange for traffic management
Real-time data exchange matters most where roads are dense and delays are costly. Municipal operators can use it to redirect traffic, prioritize emergency vehicles, and coordinate work zones. For OEMs, the commercial value comes from embedding connectivity that city systems can recognize.
Picture a downtown delivery van entering a corridor with synchronized signals and live curb-space data. If the data is accurate, the route saves minutes. If it is stale or fragmented across vendors, the van still idles at the curb.
Public transport coordination and urban mobility planning
The larger opportunity is not only smoother cars. It is blending cars with public transport so riders can switch modes without friction. That requires standard data formats, app integration, and city willingness to share operational data across agencies and private operators.
How shared mobility is changing car ownership
Shared mobility changes ownership by making access more flexible than possession. Car-sharing models, ride-hailing, and fleet-based access can raise utilization rates, but they work best where parking is expensive, trips are short, and customer behavior already favors convenience over private ownership.
Car-sharing models and fleet utilization
For fleets, shared mobility can push utilization higher than private cars ever reach. That helps operators spread depreciation across more trips. It also changes vehicle specification: interiors, cleaning cycles, durability, and telematics matter more than badge appeal.
Consumer behavior shifts from ownership to access
The shared mobility section notes a shift in consumer behavior, and that is the core point. Some urban customers prefer paying for use, not parking. Others still want ownership for control, long trips, or family needs. The market is segmented, not converted.
Environmental claims and where they do or do not hold up
Shared mobility can reduce fleet duplication if occupancy is high and deadheading is limited. It can also increase traffic if vehicles circle between trips or replace transit use. The environmental result depends on how the system is designed, not on the label alone.
What does servitization mean in the auto industry?
Servitization means shifting from ownership to usership. The page explicitly mentions subscription-based models, and that is a good shorthand: the vehicle becomes part of a broader service package, with software, maintenance, insurance, charging, or usage rights bundled into recurring revenue.
Subscription-based access and bundled mobility services
Subscriptions appeal because they lower commitment and let brands keep customers inside their ecosystem. Mobility-as-a-service bundles can include maintenance, connected features, and short-term access options. The upside is steadier revenue; the downside is customer backlash if pricing feels opaque or restrictive.
Connected features as recurring revenue
Connected features can create long-tail revenue after the vehicle sale. Remote diagnostics, over-the-air updates, seat heating, navigation, and security services all fit this model. But the offer has to be clear. Buyers will reject fees that look like paywalls for basic hardware.
Retention, pricing, and dealer implications
Dealers face a different role in a servitized market. They move from one-time transaction focus toward retention, renewal, and feature activation. That can help service absorption, but only if sales teams understand the package and pricing stays transparent.
What is mobility as a service in the automotive industry?
MaaS is a growing trend in the car industry that lets users plan, book, and pay for multiple transport modes in one place. It matters most in dense cities, where commuters may switch between car, rail, bike, and shuttle depending on time, cost, and congestion.
Multi-modal trip planning and app-based access
MaaS platforms work when they connect schedules, payments, and trip planning without forcing the user to juggle separate systems. The point is not to replace cars everywhere. It is to reduce friction between modes and make access more flexible than private ownership.
How MaaS fits urban commuters and transit networks
MaaS matters most for commuters who value predictability. If a train is late, the app should offer a backup ride. If the city bus is faster, the system should recommend it. That requires integration with transit networks, not just a branded ride-hailing app.
How will alternative power sources change the automotive market?
Alternative power sources will split the market rather than replace batteries outright. EVs will keep growing, hybrids will remain important during the transition, and hydrogen fuel cells will stay niche outside specific commercial use cases. The market is moving toward fit-for-purpose powertrains, not one universal answer.
Are hydrogen fuel cells really part of the future of cars?
Hydrogen fuel cells are part of the future for some vehicles, but not most passenger cars. They refuel faster than battery-electric vehicles, which helps in certain commercial and long-range duty cycles. Efficiency losses, infrastructure scarcity, and high system cost still limit broad passenger adoption.
Refueling versus charging
Hydrogen’s strongest argument is downtime. Refueling can be quick, which matters for buses, trucks, and other vehicles that cannot sit idle for long charging sessions. Battery-electric power remains more efficient from grid to wheel, though, and that efficiency matters for operating cost.
Where hydrogen makes sense for commercial and long-range use
Hydrogen makes the most sense in routes that are predictable, heavy-duty, or time-sensitive. Long-haul freight, select buses, and specialized fleets can justify it if infrastructure exists. Passenger cars rarely get the same economics because they lack scale and dense refueling access.
Infrastructure limits and efficiency trade-offs
The biggest limit is infrastructure. Hydrogen stations are expensive and sparse compared with charging. The second is energy loss across production, transport, and conversion. That trade-off keeps hydrogen behind batteries for most light-duty cars, even if it remains relevant in a narrower commercial lane.
A practical ranking by business impact in 2026
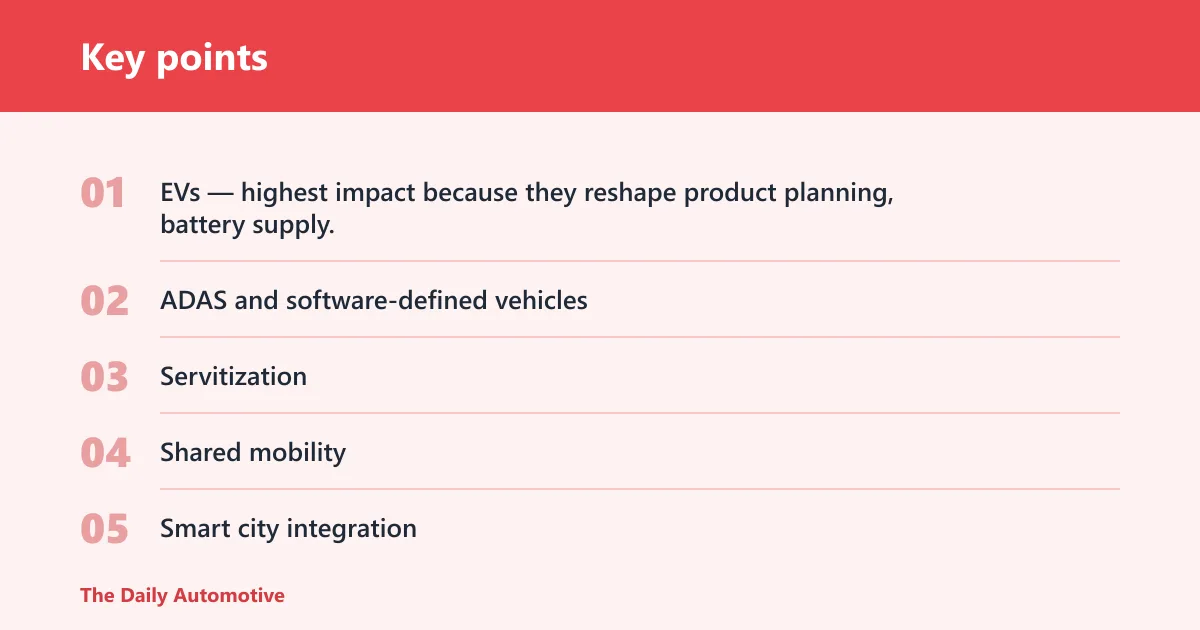
- EVs — highest impact because they reshape product planning, battery supply, charging partnerships, and dealer service.
- ADAS and software-defined vehicles — high impact because feature content and recurring software revenue are already changing margins.
- Servitization, high impact because subscriptions and connected services alter retention and pricing.
- Shared mobility, moderate impact, strongest in fleets and dense cities.
- Smart city integration, moderate but growing, especially for municipal and fleet channels.
- MaaS, localized impact, mainly urban commuter ecosystems.
- Hydrogen fuel cells, limited impact for passenger cars in the near term.
- Full self-driving, important long term, but still too constrained to rank as mainstream in 2026.
Readiness checklist for OEMs, suppliers, and dealers
- Map each trend to a revenue line, not a press release.
- Separate volume products from pilot programs.
- Stress-test regulation, liability, and service costs.
- Check regional charging, transit, and data infrastructure.
- Build software, fleet, and subscription support into the sales plan.
- Keep hydrogen and full autonomy in gated pilots unless the use case is narrow and funded.
Frequently asked questions
What are the biggest trends shaping the future of the car industry?
The biggest trends are EV adoption, ADAS, software-defined vehicles, connected services, shared mobility, servitization, smart city integration, MaaS, and selective hydrogen use. The near-term winners are the ones already affecting purchasing, service revenue, and fleet planning, not the ones still waiting on infrastructure or regulation.
How is electric vehicle adoption changing the auto industry?
EV adoption is changing battery sourcing, platform design, dealer service, and charging partnerships. It is also pushing OEMs to compete on software, charging speed, and total cost of ownership. Adoption is uneven by region, so product mix has to match local infrastructure and customer willingness to pay.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.