What Is a Car Payment? Definition and Payment Breakdown
A car payment is the monthly amount you pay on an auto loan. It usually includes principal and interest, and it can also include taxes, fees, or add-ons if those costs are financed. Misreading it can leave you short on monthly cash and paying far more over the loan term. This guide breaks down down payments, loan terms, ownership costs, and what happens if you miss a payment.
What is a car payment?
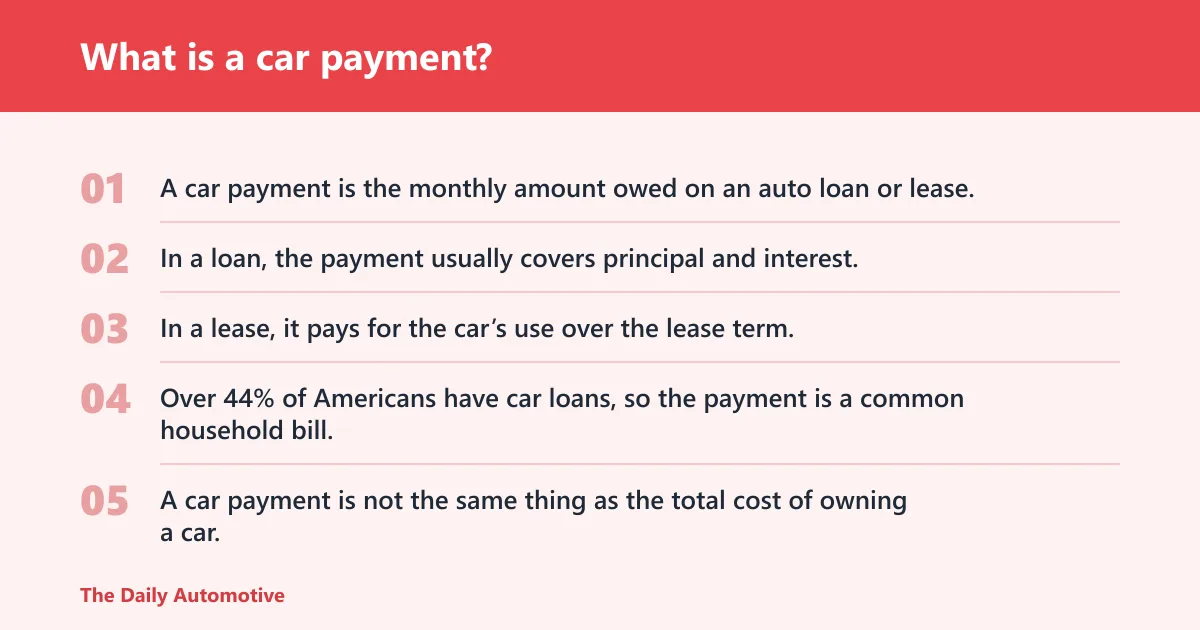
A car payment is the monthly amount owed on an auto loan or lease. In a loan, the payment usually covers principal and interest. In a lease, it pays for the car’s use over the lease term, plus any lease charges spelled out in the contract. Over 44% of Americans have car loans, so the payment is a common household bill.
A car payment is not the same thing as the total cost of owning a car. It is one debt obligation. Insurance, fuel, maintenance, parking, and registration renewals are separate costs unless your contract folds a specific fee into the loan balance.
What a monthly payment usually covers
Most auto loan payments include two parts: principal and interest. Principal reduces the amount you borrowed. Interest is the lender’s charge for lending the money, and it rises with a higher APR or a longer repayment term.
What a car payment does not cover
A standard loan payment usually does not include insurance, gasoline, oil changes, tires, parking, or routine maintenance. It also does not equal the out-the-door price, which is the total amount you owe at signing after price, taxes, title, registration, and fees.
📊 Some lenders report missed payments at the 30-days-late mark. Source: What Happens When You Miss a Car Payment?.
How does a car payment get calculated?
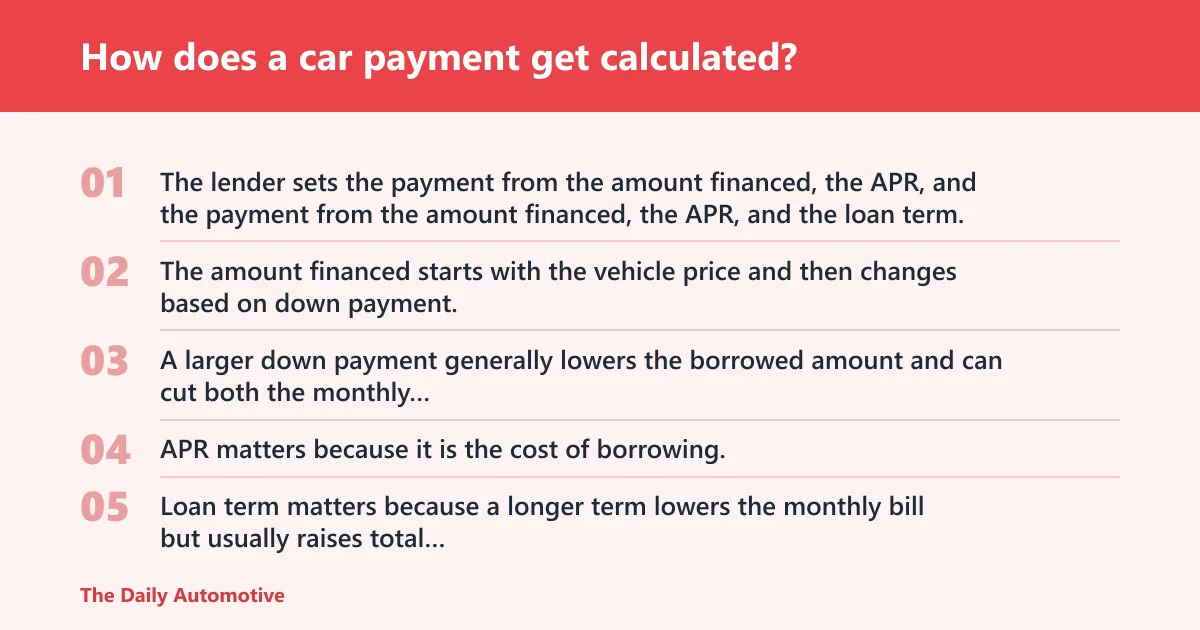
The lender sets the payment from the amount financed, the APR, and the loan term. The amount financed starts with the vehicle price and then changes based on down payment, trade-in equity, taxes, title, registration, and any fees or add-ons you roll into the loan. A larger down payment generally lowers the borrowed amount and can cut both the monthly payment and total interest.
APR matters because it is the cost of borrowing. Loan term matters because a longer term lowers the monthly bill but usually raises total interest paid over time. That tradeoff explains why two shoppers can buy the same car and still end up with very different payments.
Amount financed after down payment and trade-in
Start with the purchase price. Subtract cash down and any trade-in equity. Then add financed taxes and fees if the contract rolls them in. Trade-in equity is not the same as a down payment; it is an offset created by the value of your current vehicle after any payoff to the lienholder.
Taxes, title, and registration
Sales tax, title, and registration may be paid at signing or folded into the loan, depending on the contract and state rules. That choice changes the amount financed and the monthly payment. It also changes the amount due at closing, which is why the sticker price and the out-the-door price are not interchangeable.
What is included in a monthly car payment?
In a loan context, a monthly car payment is usually principal and interest. Some contracts also include financed fees, gap coverage, service contracts, or other add-ons if you agreed to roll them into the loan. Those items change the amount financed before the lender calculates the payment.
Principal and interest
Principal reduces the balance you owe. Interest is the lender’s charge for access to the money. Early in the loan, a larger share of each payment often goes to interest; later, more goes to principal. That pattern is normal amortization.
Fees that may be rolled into the loan
Taxes, title, registration, documentation charges, and optional products can be financed in some deals. That makes the monthly number look manageable at signing, but it also means you pay interest on those added amounts too.
Costs that are usually separate
Insurance, fuel, repairs, parking, and routine maintenance are usually separate from the car payment. If you budget only for the loan bill, the vehicle can still strain cash flow because ownership costs arrive every month.
How do car down payments work?
A down payment is upfront cash paid at purchase. It reduces the amount financed, which often lowers the monthly payment and the total interest cost. If you also have trade-in equity, that value can work like additional upfront money because it offsets the amount you need to borrow.
Suppose a buyer puts $4,000 down on a $30,000 car. The payment falls because the lender is financing less principal. The exact change depends on APR, loan term, and whether taxes and fees are rolled in.
Cash down vs. trade-in equity
Cash down is money you bring to the deal. Trade-in equity is the value of your current car after any remaining loan is paid off. Both reduce the amount financed, but they are not the same thing on the contract.
How much a down payment can change the payment
With the same vehicle price, APR, and loan term, a larger down payment generally means a smaller monthly bill. It can also reduce the risk of owing more than the car is worth early in the loan. That matters if you sell or trade it before the balance falls much.
How do down payments work on cars?
Down payments work by shrinking the loan balance before interest is calculated. The bigger the down payment, the less you finance. That can lower the payment and reduce the total interest over the term, but the right amount still depends on your cash reserves and the rest of the deal.
A common mistake is assuming the monthly car payment covers insurance, gas, and maintenance in one bill. It is not. It is prepaid equity in the deal, and it should be weighed against savings you need for insurance, registration, repairs, and an emergency fund.
How does a down payment change a car loan payment?
A down payment changes a car loan payment by cutting the amount financed, which lowers the lender’s principal balance. With the same APR and term, less principal usually means a smaller monthly payment and less interest paid over time. The effect is strongest when the down payment is large relative to the car price.
Sample payment breakdown for a $30,000 car
Assume a roughly 60-month loan at around 8.0% APR, with about $2,000 in taxes, title, and registration rolled into the loan. The figures below are estimates, not quotes, but they show how the same car price changes under different down-payment scenarios.
| Down payment | Amount financed | Estimated total interest over 60 months | Taxes/fees rolled in | Estimated monthly payment | Monthly payment change vs. no down payment |
|---|---|---|---|---|---|
| $0 | $32,000 | $7,036 | $2,000 | $651 | Baseline |
| $3,000 | $29,000 | $6,376 | $2,000 | $590 | About $61 less |
| $6,000 | $26,000 | $5,716 | $2,000 | $529 | About $122 less |
What the table shows
The car price stays the same in all three cases. What changes is the amount borrowed. More cash down cuts the principal, trims the interest burden, and lowers the monthly bill. If you shortened the term, the payment would rise even if the down payment stayed the same.
What monthly costs are not part of the car payment?
Insurance is not part of the loan payment unless your lender requires a separate product you agreed to finance. Fuel, maintenance, repairs, parking, tolls, and registration renewals are also outside the car payment. These are ownership costs, not debt-service costs.
Why that distinction matters
Buyers often ask whether they can “afford the car” by looking only at the monthly loan payment. That misses the rest of the bill. A lower payment can still leave you stretched if insurance is expensive or the car needs tires, brakes, or scheduled service soon after purchase.
What happens if you miss a car payment?
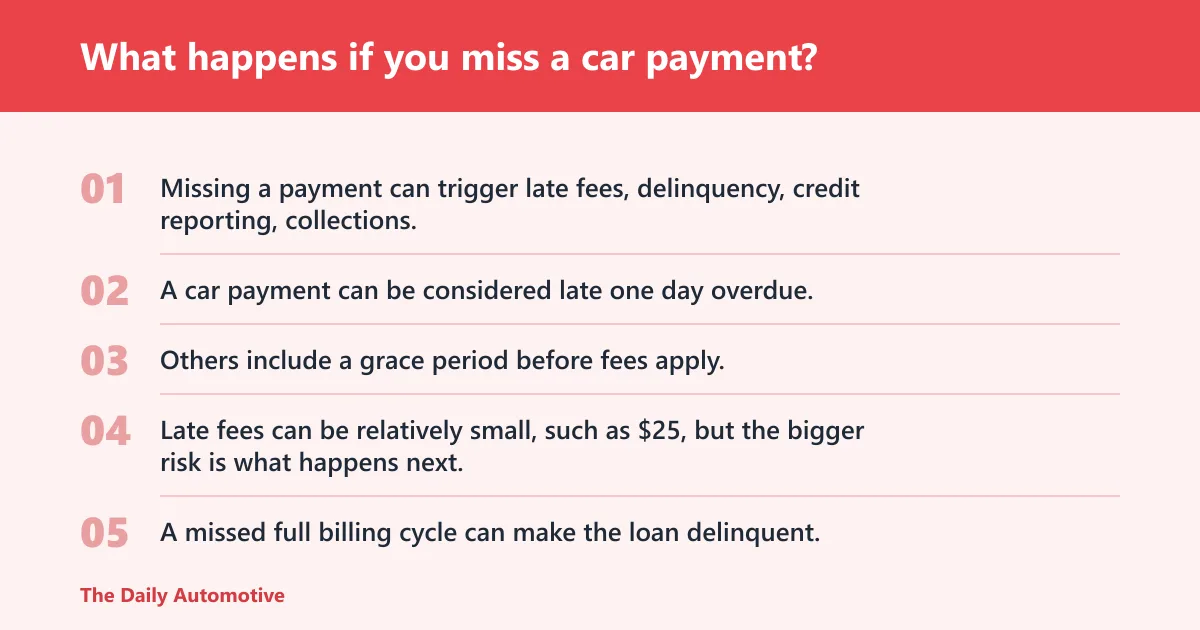
Missing a payment can trigger late fees, delinquency, credit reporting, collections, and eventually repossession, depending on the lender and how long the account stays unpaid. A car payment can be considered late one day overdue, and some loan terms treat it as late on the exact due date. Others include a grace period before fees apply.
Late fees can be relatively small, such as $25, but the bigger risk is what happens next. A missed full billing cycle can make the loan delinquent, and some lenders report missed payments at the 30-days-late mark. A delinquent loan hit can stay on a credit report for seven years.
Late fees and grace periods
Do not assume every lender gives the same grace period. Some lenders may contact borrowers after a missed payment, while others act faster. Read the contract for the due date, the late-fee trigger, and whether electronic payments count on the date you submit them or the date they settle. EFT is the catch-all term for electronic payments, and ACH is one type of EFT.
Delinquency and repossession
If the account stays unpaid, collections can follow. Collections can lead to repossession and damaged credit. Repossession rules vary by contract and state law, but the path usually starts with repeated missed payments and a lender’s effort to recover the vehicle or the balance due.
How do I estimate a car payment before I buy?
Estimate the payment by starting with the car price, then subtracting down payment and trade-in equity, adding taxes and fees, and applying the APR and loan term. That gives you a rough monthly number before you sign. The estimate will be close only if the final contract matches those assumptions.
- Set the vehicle price and ask for the out-the-door figure.
- Subtract cash down and any trade-in equity.
- Add taxes, title, registration, and any financed extras.
- Confirm the APR and the loan term in months.
- Check the estimated payment against your full monthly budget.
What to read in the retail installment contract
Look for the amount financed, APR, total of payments, finance charge, payment due date, late-fee rule, grace period, and whether any add-ons are included. Check whether taxes and fees are financed or paid upfront. If any line looks unclear, ask for the exact dollar impact before signing.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.