Who Will Finance a Rebuilt Title Car? What Lenders Say (2026)
Who will finance a rebuilt title car? There is no single list. Some lenders refuse any branded title, while others, such as Communication Federal Credit Union in Oklahoma and Kansas, publish rules for rebuilt and salvage vehicles. Capital One’s auto loan page excludes branded titles. This guide checks what lenders, state DMVs, NMVTIS, the CFPB and the FTC actually say, with the date each page was read (October 14, 2026), so you can ask the right questions before you buy.
Who Finances Salvage Title Vehicles? The Short List
The honest short list is short because lenders set their own collateral rules and few publish them. The table below only includes policies that appear on the lender’s own page or an official consumer page, and it says plainly when a page is silent. It is not a list of lenders that will approve you.
Inspection Tool Pick: Paint Thickness Gauge
|
Digital Paint Thickness Gauge for Cars, Backlit LCD, Mils and Micron Units Lenders and insurers care about what a rebuilt car went through. A coating gauge is a cheap way to spot panels that were repainted or filled before you pay for a full inspection.
|
As an Amazon Associate we earn from qualifying purchases. Spec-based pick from the listing, not a hands-on test. No lender requires this tool; it is an optional buyer aid.
| Lender or source type | What the page says about rebuilt or salvage titles | Page date or as-of | Source |
|---|---|---|---|
| Large bank, purchase loan (Capital One) | Its auto financing FAQ says it does not offer financing for branded title vehicles (also lemon buybacks, commercial vehicles and others). The page does not name rebuilt or salvage titles separately; a Texas rebuilt title carries a “Rebuilt Salvage” brand, so confirm with the lender first. | Page undated; read Oct 14, 2026 | Capital One auto financing FAQ |
| Large bank, refinance (Capital One) | Its refinance FAQ lists salvage title vehicles and branded title vehicles among those it does not refinance. | Page undated; read Oct 14, 2026 | Capital One auto refinance FAQ |
| Credit union (Communication FCU, Oklahoma and Kansas) | Says it can finance rebuilt or salvage title vehicles: up to 50% of the NADA clean retail value, the vehicle must be operable, no junked titles, and full coverage insurance (collision and comprehensive) is required. | Page published Aug 29, 2025; modified Jul 20, 2026 (per the page) | Communication FCU auto loans page |
| Credit union add-on (America First CU) | Its GAP coverage page says it cannot provide GAP for classic or rebuilt/restored vehicles or those with salvaged titles. That is an add-on product, not a loan decision. | Page undated; read Oct 14, 2026 | America First CU GAP page |
| Dealer-arranged financing | The CFPB says the dealer sends your information to lenders and may add a markup. The page does not address title brands, so ask which lenders will take the car before you sign. | CFPB page reviewed Nov 8, 2022 | CFPB, dealer-arranged vs bank financing |
| Buy here, pay here dealers | The CFPB says they finance borrowers with no or poor credit and rates tend to be higher than from a bank or credit union. It says nothing about rebuilt titles. | CFPB page reviewed Jan 30, 2024 | CFPB, buy here pay here |
| Auto title loan lenders | Not a way to buy a car. The CFPB describes these as high-cost small-dollar loans secured by the title of a vehicle you already own. | CFPB post published May 18, 2016; modified Jun 25, 2026 | CFPB blog on auto title loans |
Notice the pattern: only a lender’s own page can tell you its policy, and many pages simply do not mention title brands. That silence is not approval. The only way to find out is to ask a lender, before you buy, whether it will lend on a branded title and what it needs to see.
Salvage vs Rebuilt: What the State Pages Say
Lenders read the brand on the title, so the words matter. They are not the same in every state, which is a common source of confusion for shoppers comparing cars across state lines.
- Texas: the TxDMV rebuilt vehicles page says a rebuilt vehicle, also known as prior salvage, was branded salvage but rebuilt to road worthiness, and the title will carry the Rebuilt Salvage brand. TxDMV’s salvage page defines a salvage vehicle as one damaged so that the repair cost, materials and labor, was more than the vehicle was worth before the damage, usually decided by an insurance company, and says it must be rebuilt and inspected before it can be driven on a road again.
- California: the California DMV branded titles page describes the Salvaged brand as a vehicle involved in an accident or one that took considerable damage from another source, and lists Rebuilt among other brands without defining it. California is one example; do not assume another state uses the same labels.
- Other states: not covered here. Check your state DMV’s own page, because brand names, thresholds and inspection steps differ.
The federal NMVTIS system adds one more layer. Its NMVTIS consumer page defines a brand as a descriptive label that states assign to identify a vehicle’s current or prior condition, and it warns that brand standards vary by state, so a vehicle treated as salvage in one place may not carry that brand in another.
Why a clean history report is not proof
The same NMVTIS page says not all states and entities report, so a search may give a false negative, such as showing no junk or salvage history. The FTC adds that a vehicle history report is not a substitute for an independent vehicle inspection. Treat the report as one check among several, not a final answer. Ask the seller to show the physical title and compare its brand with what the report shows.
What Lenders Require Before Approving a Rebuilt Title Loan
There is no national checklist. The clearest published example in this research is Communication Federal Credit Union, which serves Oklahoma and Kansas. Its page says it can finance rebuilt or salvage title vehicles with limits: financing up to 50% of the NADA clean retail value, an operable vehicle, no junked title and full coverage insurance. That is one credit union’s rule, not an industry norm.
What does show up across official pages is the insurance link. The Insurance Information Institute says auto dealers or lenders will likely require you to buy collision and comprehensive coverage when you finance. If your insurer will not write that coverage on the car, a lender that requires it has nothing to work with.
Insurance: The Step Buyers Often Skip
TxDMV’s rebuilt vehicles page says, in its words, that often rebuilt vehicles are denied insurance, and it tells buyers to check with their insurance agent before purchasing. That sentence is from a Texas state agency, not a national statistic, but the order of operations is the lesson: confirm coverage before you commit to a loan, not after.
- Ask the insurer which coverage it will write. Liability alone usually will not satisfy a lender that requires collision and comprehensive.
- Ask what documents it needs. Some insurers may want inspection details; the pages read do not say which, so ask.
- Ask about gap coverage separately. America First Credit Union’s page says it cannot provide GAP for rebuilt or restored vehicles or those with salvaged titles, so do not assume a lender’s add-ons are available on a branded car.
Alternative Ways to Buy a Rebuilt Title Car Without a Traditional Loan
Only the options the CFPB describes are covered here. The CFPB says getting a loan directly from a bank or credit union tends to be the cheaper route because you avoid the dealer’s markup, and that a preapproval gives you a quote with a rate, term and maximum amount based on your credit and the type of vehicle you have in mind. Tell the lender the car has a branded title when you ask for a quote, because that detail can change the answer.
- Bank or credit union direct loan. Ask about branded titles up front. Our guide on the mark-up on a new car explains how dealer pricing works on the sale side.
- Dealer-arranged financing. The CFPB says dealers may charge more than the rate a lender offered them. Ask which lenders the dealer will submit a branded-title car to.
- Buy here, pay here. The CFPB says rates tend to be higher than at banks and credit unions, and that these dealers often only report negative payment information to credit bureaus. If you use one, ask for written confirmation that on-time payments are reported.
- Paying cash. Avoids a lender’s title-brand policy entirely, but not the insurance question.
- Personal loans. None of the official pages read for this guide cover personal loans for branded-title cars, so compare any offer using the lender’s own loan disclosures.
Do not confuse a car loan with a title loan
Search results for this topic mix two different products. A loan to buy the car is secured by the car you are buying. An auto title loan, which the CFPB describes as a high-cost small-dollar loan, is secured by the title of a vehicle you already own. The CFPB’s 2016 research found that one in five single-payment auto title loan borrowers had their vehicle seized.
Checklist: What to Do Before You Buy a Rebuilt Title Car
- Pull the history. Order a vehicle history report that uses NMVTIS data, then compare it with the seller’s physical title and its brand wording.
- Confirm the car is road legal. TxDMV says a salvage vehicle must be rebuilt and inspected before it can be driven on a road again. Check your own state’s page for the equivalent step.
- Pay for an independent inspection. The FTC says a history report is no substitute, and TxDMV advises having an expert mechanic thoroughly inspect the vehicle. A paint gauge helps, but a mechanic should look at structure, brakes and safety systems.
- Call your insurer first. Ask whether it will write collision and comprehensive on this specific vehicle, and what documents it wants.
- Ask lenders in writing. Ask if they finance branded titles, what their loan limits are, whether the car must be operable and insured, and what documents they need.
- Get preapproved before you negotiate. The CFPB says a preapproval can strengthen your hand with the dealer. Our guide on whether dealerships accept credit cards may help you plan a down payment.
- Know your exit. Check the seller’s terms in writing. Our guide on returning a car to a dealership explains why you should not assume you can undo the sale.
When to walk away: if the seller will not allow an independent inspection, will not show the title, or cannot show the vehicle passed your state’s rebuilt inspection where one is required. Do not drive a car with warning signs on the brakes, steering or airbags until a qualified mechanic has checked it.
Is Financing a Rebuilt Title Car Worth It?
A lower purchase price is the usual draw, but no official page read for this guide gives a standard discount, so verify the car’s value with comparable listings. Then add the extra work the pages describe: a narrower lender pool, an insurance check and a paid inspection. Rebuilt cars also carry their brand into every future sale.
Frequently Asked Questions
Who finances rebuilt title cars?
No official page lists lenders that always will. Some credit unions publish their own rules for rebuilt and salvage vehicles, for example Communication Federal Credit Union in Oklahoma and Kansas, while Capital One’s auto financing page excludes branded titles. Ask each lender directly.
Will Capital One finance a rebuilt title car?
Its auto financing FAQ says it does not offer financing for branded title vehicles, and its refinance FAQ lists salvage and branded title vehicles among those it does not refinance. Neither page names rebuilt titles separately, so confirm with Capital One for a specific car.
What credit unions finance rebuilt title cars?
Policies vary by credit union and membership area. Communication Federal Credit Union, serving Oklahoma and Kansas, says it can finance rebuilt or salvage title vehicles up to 50% of NADA clean retail value if the vehicle is operable and fully insured. Check your local credit union’s own page or call before applying.
Can I get a title loan on a rebuilt title car?
A title loan is a different product from a car loan. The CFPB describes auto title loans as high-cost small-dollar loans secured by the title of a vehicle you own. Whether a title lender accepts a branded title is that lender’s policy; the CFPB pages read do not say.
Can I get full coverage insurance on a rebuilt title car?
Not always. TxDMV says rebuilt vehicles are often denied insurance and tells buyers to check with their insurance agent before purchase. The Insurance Information Institute says lenders will likely require collision and comprehensive, so ask your insurer before applying for a loan.
How do I check if a car has a salvage or rebuilt title?
Start with the physical title and an NMVTIS-based history report. The NMVTIS consumer page says brands are state-assigned and that a search can show a false negative. The FTC adds that the National Insurance Crime Bureau’s VIN lookup can show if a vehicle was flood damaged, stolen but unrecovered or declared salvage,
Conclusion
Financing a rebuilt title car is possible with some lenders, but it takes more checking than a standard auto loan. Ask lenders about branded titles in writing, confirm insurance before you borrow, get an independent inspection, and use the title, not marketing claims, as your guide. This guide is general information, not financial, insurance or legal advice; policies and state rules change, so confirm every point with the lender, insurer and your state DMV before acting.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
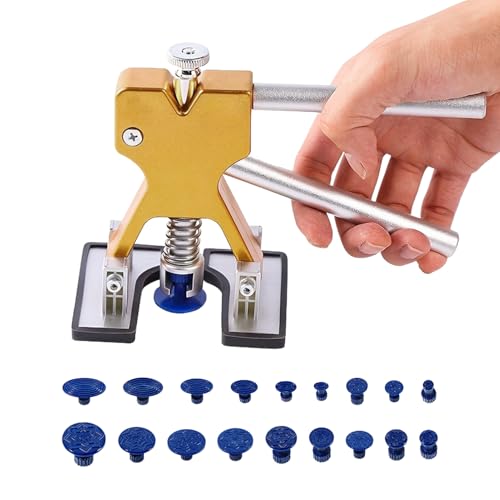 Auto Body Repair Kit Car Dent Puller with 18pcs Pull Tabs, Universal T Bar Paintless Dent Remover Tool Lifter for Auto Hail Damage Repair & Other Metal Surface
 Car A/C Repair Kit, 270PCS Rubber O-Ring Seal Kit + 40PCS Car Air Conditioner Valve Core Kit for R12 R134a A/C with Remover & Install Tool+10pcs R134a AC Valve Caps, Fix Refrigeration System