Best Auto Insurance for Low-Mileage Drivers: Cheap Picks
For many low-mileage drivers, pay-per-mile may be cheapest below about 7,000 miles a year; between roughly 7,000 and 12,000 miles, usage-based insurance can often be a better fit; above that, a traditional policy with a low-mileage discount may cost less. Choose wrong, and you can pay hundreds more each year for a policy built on miles you never drove. This guide breaks down the cutoff points, the tradeoffs, and how to choose the cheapest fit for your mileage and driving habits.
Best auto insurance for low-mileage drivers: the top pick by mileage
The best auto insurance for low-mileage drivers depends on annual miles, not just on driving less than average. The plain rule is this: very low mileage usually favors pay-per-mile, moderate low mileage often favors usage-based insurance, and higher-but-still-below-average mileage often favors a standard policy with a low-mileage discount.
Top pick for very low annual miles: pay-per-mile insurance
Pay-per-mile car insurance uses a monthly base premium plus a charge for each mile driven. That setup usually fits drivers who log very few miles, and the bill can move up or down from one month to the next with mileage. NerdWallet says it fits people who do not drive often, and those policies can include the same coverage options as standard policies.
Top pick for careful drivers with moderate miles: usage-based insurance
Usage-based insurance, or UBI, uses telematics to track driving habits through an app or a plug-in device. It may record mileage, speed, handling, and when you drive. For someone who drives moderately but stays steady behind the wheel, UBI often beats a pure mileage plan because the discount can reflect both low use and low risk.
Top pick if your insurer offers it: a traditional policy with a low-mileage discount
A low-mileage discount is often available at around 10,000 miles per year or less. It is not the same as pay-per-mile pricing. If the carrier offers a solid discount and the driver does not want mileage tracking, this is often the simplest low-friction option.
According to The Best Car Insurance Companies for Low-Mileage Drivers — American Family is listed with a low-mileage discount up to 25%.
Quick picks by driving pattern
These quick picks are a decision rule, not a promise. Location, vehicle type, and driving record can still swing the final price. Mileage is one factor, and sometimes it matters less than the rest.
- Drive under 5,000 miles a year: pay-per-mile is usually the first quote to request.
- Drive about 5,000 to 8,000 miles a year: compare pay-per-mile against UBI; either can win.
- Drive 8,000 to 10,000 miles a year: a low-mileage discount or UBI often beats pay-per-mile.
- Drive more than 10,000 miles but still below average: a standard policy with a low-mileage discount is often the cheapest path.
What counts as low mileage for car insurance?
Low mileage for car insurance is usually defined against annual use thresholds, and those thresholds vary by program. Some insurers classify fewer than 7,000 miles yearly as low-mileage, while others use 7,500, 8,000, or 10,000 miles per year. The national average annual vehicle mileage is 13,476 miles, so even 10,000 miles can still count as relatively low use.
How insurers use annual mileage thresholds
One carrier may treat 7,000 miles as the cutoff for a low-mileage plan, while another uses 7,500 or 10,000. That difference matters. A driver at 7,200 miles could qualify with one company and miss the discount entirely with another.
Why 13,476 miles per year is the comparison point
That figure gives context. If a driver is far below 13,476 miles a year, they may be a better fit for mileage-based pricing. If they are only slightly below it, the discount may not be large enough to beat a plain policy.
Why your cutoff may be 7,000, 7,500, 8,000, or 10,000 miles
Different insurers price risk differently. Farm Bureau is listed with a 7,500-mile annual cutoff, State Farm is listed with a 7,500-mile annual cutoff, Mile Auto is listed with a 10,000-mile annual cutoff, and some insurers classify fewer than 7,000 miles yearly as low-mileage. The cutoff that matters is the one your carrier actually uses.
Pay-per-mile insurance: when it usually wins
Pay-per-mile usually wins when a driver logs very few miles, keeps trips short, and can live with a bill that changes from month to month. It is a clean fit for people who only drive to errands, school runs, or the occasional weekend trip. It starts to lose steam once annual mileage climbs.
How the monthly base rate and per-mile charge work
Pay-per-mile insurance uses a monthly base premium plus a cost per mile. That means the bill rises when driving rises, and drops when the car sits. The coverage can still look like a standard auto policy, which is why the setup is often appealing for very infrequent drivers.
Who should consider it
Drivers with one car that stays parked most weekdays often get the best value. So do retirees, remote workers, and households with a second vehicle used only sparingly. Nationwide is listed as offering pay-per-mile insurance with no cutoff, which makes it a useful comparison point for drivers who expect mileage to stay low.
What can make it more expensive than expected
Long road trips, a surprise commute, or a seasonal job can wipe out the price edge quickly. A driver who starts at 4,000 miles and ends up near 9,000 may find a pay-per-mile plan less competitive than a discount-based policy. Monthly volatility matters here.
Usage-based insurance: when telematics is the better fit
Usage-based insurance is often the better bet for careful drivers whose mileage is moderate rather than tiny. The program may reward safe driving behavior even when the car is used enough that pay-per-mile starts to look expensive. It also fits drivers who want savings without having to stay under a hard mileage cap.
What an app or plug-in device tracks
UBI uses telematics to monitor mileage, speed, handling, and when you drive. The tracking may happen through a mobile app or a plug-in device. That matters because the score is not only about distance. A driver can put on decent miles and still save if the pattern looks low-risk.
When UBI beats pay-per-mile
UBI often wins when annual mileage is midrange but the driver is smooth, predictable, and not driving at risky times. A commuter who logs 8,500 or 9,500 miles with clean habits may do better than they would on a pay-per-mile plan, because the telematics score can offset the mileage.
Why some low-mileage drivers still save without a mileage-specific plan
Low mileage helps, but it is not the whole pricing picture. Good driving history, a safer vehicle, and a lower-risk location can matter just as much. That is why some low-mileage drivers save more with UBI than with a strict mileage discount, especially if the carrier’s low-mileage program is weak.
Low-mileage discount on a standard policy: when it is enough
A standard policy with a low-mileage discount is often enough when a driver is below the carrier’s mileage cutoff but does not want telematics or per-mile billing. This is the simplest path for people who want a steady premium and do not want billing tied to an app or an odometer routine.
How percentage discounts differ from per-mile pricing
A low-mileage discount is a percentage off a traditional premium. Allstate is listed with an estimated discount of 50%, American Family is listed with a low-mileage discount up to 25%, and Mile Auto is listed with 30% to 40% estimated savings. That is not the same as paying per mile.
What verification insurers may ask for
Verification may come through odometer photos, self-reported mileage, or enrollment in a monitoring program. Some insurers ask for a photo at signup or renewal. Others use app data or a plug-in device. If the insurer wants proof, that step can decide whether the discount is available at all.
When keeping a standard policy is cheaper and simpler
If the driver is only a little below the carrier’s cutoff, the discount may be too small to matter. In that case, a regular policy without mileage tracking may be the cleaner choice. It is also the better fit for households where one car is low-mileage but another is not.
Which companies offer pay-per-mile car insurance
The names that often appear on ranking pages include Allstate, Mile Auto, Nationwide, Lemonade, American Family, Farm Bureau, State Farm, and GEICO. Those companies do not all use the same pricing model. Some are known for pay-per-mile, some for low-mileage discounts, and some for UBI or broader telematics programs.
How to read carrier names without mixing up the pricing model
Do not assume a low-mileage-friendly carrier is automatically offering pay-per-mile. Allstate, Mile Auto, Nationwide, Lemonade, American Family, Farm Bureau, State Farm, and GEICO are names that show up in this space, but the actual offer can be a discount, telematics, or pay-per-mile. The pricing model is what matters.
How to choose between pay-per-mile, UBI, and a low-mileage discount
Choose by annual miles first, then by driving pattern, then by verification burden. If the mileage is tiny, pay-per-mile is often the cleanest route. If the mileage is moderate and the driver is careful, UBI often wins. If the mileage is low but the driver wants simple billing, a standard policy with a low-mileage discount is often enough.
| Annual miles | Driving pattern | Verification method | Most likely best format |
|---|---|---|---|
| Under 5,000 | Rare use, short trips, parked most days | Odometer photo or app enrollment | Pay-per-mile |
| 5,000 to 8,000 | Low use, but some weekly driving | App or plug-in device | UBI or pay-per-mile, compare both |
| 8,000 to 10,000 | Occasional commuting, seasonal use, mixed trips | Odometer photo or self-reported mileage | Low-mileage discount or UBI |
| Above 10,000 but below average | Regular driving, fewer miles than most drivers | Self-reported mileage or renewal check | Standard policy with low-mileage discount |
Checklist: choose pay-per-mile, UBI, or a standard low-mileage discount
- Estimate annual miles as honestly as possible.
- Check the carrier cutoff: 7,000, 7,500, 8,000, or 10,000 can all appear.
- Decide whether monthly price swings are acceptable.
- Ask whether the insurer wants odometer photos, self-reported mileage, or app tracking.
- Compare pay-per-mile against UBI if annual miles are between 5,000 and 10,000.
- Use a standard low-mileage discount if the savings are real and the billing is simpler.
How mileage affects car insurance premiums
Lower mileage can reduce insurance costs because fewer miles usually mean less exposure to crashes. That is the basic logic behind low-mileage pricing. But mileage is only one factor among many. A bad driving record, an expensive vehicle, or a risky ZIP code can blunt the savings fast.
Why low mileage does not always mean a big discount
If a carrier already prices the policy heavily on location or driving history, low mileage may not move the number much. That is one reason a driver can have limited savings even when the odometer is low. The mileage program may be real, but the overall premium still depends on more than one variable.
Edge cases that change the math
Occasional road trips can push a pay-per-mile policy out of its sweet spot. Seasonal commuting can do the same. In multi-car households, one vehicle may deserve pay-per-mile while the other fits a regular low-mileage discount better. The right answer can differ inside the same driveway.
can low-mileage drivers save with usage-based insurance
Yes. Low-mileage drivers can save with usage-based insurance when the telematics score stays favorable, even if the car is not driven enough to justify a strict mileage-only plan. UBI can help drivers who are careful, predictable, and willing to let an app or plug-in device track behavior.
When UBI beats a mileage-only plan
UBI can beat pay-per-mile when the driver’s habits are good enough to earn a meaningful score-based discount. That is especially true once mileage moves out of the very-low range and into the middle bands, where a pure per-mile charge starts to lose its edge.
Frequently asked questions
does low mileage reduce insurance
Yes, low mileage can reduce insurance because fewer miles usually mean less exposure to loss. That said, the savings are not automatic. Driving record, location, vehicle type, and the carrier’s own pricing rules can matter just as much, and sometimes more, than the odometer reading.
what is low mileage for car insurance
Low mileage for car insurance usually means the driver is below a carrier’s annual cutoff. Some insurers use fewer than 7,000 miles yearly, while others use 7,500, 8,000, or 10,000. The national average annual vehicle mileage is 13,476 miles, so low mileage is often well below that.
best auto insurance for low mileage drivers
The best auto insurance for low mileage drivers depends on how low the mileage really is. Below about 7,000 miles, pay-per-mile often wins. Between about 7,000 and 12,000 miles, UBI may be cheaper. Above that, a standard policy with a low-mileage discount is often the better fit.
cheap car insurance for low mileage drivers
Cheap car insurance for low mileage drivers is usually the option that matches the driving pattern most closely. Very low-mileage drivers should compare pay-per-mile quotes first. Drivers with moderate mileage and safe habits should compare UBI. Drivers above common cutoffs should ask for a traditional low-mileage discount.
what companies offer pay-per-mile car insurance
Names that often appear on ranking pages include Allstate, Mile Auto, Nationwide, Lemonade, American Family, Farm Bureau, State Farm, and GEICO. Not all of those are pay-per-mile carriers in every market, so the actual offer needs to be checked. The pricing model matters more than the logo.
how does pay-per-mile insurance work
Pay-per-mile insurance works by charging a monthly base premium plus a per-mile fee. The bill changes from month to month with mileage, which makes it useful for infrequent drivers. It can include the same coverage options as a standard policy, but the final cost depends heavily on how much the car is driven.
what qualifies as low mileage for auto insurance
What qualifies as low mileage for auto insurance depends on the insurer. Common cutoffs include below 7,000 miles per year, 7,500 miles, 8,000 miles, or 10,000 miles. Some programs require odometer photos, while others use self-reported mileage or a monitoring program to verify use.
can low-mileage drivers save with usage-based insurance
Yes, low-mileage drivers can save with usage-based insurance, especially if the driver also behaves carefully. UBI can track mileage, speed, handling, and when you drive through an app or plug-in device. For moderate miles, that mix of low use and safer habits can beat a strict mileage-only plan.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
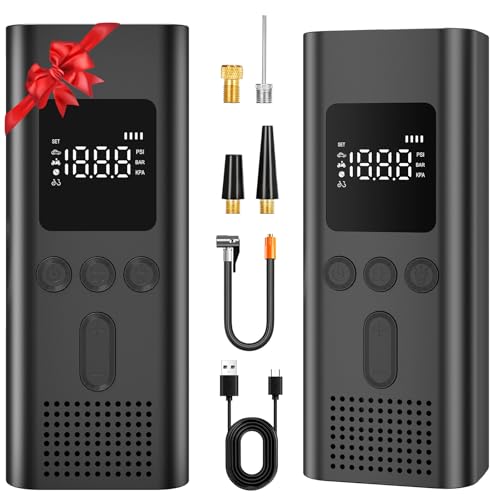 AIRSURE Tire Inflator Portable Air Compressor with Auto Shut-Off,Pack of 2
 Scosche Wireless Car Charger, Auto Clamping Car Vent Phone Mount, Cell Phone Holder Charger with Twist-to-Secure Hook, 360° Rotation, Compatible with iPhone, Samsung, Qi-Enabled Android Phones
 ONHUMILLION 3-Piece AC Charging Hose Set 60" Shut-off Valve for HVAC R134A