Car Insurance Coverage Guide
Choose liability insurance limits high enough to help protect your net worth, often around 100/300/100 or higher as a common shopping benchmark, and add collision coverage and comprehensive coverage when replacing or repairing the car out of pocket would be difficult. Get this wrong and one crash can leave you paying medical bills, a loan balance, or lawsuit damages out of pocket. This Car insurance coverage guide explains what each coverage does, how much is enough, and when to add, keep, or drop it as your car, loan, household risk, and assets change. (For the legal floor and split-limit format, see the NAIC Auto Insurance Guide and the Insurance Information Institute’s overview of auto liability limits.)
The practical way I buy coverage is to start with the losses that can blow up a household budget.
Then match those exposures to four things: the car’s value, whether there is a loan or lease, how much cash is available for a deductible, and how much income or property could be exposed in a lawsuit. A low-value paid-off car and a financed late-model SUV should not carry the same policy.
A quick self-audit helps. Ask which would hurt more: being sued after injuring someone, writing a check for another driver’s expensive vehicle, or replacing your own car next week if it were stolen or totaled.
What car insurance coverage do I actually need?
At minimum, a driver needs whatever state law requires, but that is only the legal floor. Financially sensible coverage usually means liability limits above the minimum, plus collision and comprehensive when losing the car would create a cash problem, and medical or uninsured-driver coverage where gaps would otherwise stay uncovered.
Start with the legal floor, then build to a usable policy
Most states require bodily injury and property damage liability auto insurance. In practice, state rules differ a lot, sometimes by just a little, sometimes by a lot. Some states also require medical or uninsured-driver protection. New York requires liability, PIP, and UI/UIM coverages. Florida only mandates property damage liability and PIP. (Those examples come from the New York DMV insurance requirements page and Florida Highway Safety and Motor Vehicles insurance requirements materials.)
That variation matters because a policy that is legal in one state may leave obvious holes in another. State minimum requirements may include liability, PIP, MedPay, or UI/UIM, but minimums usually tell you what keeps the registration legal, not what keeps a household from eating a large loss after a bad crash. The NAIC makes the same point in its consumer guide: minimums are a compliance baseline, not a recommendation for everyone.
When liability-only is enough
Liability-only can make sense when the car is paid off, worth little, and can be replaced from savings without disrupting rent, mortgage, or other essentials. Even then, liability-only should still include serious thought about UI/UIM, because careful driving does nothing when the other driver has no insurance or too little of it.
When liability-only is a bad bet
It becomes a bad bet when the car is financed, leased, hard to replace, or used daily for work, school, or family logistics. Liability-only also leaves a dangerous gap after a hit-and-run, an uninsured driver crash, hail damage, theft, or a rollover where only your own vehicle is damaged.
Why financed and leased cars narrow your options fast
Lenders usually require collision and comprehensive until the loan is paid off. They are protecting the collateral, not your budget. If a financed car is totaled and the policy does not include collision, the owner may still owe the loan while getting no payment for the vehicle itself.
How much liability coverage is enough?
Liability coverage should be high enough that one bad crash does not force a driver to raid savings, lose wages to judgments, or expose major assets. For many households, that means treating the state minimum as a legal starting point and choosing materially higher bodily injury and property damage limits. A common benchmark people shop around is 100/300/100, but it is better thought of as a starting reference point than a universal rule. (NAIC advises buying more than the minimum if you have assets to protect, and the Insurance Information Institute explains the 100/300/100 split-limit structure.)
Bodily injury liability: the loss that can get very expensive very fast
Bodily injury liability pays for injuries or deaths a driver causes to others. Consumer Reports describes liability insurance as coverage for bodily harm or property damage to a third party. This coverage is mandatory in most states, and it is where low limits can fail first after a serious crash.
Limits are often shown as per-person and per-accident caps. In a common 100/300 format, the first number is the most the insurer pays per injured person, and the second is the total for all injured people in that crash. If damages exceed those caps, the at-fault driver can be pursued for the rest. That split-limit explanation is consistent with both the NAIC and the Insurance Information Institute.
Property damage liability: low limits meet high repair costs
Property damage liability pays for damage caused to another vehicle or property. That can mean a bumper, a storefront, a fence, road signs, or several parked cars. Modern vehicles pack expensive lights, sensors, cameras, and calibration work into what used to look like a minor impact.
The property damage cap is separate from bodily injury. A low property damage limit may still satisfy a state requirement, but I would call it thin protection in areas with newer vehicles and high labor rates. If you drive around a lot of newer trucks, SUVs, or EVs, a bare-minimum property damage limit can look inadequate pretty quickly.
How to choose limits without guessing
Use a simple rule set. First, consider what could be reached in a lawsuit: savings, home equity, future wages, business income, or other assets. Second, think about local claim severity. Dense traffic, expensive cars, and higher repair rates call for more room in the policy.
Liability coverage does not include a deductible. That means the issue is not whether a driver can absorb a deductible. The issue is whether the liability limit can absorb a serious claim.
Why the state minimum is rarely a smart target
Minimums are written to set legal compliance, and in many states those numbers are low enough that one ER visit, one newer pickup, or one chain-reaction crash can burn through them fast. For a driver with assets, dependents, or strong future earnings, the more sensible target is a limit that can absorb a meaningful injury claim and a costly property claim without turning the difference into personal debt. That is also why the NAIC consumer guide explicitly urges buyers to consider higher limits than the state minimum.
When should I carry collision and comprehensive?
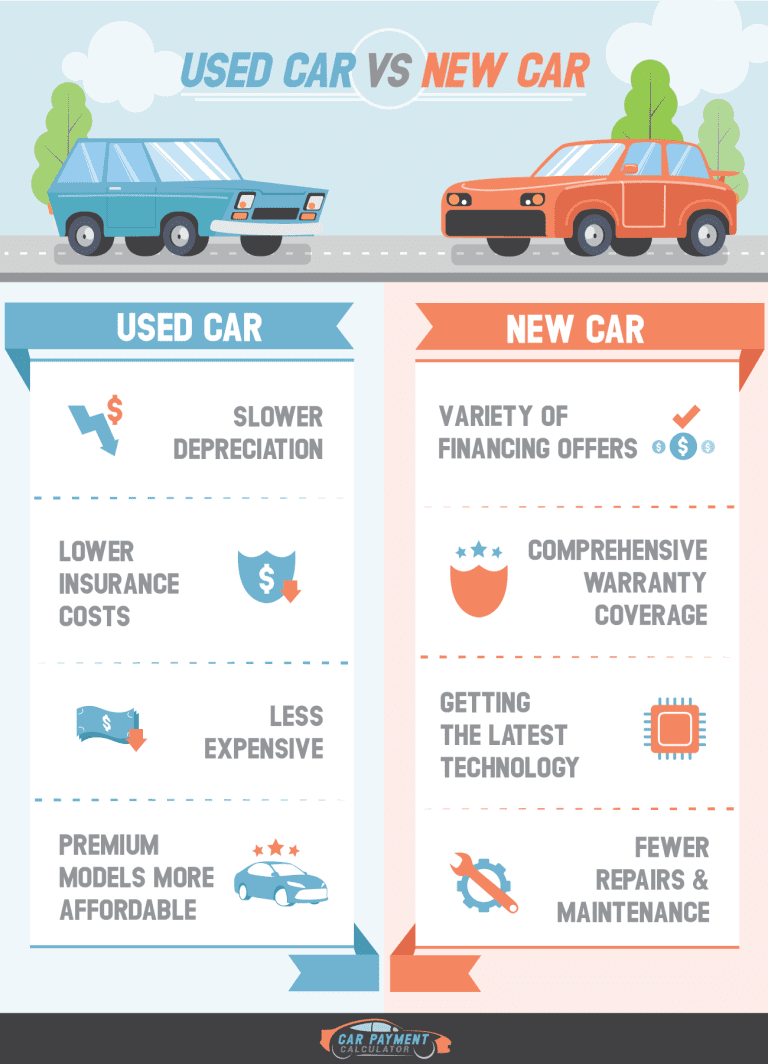
Carry collision and comprehensive when the car is expensive enough, financed, or difficult to replace from savings. Drop collision when the car’s value gets low enough that the premium plus deductible starts to approach the payout, but keep comprehensive longer if theft, weather, glass, or animal-strike risk remains meaningful.
Collision coverage: protect the car when the math still works
Collision pays for damage to your own vehicle after a crash, regardless of fault, subject to the deductible. This is one half of what people often call “full coverage,” though that phrase is loose market shorthand, not a formal policy type.
Collision and comprehensive coverages do have deductibles. If the deductible is high and the car’s actual cash value is low, collision can become weak value. The trigger to review it is simple: if a claim payment would be modest after the deductible, and the car could be replaced from savings, collision may no longer earn its keep.
Comprehensive coverage: often useful longer than collision
Comprehensive covers non-collision losses such as theft, weather-related damage, vandalism, falling objects, some glass damage, and animal strikes. A parked car can be stolen or hit by hail whether it is worth a lot or a little. That is why comprehensive often stays sensible after collision no longer does.
On low-value vehicles, comprehensive can still be worth paying for if theft rates are high, the car sits outside, severe weather is common, or replacing the vehicle quickly would still be painful.
The paid-off car test
Ask three questions. If the car vanished tomorrow, could it be replaced without debt? Would a payout after the deductible be large enough to matter? Is non-collision risk still real where the car is parked and driven? If the answers are yes, no, and yes, dropping collision while keeping comprehensive often makes sense.
Loan and lease requirements
Financed and leased vehicles usually leave little room for debate. The lender or lessor often requires both collision and comprehensive until the contract ends. That requirement does not answer whether the deductibles are set well, so drivers still need to choose deductible levels they can actually fund after a claim.
Which medical and uninsured-driver coverages are worth adding?
PIP, MedPay, and UI/UIM are worth adding when state law requires them or when health-cost and uninsured-driver gaps would otherwise land on the household budget. PIP matters most in no-fault states, MedPay is narrower but useful in some setups, and UI/UIM can rescue a claim when the other driver cannot pay.
PIP: no-fault medical coverage with broader uses
Consumer Reports notes that no-fault insurance is also called personal injury protection. PIP covers medical expenses regardless of fault and may also cover lost wages, childcare, and other related costs depending on the state and policy. It is mandatory in some no-fault states and optional or unavailable in others.
PIP matters most when a state requires it or when a household wants first-party medical benefits built into the auto policy. It can pay quickly after a crash even when fault is disputed.
MedPay: simpler and usually narrower than PIP
Medical payments coverage also helps with medical bills for the driver and passengers regardless of fault, but it is usually narrower than PIP. It does not commonly carry the same broader wage-loss or childcare features. It is required in only a small number of states.
MedPay can fit well where PIP is not available or where a driver wants extra auto-related medical coverage. It can become redundant when another policy setup already covers the same gap efficiently, so it should be checked against existing health coverage and any PIP already on the auto policy.
UI/UIM: the gap minimum-limit shoppers miss
Uninsured/underinsured motorist coverage can help pay for losses after you are hit by a driver with no insurance or not enough insurance. It is required in some states and optional in others. This is one of the most practical coverages on the menu because it protects against somebody else’s bad choices.
Liability-only shoppers often miss the real failure case here. They may carry legal coverage for damage they cause, yet have no useful way to recover enough for their own injuries when the other driver lacks insurance, disappears, or carries limits that run out early.
Failure cases that expose weak policies
- Hit-and-run: without UI/UIM, a driver may have no solid source of recovery for injuries after the at-fault car disappears.
- Uninsured driver: careful driving does not stop somebody else from running a red light with no policy in force.
- Low-limit driver: the at-fault policy may pay something, then run out far below the actual medical and property loss.
- Financed car totaled: liability-only does nothing for the borrower’s own vehicle damage.
How should I choose deductibles?
A deductible should be set at an amount the driver can comfortably pay on short notice, because collision and comprehensive claims are reduced by that amount. Higher deductibles can lower premiums, but the savings only help if the deductible does not become unpayable right after a crash, theft, or hail loss.
What a deductible changes
Consumer Reports defines a deductible as the amount you must pay before insurance pays the rest. It applies to collision and comprehensive, not liability. Choose it as a cash-flow decision first, then as a premium decision. (consumerreports.org)
A high deductible means the policy covers larger losses while the driver absorbs more small or medium losses. A low deductible shifts more repair cost to the insurer but raises the premium.
The emergency-fund test
If paying the deductible would force credit-card debt, missed bills, or borrowing from family, it is too high. If it can be paid the same week without wrecking the budget, it is probably workable.
This matters more than many buyers think. A cheap premium paired with an impossible deductible is a paper bargain.
When a high deductible works
A higher deductible fits drivers with stable savings, low claim frequency, and cars where small cosmetic damage would never be claimed anyway. It also fits households using insurance for big losses, not minor repairs.
When it backfires
It backfires when the driver parks on the street, commutes heavily, has a teen driver on the policy, or simply cannot write the deductible check after a loss. Consumer Reports also notes that less-experienced drivers and people who rack up lots of annual miles often pay more. In real life, those are also the households where a deductible needs to be realistic, not aspirational.
A simple repair-threshold rule for older cars
On older cars, compare the likely payout after the deductible with the annual premium for collision. If the car’s actual cash value is not much higher than the deductible plus a year or two of premium, collision is nearing its expiration date as a smart buy.
Coverage decision table by driver scenario
| Driver scenario | Likely best-fit coverage | Liability approach | Deductible range approach | Red-flag gaps |
|---|---|---|---|---|
| Financed new car | Liability, collision, comprehensive, UI/UIM; PIP or MedPay as state and household needs dictate | Start around 100/300/100 or higher if assets and income are meaningful | Use only a deductible that can be paid immediately after a total loss or major repair claim | Liability-only, missing UI/UIM, deductible too high to fund, no plan for loan gap exposure |
| Paid-off older car | Liability first; keep comprehensive if theft, weather, or animal-strike risk is real; review collision closely | Do not cut liability just because the car is old | Higher deductibles can work if savings are solid and minor damage would not be claimed | Dropping UI/UIM, keeping collision after payout value has become thin, carrying an unusable deductible |
| Teen driver household | Strong liability, collision and comprehensive on newer cars, UI/UIM, PIP or MedPay where useful | Lean higher because injury and property damage severity matter more than the premium savings | Avoid deductibles that parents could not cover twice in a bad year | State-minimum liability, low property damage caps, assuming careful supervision replaces coverage |
| High-asset household | High liability limits, UI/UIM, collision and comprehensive as vehicle value justifies, medical coverages by state setup | Set limits to reflect assets, income, and lawsuit exposure, not only the car’s value | Choose deductibles based on convenience and claim strategy, not desperation premium cutting | Minimum liability, weak property damage limit, forgetting that future wages can be exposed |
| Minimum-coverage shopper | State-required coverages at bare minimum only if the car is replaceable and finances are very tight; add UI/UIM first if possible | Recognize the legal minimum is often below the financially safe minimum | Any deductible chosen must still be payable from cash on hand | No collision on a car that cannot be replaced, no UI/UIM, assuming “full coverage” exists as a single standard package |
When to reduce car insurance coverage safely
Reduce coverage only after the loan is gone, the car’s value has dropped enough that collision pays little after the deductible, and the household can replace the vehicle without debt. Even then, cutting too far can leave uninsured-driver, theft, weather, and lawsuit gaps that cost more than the premium saved.
After the loan is paid off
This is the first major review point. Once the lender no longer requires collision and comprehensive, the decision becomes purely financial. Keep asking whether the expected payout after deductible is still large enough to matter.
When collision stops paying back
If a low-value vehicle would produce only a modest claim payment after the deductible, collision may be weak value. That does not mean the whole policy should be stripped down. Liability can still need to stay high, and comprehensive may still have a job.
When keeping comprehensive still makes sense
Comprehensive often survives longer because theft, hail, vandalism, broken glass, and animal strikes still happen to older cars. A modest premium for comprehensive can still be sensible when replacing even an older vehicle quickly would be difficult.
Red flags to fix before cutting anything
- The deductible already strains the emergency fund.
- The car is required for work and cannot be replaced promptly.
- The policy lacks UI/UIM in an area with many uninsured or low-limit drivers.
- Liability limits still sit at the state minimum even though assets or wages have grown.
How to read a policy and spot underinsurance or waste
A policy is balanced when liability limits match lawsuit risk, first-party coverages match the car’s replacement risk, and deductibles match available cash. It is underinsured when one claim could spill into savings or debt, and overinsured when premiums protect losses the driver could easily absorb alone.
What car insurance terms should I know
Premiums are what policyholders pay to insurers for coverage. Consumer Reports uses the same basic definition. A claim is the request for payment after a covered loss. A limit is the most the insurer pays on a claim.
Actual cash value is the vehicle’s depreciated value at the time of loss. Total loss means the car is damaged badly enough that the insurer pays its value rather than repairs it. An exclusion is something the policy does not cover. An endorsement is a policy change that adds, removes, or modifies coverage.
How to tell if the policy is underinsured
It is underinsured if liability limits are low relative to assets and earnings, if UI/UIM is missing where it is available, if a financed car lacks required physical damage coverage, or if the deductible cannot be paid. It is also underinsured when the household depends on the car but has no realistic replacement plan.
How to tell if the policy is overinsured
It may be overinsured if collision remains on a low-value paid-off vehicle even though the maximum realistic payout is small after the deductible, or if medical coverages duplicate one another without filling a real gap. Overinsurance is usually a mismatch problem, not simply “too much coverage.”
A one-page renewal checklist
- Check state-required coverages for the current garaging state.
- Review bodily injury and property damage limits against assets, income, and local repair severity.
- Confirm whether any car is financed or leased and therefore needs collision and comprehensive.
- Estimate each car’s current actual cash value and compare it with collision deductible and premium.
- Decide whether comprehensive still earns its keep based on theft, weather, glass, and animal-strike risk.
- Verify UI/UIM, PIP, or MedPay based on state law and household medical-gap risk.
- Set deductibles at amounts that can be paid immediately from savings.
- Read exclusions and endorsements so the policy matches actual use of the vehicle.
How much should car insurance cost
Cost follows the coverage stack. Higher liability limits, lower deductibles, newer vehicles, frequent driving, and claim-prone locations all push premiums upward. There is no honest national “right” price for everyone. Broad averages can be useful for context, but they are not budgeting targets because rate filings vary by state, vehicle, driver history, mileage, and coverage choices. For a national benchmark, the NAIC’s most recent published average auto insurance expenditure is a little over $1,100 annually, but any individual policy can land far below or far above that depending on risk and coverage.
That is why I do not put much weight on ultra-cheap advertised starting prices. I have seen policies that looked like bargains until I noticed stripped-down liability limits or deductibles the owner could not realistically pay. The right cost is the price of a policy that fits the driver’s legal requirements, vehicle value, savings, and lawsuit exposure without paying for coverages that no longer make sense.
Frequently asked questions
what should my car insurance coverage be
It should start with liability limits strong enough to protect savings, wages, and other assets, then add collision and comprehensive only if losing the car would hurt financially. UI/UIM deserves serious attention, and PIP or MedPay depends on state rules and the household’s medical-coverage gaps.
what to cover in car insurance
Cover the losses that would hit hardest: injuries you cause to others, damage you cause to other property, and damage or loss to your own car when replacing it from cash would be difficult. Then decide whether PIP, MedPay, and UI/UIM close real gaps or just duplicate protection you already have.
how much car insurance coverage do i need
The answer depends less on the car alone and more on asset exposure, income, loan status, and replacement risk. A financed newer car usually needs collision and comprehensive, while an older paid-off car may not. Liability limits should reflect lawsuit risk, not simply the minimum needed to register the vehicle.
what is recommended for car insurance coverage
A sensible baseline is liability well above the state minimum, with collision and comprehensive on financed or hard-to-replace vehicles. A common benchmark is 100/300/100, but the better answer is enough liability to protect assets and enough physical-damage coverage to avoid a car-replacement crisis. UI/UIM is often one of the best add-ons because it covers somebody else’s lack of insurance. Deductibles should match available savings, not a wish for a lower bill.
when to reduce car insurance coverage
Reduce coverage after the loan is paid off, the car’s value has fallen enough that collision produces little net benefit, and the household could replace the car without debt. Before cutting anything, confirm liability limits are still adequate and make sure UI/UIM and comprehensive are not being dropped thoughtlessly.
how much should car insurance cost
There is no single correct price because premiums reflect limits, deductibles, vehicle value, mileage, driver experience, location, and claims history. Cheap can mean underinsured, while expensive can mean mismatched coverage. Judge cost against the policy’s real job: preventing a crash, theft, or lawsuit from becoming a budget crisis.
For readers who want the source trail behind the key examples in this guide, the state-law references above come from New York DMV and Florida Highway Safety and Motor Vehicles materials, the coverage and limit concepts track the NAIC Auto Insurance Guide and Insurance Information Institute explanations of split limits, and the broad premium context comes from NAIC average expenditure data. The short version is simple: buy enough liability insurance to protect what you have, keep collision coverage and comprehensive coverage while the car would be hard to replace, and use PIP or MedPay and UI/UIM to close the gaps that would otherwise come back to your own budget.