Best Auto Insurance for New Drivers: Budget Guide
For new drivers on a budget, the best auto insurance is usually a liability-only policy, or liability plus collision if the car is worth more than about 10 times the deductible, with a deductible the driver can pay today. I have seen people buy too much coverage for a worn-out car, then keep paying for years. Others buy too little and get stuck with a repair bill they cannot cover. This guide shows how to balance premium, deductible, car value, and emergency cash to buy the cheapest sensible policy.
How to buy the cheapest sane policy as a new driver
The cheapest sane policy starts with the car, the loan status, and the cash available after a loss. If the driver cannot replace a windshield, bumper, or totaled car without borrowing, the cheapest quote is not always the cheapest choice.
Pick the coverage level first, then shop price. Decide whether the car needs liability only, liability with comprehensive, or full coverage before comparing deductibles and discounts.
Start with car value, loan status, and emergency savings
Car value decides how much protection is worth buying. Loan or lease status changes the answer because lenders usually require collision and comprehensive until the balance is paid down.
Emergency savings matter just as much. A driver with $300 in spare cash should not choose a $1,000 deductible just because the monthly premium drops.
Use monthly premium and out-of-pocket risk together
A low premium can hide a painful deductible. The real budget question is whether the driver can pay the premium every month and still absorb the deductible after a crash, theft, hailstorm, or deer strike.
For a first policy, that means thinking in two numbers: the monthly bill and the amount due after a claim. If either one breaks the budget, the policy is too thin or too expensive.
What auto insurance new drivers actually need
New drivers usually need liability coverage first, then add collision or comprehensive only when the car value, lender rules, or savings justify it. State minimums are the floor, not a safety net for every situation.
Minimum coverage can be legal and still leave a driver exposed to a large repair or injury bill. The goal is to avoid a loss that would wreck the budget.
Liability coverage and your state minimums
Liability coverage pays for injuries and property damage the driver causes to others. States set minimum bodily injury limits and property damage limits, and those minimums vary a lot.
Low limits are the cheapest baseline for many budget shoppers, but they can be too thin if the driver causes a serious crash. A minimum-limit policy can protect the wallet from a monthly bill, yet still leave the driver exposed to a claim above the limit.
When collision coverage belongs in the budget
Collision coverage pays for crash damage to the driver’s car. It is usually optional on an older, paid-off car, but lenders and lessors often require it.
It makes more sense when the car would cost enough to repair or replace that the driver could not absorb the loss. On a car worth only a few thousand dollars, collision can be hard to justify if the deductible is high and the premium jump is large.
What comprehensive coverage adds for theft and weather
Comprehensive covers theft, vandalism, weather damage, glass breakage, fire, and animal hits. It is paired with collision for full coverage, though it can sometimes be bought without collision.
It is often worth keeping on a car that would hurt to replace out of pocket, even if the car is older. If the car is low-value and the driver has cash to absorb a total loss, comprehensive may be optional.
How deductibles change the real cost of a claim
The deductible is the amount the driver pays before insurance pays the rest of a covered loss. Common deductible choices are often around $250, $500, and $1,000.
A higher deductible usually cuts the premium, but only helps if the driver can pay it after an accident. A deductible that cannot be paid in an emergency is not a savings tool; it is a trap.
Should you stay on a parent’s policy or buy your own?
A family policy is often cheaper for a teen or college student because the household may get a better rate structure than a separate policy. A separate policy can make sense when the driver lives apart, owns a car outright, or has household factors that push the family rate too high.
The cheapest option depends on the address, the car, and who actually drives it. Adding a new driver to the wrong household setup can raise the whole policy more than expected.
When a family policy is usually cheaper
Young drivers, especially teens, are often priced more favorably when added as a named driver on a parent’s policy. Multi-car pricing can help too.
This is especially useful when the teen shares the family address and the car is used with parental oversight. It can also simplify claims and coverage coordination.
When a separate policy makes more sense
A separate policy may fit an adult first-time driver who lives independently, commutes alone, and owns a car in their own name. It also makes sense when the household policy would be penalized by a high-risk driver or a recent violation.
Insurance follows the garaging address and the real use pattern. If the address or primary use is wrong, the price can be wrong too.
How household rating and address changes can affect price
Carriers rate by household, drivers, vehicle, and location. Moving to a new ZIP code, changing who parks the car overnight, or switching from a family policy to a separate policy can change the premium fast.
A gap after a move or policy switch can also hurt later pricing. Continuous coverage matters more than many new drivers expect.
Which discounts matter most for first-time drivers?
Discounts can help, but they do not fix the wrong coverage choice. The most useful ones for first-time drivers usually come from grades, telematics, training, and household structure.
The best discount is the one that lowers cost without forcing the driver into a policy that is too thin or a deductible that is too high.
Good student discount rules that often apply
The good student discount often applies to full-time students who meet a B-average or similar GPA requirement. Exact rules vary by insurer and state.
It can matter a lot for teen and college drivers because their base price is already high. It is one of the few discounts that can cut real dollars off a first policy without changing coverage.
Telematics and low-mileage programs
Telematics or usage-based insurance tracks driving behavior, mileage, or both. Safe, low-mileage drivers may pay less, while hard braking, late-night driving, or frequent high-risk trips can push rates up.
It is a good fit for a careful commuter who drives little. It is a poor fit if driving habits are erratic or the driver does not want the insurer watching the trip data.
Defensive driving and driver training discounts
Some insurers offer discounts for approved driver training or defensive driving courses. These discounts can be modest, but they are useful when the course cost is low and the driver is new.
For teens, training can also improve real-world habits. For adults new to driving, it may help offset the lack of history insurers use to price the policy.
Bundling and multi-car savings without overbuying coverage
Bundling home and auto, or putting multiple vehicles on one household policy, can lower price. It should not be used as a reason to buy more coverage than the car needs.
A discount on the wrong policy is still the wrong policy. The coverage decision comes first.
Decision table: the cheapest sane coverage by driver scenario
This table ties the policy choice to car value, loan status, and emergency savings. The point is not to buy the lowest quote. It is to buy the lowest-cost coverage that still protects the driver from a bill they cannot absorb.
| Driver scenario | Cheapest sane coverage | Why it fits | Watch-out |
|---|---|---|---|
| Older paid-off car, value under about $4,000, and at least $1,000 in emergency cash | Liability-only | Repair cost may exceed the car’s value, so collision and comprehensive can cost more than they are worth | Keep liability limits high enough to protect savings from a serious claim |
| Older paid-off car, value around $5,000 to $10,000, and $1,000 to $2,500 in emergency cash | Liability plus comprehensive | Protects against theft, hail, glass, and animal hits while skipping crash coverage if the car would not justify full coverage | Do not choose a deductible higher than the cash reserve |
| New car with a loan or lease | Full coverage | Lender or lessor usually requires collision and comprehensive until the loan balance drops and the car still has value to protect | Minimum liability alone can violate contract terms |
| Teen on a family policy, modest car, shared household address | Family policy with liability, collision, and comprehensive as needed | Household pricing and shared discounts often beat a separate policy for a new teen driver | Make sure every driver and car is listed correctly |
| Adult first-time driver, no emergency fund, car worth under about $5,000 | Liability-only with the strongest affordable limits | Protects against injury and property claims without forcing a deductible the driver cannot pay | A cheap claim on the car may still be a total loss for the owner |
| Low-mileage driver who can use telematics, car worth $6,000 to $12,000 | Liability plus comprehensive, or full coverage if the premium gap is small | Telematics can reduce cost for careful, low-use driving while still protecting against non-crash losses | Monitor whether the program penalizes night driving or heavy braking |
How to choose a deductible without setting yourself up for a bill you cannot pay
The deductible should match real emergency cash, not wishful thinking. A lower deductible usually means a higher premium, but a higher deductible only helps if the driver can pay it after a loss.
For many new drivers, $500 may be a middle-ground deductible. $1,000 can work when savings are healthy. $250 may be sensible when the premium difference is small and the budget can handle it.
$250 versus $500 versus $1,000
A $250 deductible can reduce out-of-pocket strain after a claim, but it may raise the premium enough that it is not the cheapest long-term choice. A $500 deductible is the common balance point.
A $1,000 deductible can trim the bill, but it may be a poor fit if the driver could not replace that money quickly. The savings vanish the moment the claim happens and the account is empty.
Match the deductible to emergency savings
Emergency savings should cover the deductible plus a little breathing room for towing, glass, or transportation costs. If the car is the only way to work or school, the backup plan matters as much as the coverage.
If the deductible would force credit card debt or a family loan, it is too high. That is true even if the monthly premium looks attractive.
When a higher deductible is a false saving
A higher deductible is a false saving when the premium drop is small or the car is low-value and prone to total loss. It can also be false savings if the driver carries the policy only to avoid a big repair bill that still cannot be paid later.
In that case, the policy is cheaper only on paper. Real savings come from picking a deductible the driver can actually cover.
What drives first-driver pricing besides the quote itself?
Insurers price new drivers with limited history, and they may also use credit-based pricing where state law allows it. Age, location, vehicle type, driving record, and lapse history all matter.
That means a cheap quote can turn expensive fast if the driver has a violation, a move, or an SR-22 requirement.
Insurance score and credit-based pricing where allowed
Some states allow credit-based insurance scoring, and it can matter for first-time buyers. The score is not the same as a credit score, but it is often built from similar data.
Drivers with thin credit files may see less favorable pricing because the insurer has little to measure. Building ordinary credit can help in states where this pricing method is allowed.
Driving record, age, and location
New drivers are often expensive because the insurer has little or no driving history to price from. Teen drivers often pay more than adult first-time drivers, and urban areas can cost more than rural ones.
Parking location, commute length, and annual mileage all influence the rate. The same driver can look cheap in one ZIP code and expensive in another.
SR-22 filings and high-risk surcharges
An SR-22 is a filing requirement, not a type of insurance policy itself. It usually follows certain serious violations or lapses and can materially increase costs.
Drivers with an SR-22 often need to stay extra careful about continuous coverage. A lapse can restart the pain.
Why coverage gaps and lapses can make the next policy pricier
A coverage gap after a move, policy cancellation, or delayed switch can raise the next quote. Insurers often read a lapse as a sign of risk, even when the lapse was accidental.
That is one reason the replacement policy should be lined up before the old one ends. Continuous coverage is worth protecting.
What coverage should a new driver never skip even when shopping cheap?
A new driver should never skip liability coverage that meets state minimums, and in many cases should buy limits above the bare minimum if the driver has assets or regular income. Minimum legal coverage is not the same as enough protection.
If the car is financed, collision and comprehensive are often nonnegotiable because the lender can require them. The policy should also never include a deductible the driver cannot pay right away.
How can parents insure a teen driver without overpaying?
Parents usually save money by adding the teen to a family policy, choosing the right car, and avoiding coverage that exceeds the car’s value. The cheapest setup is often a modest vehicle, strong liability limits, and only the physical damage coverage the car truly needs.
Teen driving costs can jump when the policy structure is wrong. A careful household setup matters more than chasing the lowest sticker quote.
Choose the right car first
A safer, cheaper-to-repair car often costs less to insure than a sporty or high-powered one. Repair costs and theft risk feed into pricing.
A modest sedan or compact car can keep both premium and deductible risk under control. That matters more than fancy trim or extra horsepower.
Use discounts without stretching coverage
Good student, training, telematics, and multi-car discounts can help families manage cost. They should be used to reduce the bill on the right policy, not to justify a deductible the family cannot pay.
If the teen drives little and safely, a usage-based program may help. If the driving pattern is erratic, the family may be better off with a standard policy.
Frequently asked questions
What is the cheapest auto insurance for a new driver?
The cheapest policy is often liability-only on an older paid-off car, especially when the vehicle value is low and emergency savings are limited. If the car is financed or worth enough to protect, liability plus comprehensive or full coverage may be the cheaper sane choice after the risk is considered.
How can a new driver lower car insurance costs on a budget?
Start with the right coverage level, then adjust the deductible and discounts. Good student status, telematics, driver training, a family policy, and a clean record can all help, but none of them fix a policy that is too weak for a financed car or too expensive for the budget.
Is liability-only insurance enough for a new driver?
Liability-only can be enough for a new driver with an older paid-off car and little emergency cash, especially when the car’s value is lower than the cost of adding physical damage coverage. It is usually not enough for a financed or leased car, or for a driver who cannot absorb a large repair bill.
What discounts do insurance companies offer for new drivers?
Common discounts include good student, driver training, telematics or low-mileage programs, multi-car, and sometimes bundling. Savings vary by insurer and state, and some discounts come with tradeoffs. Telematics can lower rates for careful drivers, but it can also raise them if driving habits look risky.
Should a new driver stay on a parent’s policy or get their own?
Many teens and college students cost less on a parent’s policy, especially when they live at home or share a household address. A separate policy can fit adult first-time drivers living independently, but the family should compare both setups because address, vehicle, and household rating can change the result.
How much does auto insurance cost for a new driver?
There is no single number because age, location, vehicle, credit-based pricing rules, record, and coverage all change the price. New drivers usually pay more than experienced drivers because insurers have little or no history to price from, so the same coverage can vary a lot from one person to the next.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 Auto Car Dent Repair Puller Head Paintless-Dent Repair Removal Kit for Slide Hammer Pulling Tab Adapter Pulling Tabs Car Aluminum-alloy Puller Head Adapter Screw Glue-tabs for Slide Hammer and
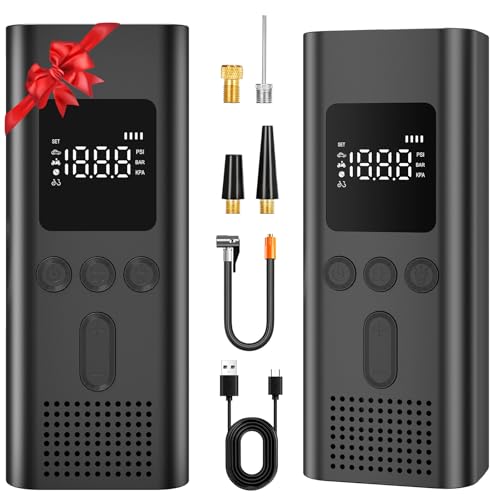 AIRSURE Tire Inflator Portable Air Compressor with Auto Shut-Off,Pack of 2
 AIRSURE Tire Inflator Portable Air Compressor with Auto Shut-Off,Pack of 2