Do You Need Car Insurance for DoorDash? Coverage Gaps Explained
Quick Answer
Yes, you need your own car insurance to drive for DoorDash. DoorDash’s own coverage — up to $1 million in third-party liability, plus contingent damage coverage for your car — only applies during an active delivery, from the moment you accept an order until it’s dropped off, canceled, or unassigned. While you’re just logged in waiting for an order, DoorDash provides nothing at all, and most personal auto policies exclude “business use” like paid deliveries, so you could be left without coverage in that gap unless your policy specifically allows delivery driving.
Driving for DoorDash turns a personal errand into paid commercial work the moment you accept a delivery, and that distinction matters a lot to your insurance company. Most standard auto policies are written for personal use only, and DoorDash’s own insurance is narrower than a lot of Dashers assume. Here’s exactly what’s covered, what isn’t, and where the real gap sits.
What DoorDash’s Insurance Actually Covers
DoorDash maintains insurance for U.S. Dashers, but it only applies during what DoorDash calls the “Delivery Service Period” — the window that starts when you accept a delivery request and ends when the order is marked delivered, canceled, or unassigned. It has three separate parts.
$1 Million in Third-Party Liability
If you cause an accident while actively on a delivery, DoorDash provides third-party auto liability coverage up to $1 million for bodily injury or property damage to other people involved in the crash. This is the coverage most people mean when they say “DoorDash has insurance.”
Contingent Comprehensive and Collision for Your Own Car
DoorDash also carries contingent comprehensive and collision coverage for damage to your own vehicle during an active delivery — but with a $2,500 deductible, and it’s secondary to your personal policy. That means your own insurer has to respond first; DoorDash’s coverage only steps in if your policy doesn’t apply or doesn’t fully cover the loss. If you don’t carry comprehensive or collision on your own policy at all, this contingent layer is the only thing standing between you and a $2,500+ repair bill.
Occupational Accident Insurance (For You, Not Your Car)
Separately, DoorDash automatically provides Occupational Accident coverage for U.S. Dashers at no cost — no sign-up, no premium, no deductible. If you’re injured while actively delivering, it can pay up to $1,000,000 in medical expenses and disability payments equal to 50% of your average weekly earnings, up to $500 a week. It does not cover damage to your car or your delivery bag; it only covers your own injuries.
Documents Accidents Automatically
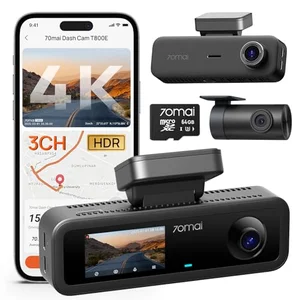 |
70mai 4K Dash Cam T800E (Front, Rear & Interior) – $99.99 A dash cam will not replace your own insurance, but timestamped front-and-cabin footage is exactly what insurers and DoorDash both want to see when a delivery-related claim is disputed.
|
The Coverage Gap Most Dashers Do Not Know About
The part of DoorDash’s coverage that surprises people isn’t what it includes — it’s when it doesn’t apply at all. If you’re logged into the Dasher app and available for orders but haven’t accepted a delivery yet, DoorDash provides zero liability coverage. Your own personal auto insurance is the only thing protecting you, and if your insurer classifies that as “business use,” it may deny a claim from that window entirely.
| Situation | What’s Happening | Who Covers You |
|---|---|---|
| App closed | Not dashing at all | Your personal auto policy only |
| Waiting for an order | App is on, no delivery accepted yet | Your personal auto policy only — DoorDash provides nothing here |
| Active delivery | Accepted an order, until it’s delivered, canceled, or unassigned | DoorDash’s $1M liability + contingent comp/collision (secondary, $2,500 deductible), plus Occupational Accident coverage for you |
Does Your Personal Car Insurance Cover DoorDash Driving?
Not automatically, and this is the single most important thing to check. Most personal auto policies are written for commuting, errands, and everyday driving — many insurers specifically exclude accidents that happen while you’re using your car for paid delivery work, sometimes called “business use.” If your insurer finds out you were dashing at the time of a crash, even a small one, that alone can be grounds to deny a claim on your personal policy.
The fix isn’t necessarily a full commercial policy. Many insurers now sell a delivery endorsement — a relatively inexpensive add-on to your existing personal policy that extends coverage to include food and package delivery driving, closing the exact gap DoorDash’s insurance leaves open. Not every carrier offers one, and not every endorsement covers food delivery specifically (some are written for rideshare only), so call your agent, name DoorDash by name, and ask them to confirm in writing. If your insurer won’t extend coverage at all, a standalone commercial auto policy is the fallback, though it typically costs more.
State Legal Minimums Still Apply
Regardless of DoorDash’s coverage, every state (aside from New Hampshire and Virginia, which have their own alternative rules) requires you to carry at least the state’s minimum liability insurance to legally drive at all, delivery or not. Minimums vary significantly from state to state, and basic liability alone won’t cover damage to your own car. Check your state DMV’s current minimums, and don’t assume the legal minimum is enough protection just because it’s enough to satisfy the law.
What to Do If You’re in an Accident While Dashing
If you’re in a crash during an active delivery, treat it like any other accident, but keep DoorDash in the loop too.
- Check for injuries and call 911 if anyone is hurt or the damage is significant.
- Photograph the scene, both vehicles, and any visible damage before anything is moved, if it’s safe to do so.
- Exchange information with the other driver and get contact info for any witnesses.
- File a police report — most insurers, including DoorDash’s, will ask for one before processing a claim.
- Report the accident to DoorDash through the app or Dasher support, and separately notify your own personal insurer, even if you think DoorDash’s coverage will apply.
- Keep every receipt tied to the accident (towing, a rental car, repairs) for reimbursement later.
An adjuster will review the damage and the circumstances of the accident to determine what’s covered and by whom. Because DoorDash’s vehicle-damage coverage is secondary to your own policy, expect your personal insurer to be the first call regardless of who was at fault, unless you’ve confirmed with your agent ahead of time that delivery driving is excluded.
Frequently Asked Questions
Does DoorDash provide car insurance for its drivers?
Yes, but only during an active delivery. DoorDash provides up to $1 million in third-party liability coverage and contingent comprehensive/collision coverage (secondary, $2,500 deductible) from the moment you accept an order until it’s delivered, canceled, or unassigned. It provides no coverage at all while you’re logged in but not yet delivering.
What is the DoorDash “Delivery Service Period”?
It’s the specific window DoorDash’s insurance applies to: starting when a Dasher accepts a delivery request and ending when the order is marked delivered, unassigned, or canceled. Outside of that window, including while online and waiting for a delivery, a Dasher’s own auto insurance is the only coverage in effect.
Will DoorDash pay to fix my own car after an accident?
Possibly, but only as a secondary, contingent coverage during an active delivery, and only after a $2,500 deductible. Your personal insurance is expected to respond first; DoorDash’s coverage only fills in the gaps if your policy doesn’t fully cover the damage.
Does my personal car insurance cover DoorDash deliveries?
Not automatically. Most personal auto policies exclude accidents that happen during paid delivery work, since insurers classify it as business use. Call your insurer, tell them you drive for DoorDash, and ask whether your policy needs a delivery endorsement or a different type of coverage to stay valid while you’re dashing.
What kind of insurance do you need to drive for DoorDash?
You need your state’s minimum personal auto liability insurance to legally drive at all, plus ideally a delivery endorsement (or a commercial policy, if your insurer won’t extend personal coverage) so you’re actually protected during the gap DoorDash’s own insurance leaves open.
How much does delivery driver insurance add to my premium?
It varies by insurer, state, driving record, and how many hours a week you dash, so there’s no single number that applies to everyone. A delivery endorsement is typically far cheaper than switching to a full commercial auto policy, so it’s worth calling your current insurer first before assuming you need to switch companies entirely.
What are the requirements to drive for DoorDash?
To drive for DoorDash, you generally need to be at least 18 years old, have a valid driver’s license, carry your own auto insurance, own an eligible vehicle, and pass a background check. Requirements can vary slightly by market, so double-check the current list for your city before signing up.
The Bottom Line
DoorDash’s insurance is real, but it’s narrower and more conditional than a lot of Dashers assume: it only kicks in during an active delivery, it treats your own car’s damage as secondary to your personal policy, and it covers nothing during the time you’re logged in just waiting for an order. The only way to close that gap is on your end — confirm with your own insurer, in writing, that your policy either allows delivery driving or has been endorsed to cover it. Skipping that step is the single most common way Dashers find out, the hard way, that they weren’t actually covered.