How to Remove Someone From a Car Loan: 4 Real Options
Removing someone from a car loan takes one of four paths: a lender-approved cosigner release, refinancing the loan solely in your name, paying it off entirely, or selling/trading in the vehicle. Which one actually works for you depends on your loan contract and your credit – here’s how each option really works, including the specific requirement most guides leave out.
Cosigner Release: The Option Most People Miss
Before you assume you need to refinance, check your original loan agreement for a cosigner release clause – it’s the cleanest way to remove someone without touching your interest rate or loan term. Not every auto loan offers this, so it genuinely is contract-specific, not something every lender provides automatically.
Where it exists, a cosigner release almost always requires a track record first: most lenders want to see 12 to 24 months of consecutive, on-time payments before they’ll even consider the request, and the remaining borrower’s credit needs to be strong enough to stand on its own without the cosigner. If your loan doesn’t offer this option at all, the lender should tell you directly – at that point refinancing becomes the more realistic path.
Keep Your Paperwork Straight
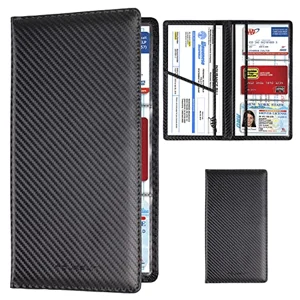 |
Car Registration and Insurance Card Holder – $7.99 Removing a cosigner means new loan documents, updated registration, and possibly a new insurance card – keeping them together in one holder makes it easy to find what your lender asks for.
|
Review the Loan Agreement First
Start by reading the actual loan document, not just assuming what it says. Look specifically for language on removing a co-borrower or cosigner, whether a release fee applies, and what the co-signer’s legal role actually is – a cosigner shares full responsibility for the debt, meaning if they’re removed, the remaining borrower becomes solely on the hook for the entire remaining balance. Confirm the remaining borrower can realistically handle full payments alone before starting the process.
Contact the Lender
Gather your loan number, account details, and identification, then call the lender directly to ask what your specific options are. Some lenders require a written request; others process a cosigner release through a specific form. Be prepared to submit updated income and financial documents for the remaining borrower, since the lender needs to confirm they qualify to carry the loan alone. This can take anywhere from a few days to a few weeks – stay in contact until you have written confirmation the change is complete.
Refinancing to Remove a Cosigner
If a cosigner release isn’t available, refinancing the loan in the remaining borrower’s name alone is the next most common route. This replaces the existing loan with a brand-new one, which can also change your interest rate and monthly payment – for better or worse, depending on current rates and the remaining borrower’s credit profile since the loan was first taken out.
| Step | Action |
|---|---|
| 1 | Check your credit score |
| 2 | Research lenders offering solo refinancing |
| 3 | Compare rates and terms |
| 4 | Apply for refinancing in one name only |
| 5 | Review the new loan terms carefully |
| 6 | Sign the new agreement |
| 7 | Confirm the cosigner is officially released |
Loan Assumption
A less common option is loan assumption, where a different person entirely takes over the existing loan in place of the current borrower. The new borrower has to independently meet the lender’s credit and income requirements – this isn’t automatic, and the lender will run a full financial review before approving the switch.
Selling or Trading In the Car
Selling the car and using the proceeds to pay off the loan removes both names entirely once the title transfers to the new owner. Trading it in at a dealership works the same way – the dealer pays off the existing loan as part of the transaction, and if you’re financing a new vehicle, only the remaining borrower’s name needs to go on the new contract.
What This Does to Credit
Removing someone from a car loan affects both people’s credit, and not always the same way. The remaining borrower’s credit utilization and payment history continue as before. For the person being removed, the account simply stops appearing on their credit report going forward – if it had a strong on-time payment history, losing that positive history can cause a small, temporary dip; if it had late payments, being removed generally helps their score. Either way, confirm the change actually shows up on both credit reports after the process completes, since lenders don’t always update this immediately.
Frequently Asked Questions
How Can I Remove Someone From My Car Loan Without Refinancing?
Check your loan agreement for a cosigner release option first – most lenders that offer it require 12-24 months of on-time payments and proof the remaining borrower qualifies alone. Paying off the loan entirely, or selling/trading in the car, also removes both names without a refinance.
How Do I Remove My Ex From My Car Loan?
Contact your lender to ask about a cosigner release first, since it’s the simplest option if your loan offers one. If not, refinancing the loan solely in your name, or selling the car and paying off the balance, are the other realistic paths.
How Do I Remove a Co-Applicant From My Car Loan?
Contact your lender directly and ask specifically about a cosigner/co-applicant release or a solo refinance. The remaining borrower will need to qualify independently on credit and income, and you’ll need to submit updated financial documentation either way.
How Long Do You Have to Wait to Remove a Cosigner From a Car Loan?
Most lenders that offer a cosigner release require 12 to 24 months of consecutive, on-time payments before they’ll approve the request. This requirement varies by lender, so check your specific loan contract for the exact terms.
If you specifically need to remove a co-signer rather than a co-borrower, see our dedicated guide to removing a co-signer from a car loan for that narrower process.
Conclusion
Check your loan contract for a cosigner release option before assuming you need to refinance – it’s the most direct path, but it typically requires 12-24 months of on-time payments first. If your loan doesn’t offer one, refinancing, paying off the balance, or selling/trading in the vehicle all work, each with different effects on the remaining borrower’s rate, payment, and both parties’ credit.