Navigating Insurance Options for a Car-Centric Lifestyle
Set liability limits against your income and assets, keep collision and comprehensive on financed or newer cars, and choose deductibles you can pay from savings. Thin coverage can leave you paying for repairs, claims, or lawsuits after one busy commute or a parking-lot loss. This guide shows how mileage, parking, vehicle value, and loan terms should shape each coverage choice.
What coverage do daily drivers actually need?
Daily drivers face more chances to cause a claim, collect a ding, or meet an uninsured motorist. Start with liability, then add collision, comprehensive, and uninsured motorist protection when the car’s value, loan balance, parking exposure, or commute risk justifies the premium.
The core coverages every driver should understand
Liability insurance pays for injuries and property damage you cause to others. Collision covers your car after a crash. Comprehensive covers theft, vandalism, hail, flooding, fire, and similar non-crash losses. Uninsured motorist coverage helps when the at-fault driver has no insurance.
Deductibles set what you pay before the insurer pays on collision or comprehensive claims. Policy limits set the insurer’s top payout. Those two settings shape how much of a loss lands on you after a fender-bender, a sideswipe, or a storm-damage claim.
Where state minimum coverage falls short
State minimums are written to meet the law, not to protect a commuter with assets, wages, or a newer car. A short commute does not mean short exposure. One crash on a crowded arterial road can create medical bills and repair costs that blow past low limits quickly.
Underinsuring a heavily used car can leave a driver exposed after a serious accident. That risk rises when the vehicle is driven every day, parked on the street, or used in dense traffic where more collisions happen at low speed and high frequency.
How do liability limits protect your finances?
Liability coverage protects your income and assets when you are at fault. Higher limits matter because daily driving raises claim exposure, and a serious injury claim can run far beyond state minimums. If you own property, have savings, or earn a steady paycheck, low limits are weak protection.
What liability coverage pays for
Liability has two jobs: bodily injury and property damage. It pays others for medical bills, lost income, repair bills, and related losses that you cause. It does not repair your own car. It also does not make a low limit feel larger when the claim is bigger than the policy.
How to think about income, assets, and risk
Think in layers. First, ask what your paycheck could support after a claim. Next, look at savings, home equity, and other assets that could be exposed. Then consider how much traffic, mileage, and parking exposure your routine creates. Higher exposure calls for higher liability limits.
A common first-timer mistake is buying the cheapest liability limit because the state requires it. Suppose a driver with a decent salary and a paid-off car causes a crash that injures two people and totals another vehicle. Minimum coverage may pay out early, leaving the driver personally exposed to the rest.
Failure case: when minimum limits are not enough
State minimum coverage can fail in three ways. It can run out on property damage alone. It can run out on medical claims before everyone is paid. And it can leave the driver owing the difference after the insurer has paid its cap. That is where assets and wages become part of the risk.
When should you add collision and comprehensive?
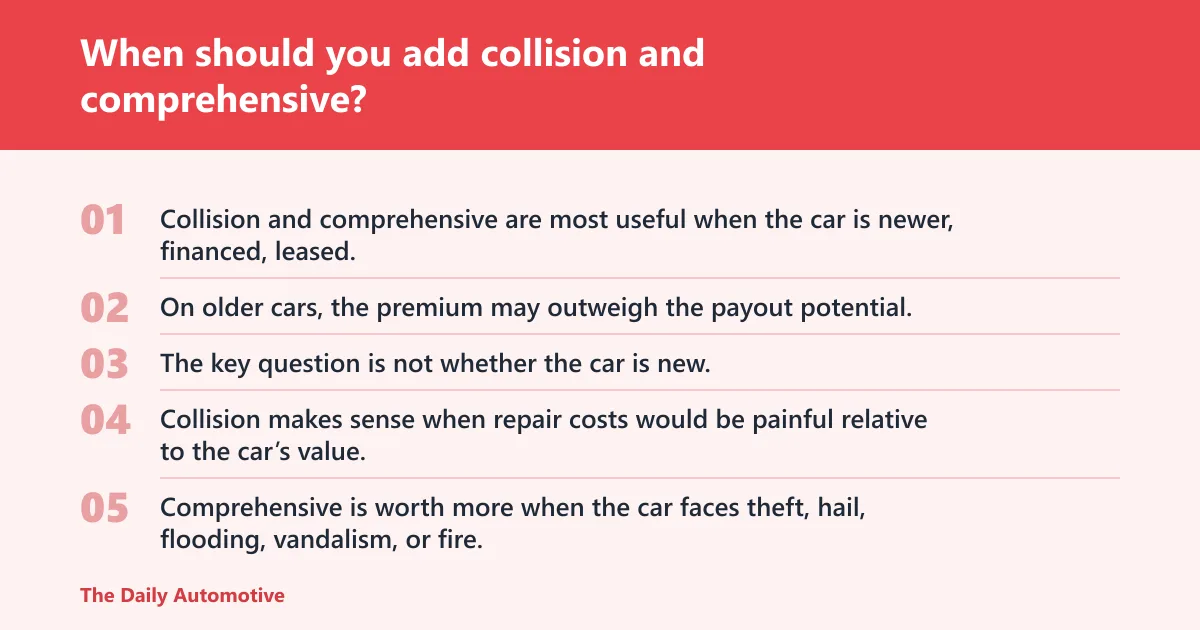
Collision and comprehensive are most useful when the car is newer, financed, leased, or still valuable enough that a major repair would hurt. On older cars, the premium may outweigh the payout potential. The key question is not whether the car is new. It is what would be lost in a claim.
Older car versus newer car decision points
Collision makes sense when repair costs would be painful relative to the car’s value. Comprehensive is worth more when the car faces theft, hail, flooding, vandalism, or fire. For an aging car with low market value, those coverages may become poor math if the premium and deductible eat most of the likely payout.
How parking, weather, and theft risk change the call
Street parking, apartment lots, and high-theft areas raise the value of comprehensive coverage. So do hail zones, flood-prone neighborhoods, and places where break-ins are common. A vehicle kept in a locked garage faces a different risk profile than one left outside on a busy block.
Say your sedan is parked outdoors near a train station and used for a 40-mile round trip each weekday. A windshield crack, catalytic-converter theft, or hail loss is more plausible than for a weekend car. Comprehensive coverage is often easier to justify in that setting than on a low-mileage spare vehicle.
When coverage may cost more than the car is worth
If the car’s actual cash value is modest, collision and comprehensive may not be worth carrying at every deductible level. Compare what the policy could pay after a claim with the annual premium plus deductible. If that number is not compelling, you may be paying too much for too little return.
Which coverages matter most in heavy traffic?
Heavy traffic raises the value of uninsured motorist coverage, solid liability limits, and strong medical protection if your policy offers it. Dense commuting means more stop-and-go crashes, more hit-and-run risk, and more chances that another driver lacks enough insurance to cover the damage.
Uninsured motorist coverage as a daily-driver safeguard
Uninsured motorist coverage protects you when the at-fault driver has no insurance. In crowded metro areas, that matters because your odds of meeting a weakly insured or uninsured driver are not the same as they are on a rural weekend route. It can fill important medical and property gaps.
Medical and property protection gaps to watch
A liability-only policy may leave your own injuries and car damage exposed if someone else has no coverage or vanishes after a hit-and-run. Even when another driver is at fault, collecting can be slow or uncertain. Stronger uninsured motorist limits reduce the chance that you absorb the loss yourself.
Why dense commuting raises the value of certain limits
Frequent lane changes, tight merges, and more bumper-to-bumper miles create more claim opportunities. That does not mean every commuter needs every add-on. It does mean that daily urban driving should push you toward higher liability limits and uninsured motorist coverage before you spend on lesser priorities.
How do deductibles and savings work together?
Higher deductibles usually lower premiums, but only if you can pay the deductible after a claim without damaging your budget. The right number depends on emergency savings, cash flow, and how likely you are to file a claim. A low premium is not a win if the deductible becomes a crisis.
The premium and deductible tradeoff
Raising a deductible shifts more loss to you. Lowering it shifts more of the upfront cost to the insurer. That tradeoff works only when your savings can absorb the deductible on short notice. For daily drivers, the repair is often less of a problem than the cash timing.
A deductible range by savings buffer
- Under one month of emergency savings: favor a lower deductible, often around the low end of what the insurer offers.
- One to three months of emergency savings: a midrange deductible can make sense if the monthly premium drop is meaningful.
- More than three months of emergency savings: a higher deductible may be acceptable if it materially lowers the premium and fits the car’s value.
These are decision ranges, not rules. The right deductible is the one you can pay after a claim without needing to raid rent money, credit cards, or retirement accounts.
What to avoid if a claim would strain cash flow
Do not pick a high deductible just to trim the bill if a repair would force debt or missed bills. That is especially risky for daily drivers, because the same car may be needed to work, commute, and handle family duties. A saved premium is not useful if the claim stalls your whole schedule.
Decision matrix: match coverage to your driving profile
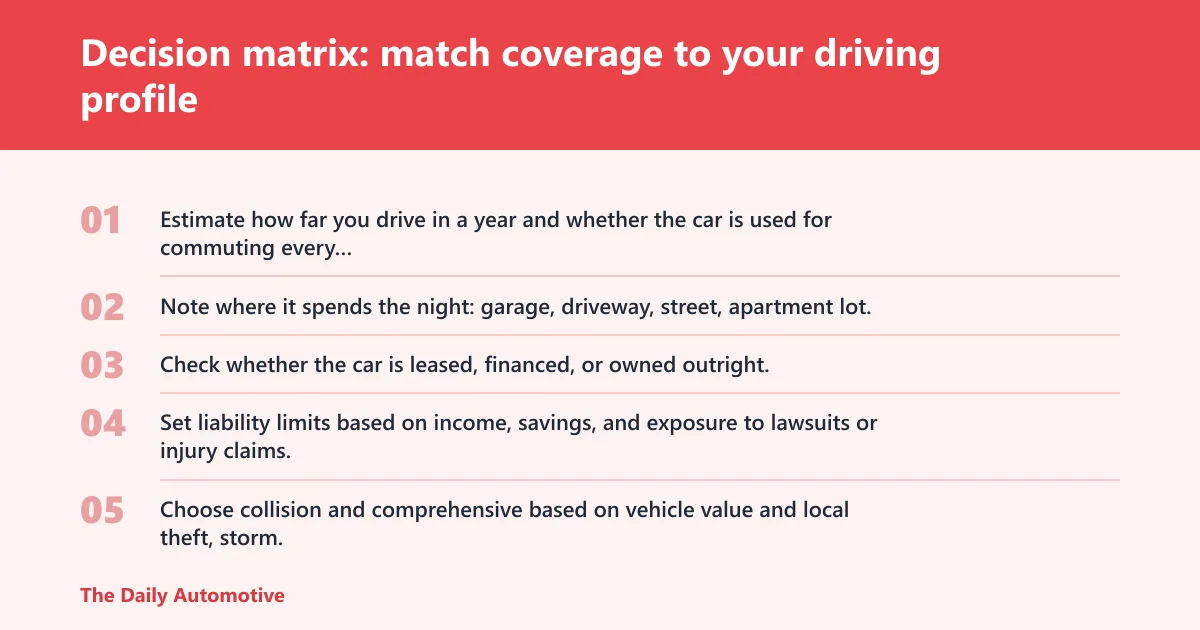
Use mileage, parking, financing, and savings together. A car driven every weekday in a city has a different insurance profile from a garage-kept car used for short suburban trips. The best policy follows the exposure, not the calendar age of the vehicle.
| Driver profile | Annual mileage | Parking environment | Financing or lease status | Savings buffer | Coverage priorities | Deductible range |
|---|---|---|---|---|---|---|
| City commuter, heavy traffic | 12,000+ miles | Street or public lot | Owned outright | 1 to 2 months of expenses | Higher liability limits, uninsured motorist, comprehensive | $500 to $1,000 |
| Financed daily driver, newer car | 10,000 to 15,000 miles | Garage or secure lot | Financed | 2 to 4 months of expenses | Liability, collision, comprehensive, gap insurance | $500 |
| Leased vehicle, long commute | 15,000+ miles | Mixed parking | Leased | 2 to 3 months of expenses | Liability, collision, comprehensive, gap insurance, uninsured motorist | $500 |
| Older paid-off car, short suburban trips | 6,000 to 9,000 miles | Garage | Owned outright | 3+ months of expenses | Higher liability limits, uninsured motorist, selective collision/comprehensive | $750 to $1,500 |
| High-value car, street parked | 8,000 to 12,000 miles | Street or apartment lot | Owned outright or financed | 3+ months of expenses | High liability limits, collision, comprehensive, uninsured motorist | $500 to $1,000 |
- Estimate how far you drive in a year and whether the car is used for commuting every weekday.
- Note where it spends the night: garage, driveway, street, apartment lot, or secured facility.
- Check whether the car is leased, financed, or owned outright.
- Set liability limits based on income, savings, and exposure to lawsuits or injury claims.
- Choose collision and comprehensive based on vehicle value and local theft, storm, or parking risk.
- Pick a deductible you can pay from savings without creating credit-card debt.
- Recheck the policy after a move, a new loan, or a big change in commute length.
What discounts are worth chasing?
Discounts matter, but only after the policy has enough protection. Bundling, telematics, and clean-record discounts can trim the bill. They should not push you into weak limits or remove coverage you would need after a bad commute, storm loss, or uninsured-driver claim.
Bundling auto with home or renters insurance
Bundling car insurance with home or renters insurance can lower total cost. That is useful for a daily driver, especially when a household already needs multiple policies. But a bundle is only good if both policies still fit the risk. A cheap bundle with weak auto coverage is still weak coverage.
Usage-based insurance and telematics
Usage-based insurance can reward predictable, lower-risk driving patterns. It often works best for drivers with steady mileage, calmer acceleration, and fewer late-night miles. It can also penalize hard braking, night driving, or heavy use, so read the rules before opting in.
Safe-driver and mileage-related savings
Clean records can help lower premiums, and lower mileage can matter too. Those savings are real, but they are secondary to limits, deductibles, and the insurer’s claim handling. A discount is useful only after the policy still covers the loss you could actually face.
How do I compare car insurance providers without overpaying?
Compare more than price. Look at policy limits, deductible choices, exclusions, discount rules, telematics terms, and claims service or customer service ratings. A cheaper quote can cost more later if the company is hard to reach, slow to pay, or thin on coverage options.
Comparison checklist for quote shopping
- Match liability limits, collision, comprehensive, and uninsured motorist coverage across every quote.
- Check deductibles side by side and confirm you can afford the amount after a loss.
- Review exclusions and usage rules, especially for telematics and work-related driving.
- Ask how bundling, safe-driver, and mileage discounts change the final price.
- Check claims service and customer service ratings, not only the premium.
- Requote after major changes such as a move, a loan payoff, or a new commute.
Frequently asked questions
What insurance coverage do I need if I drive every day?
Start with liability limits that fit your income and assets, then add uninsured motorist coverage if you drive in dense traffic. For newer, financed, or leased cars, collision and comprehensive usually deserve a closer look. Daily use raises exposure, so weak limits can become expensive quickly.
Is state-minimum car insurance enough for a daily driver?
State minimums may satisfy the law, but they often do not protect a commuter well. Frequent driving raises the odds of a claim, and a serious crash can exceed low liability limits. If your paycheck, savings, or car value would hurt from a loss, minimum coverage is thin.
When does gap insurance make sense for a financed car?
Gap insurance matters when a loan or lease balance can stay above the car’s value after depreciation. That gap is most relevant early in ownership and on vehicles that lose value quickly. If a total loss would leave you owing more than the insurer pays, gap coverage helps close that hole.
How do deductibles affect monthly car insurance premiums?
A higher deductible usually lowers the monthly premium because you agree to pay more after a claim. That only works if the deductible is realistic for your savings. If a repair would strain cash flow, a low premium is not a good trade for a painful out-of-pocket bill later.
Which discounts can lower car insurance for high-mileage drivers?
High-mileage drivers may still qualify for bundling, safe-driver, or telematics discounts, though usage-based programs can penalize heavy use or hard braking. The biggest savings should come after the policy is built correctly. A discount is helpful, but it should never replace strong liability limits or proper deductibles.
Should I choose collision and comprehensive coverage for an older car?
Sometimes, but not always. On an older paid-off car, compare the premium plus deductible against the car’s value and the likely claim payout. If the vehicle is worth little and the premium is high, those coverages may not pay back enough. Parking risk and storm risk can still change that call.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.