Does Car Insurance Cover Rodent Damage? What to Know
Yes, comprehensive car insurance is one policy that may pay for rodent-chewed wiring, nesting debris, and related interior damage. Liability and collision usually do not pay for that loss. If you wait to document it or start repairs first, an adjuster may deny parts of the claim. This guide explains what insurers approve, what they exclude, and how to prove the damage before repair work begins.
Short answer on cover
Comprehensive car insurance may cover rodent damage, but only when the policy wording leaves room for it. The key issue is usually whether the policy excludes vermin, pests, insects, rodents, or animal damage. If that exclusion is present, the claim may stop there.
The Product Disclosure Statement is the controlling document. It lists the inclusions, exclusions, and definitions the insurer will use during claim assessment. In Australia, wording varies across insurers, so do not assume one brand’s treatment applies to another.
Home insurance is a different contract. Even where a rodent problem started on your property, that does not make a house policy the payer for vehicle repairs.
Does car insurance cover rodent damage?
Sometimes, yes. Car insurers often look first at comprehensive cover, then at the exclusion list. If the damage is treated as accidental loss and the policy does not bar vermin or animal-related damage, the claim may be considered. If the wording treats rodent damage as preventable or foreseeable, the insurer may refuse it.
How insurers usually treat vermin and pest damage
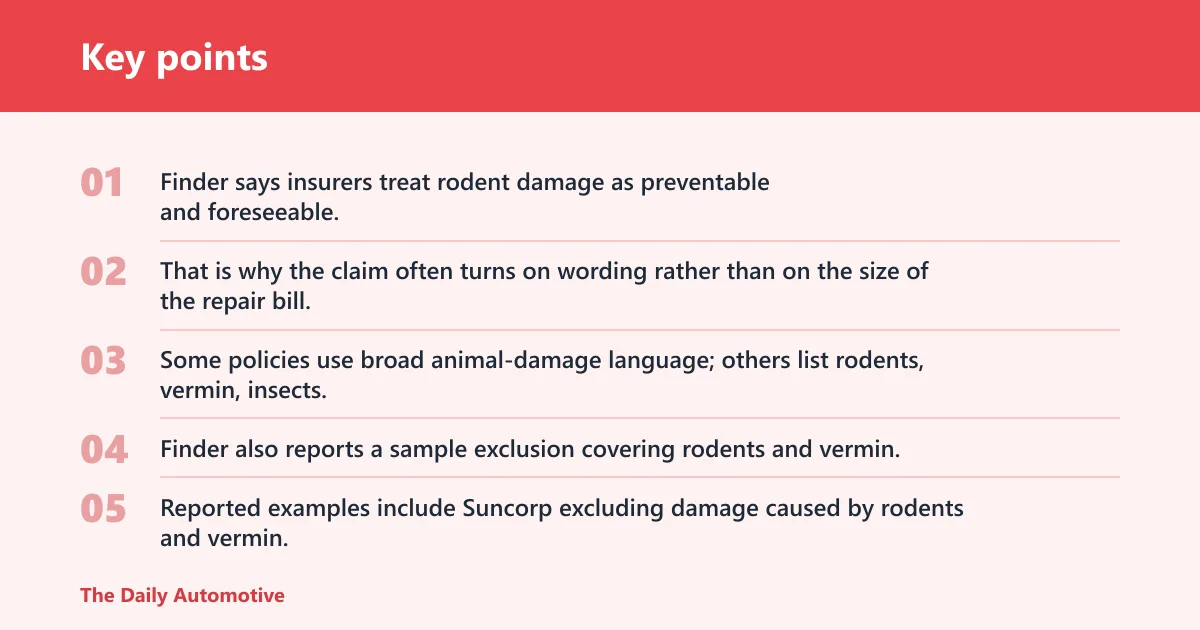
Finder says insurers treat rodent damage as preventable and foreseeable, and that it is usually listed in policy exclusions. That is why the claim often turns on wording rather than on the size of the repair bill. Some policies use broad animal-damage language; others list rodents, vermin, insects, or pests directly.
Finder also reports a sample exclusion covering rodents and vermin, plus insurer wording that excludes damage caused by rodents and vermin. Reported examples include Suncorp excluding damage caused by rodents and vermin, Budget Direct using an exclusion for rodents and vermin, Youi not covering loss or damage caused by vermin, AAMI potentially excluding damage caused by insects, vermin, or rodents, and NRMA excluding loss caused by rats, mice, vermin, insects, termites, bats, or possums.
Direct damage versus resulting electrical faults
Insurers may separate the chewed wire from the problem that shows up later. A damaged harness, shredded insulation, or debris from a nest is one issue. A warning light, no-start condition, or intermittent sensor fault that appears afterward may be treated as a result of the rodent damage, but only if the link can be shown.
Suppose a mouse chews through the wiring near the airbox and the car later throws a charging-system warning. That does not automatically make the warning payable. The insurer may ask whether the wiring damage caused the fault, or whether the fault was already present and only discovered during the inspection.
Why preventable damage is often disputed
Even when the damage is obvious, some insurers treat infestation-related losses as avoidable with ordinary care. That is why they may point to housekeeping, parking conditions, or long-term storage. The policy wording matters more than the general idea of fault. If the exclusion is broad, the claim may fail even when the wiring is clearly damaged.
What your policy wording should say
Start with the Product Disclosure Statement, not the marketing summary. The PDS should tell you what is covered, what is excluded, and how the insurer defines animal, pest, or vermin damage. If the wording is unclear, the claims team will still rely on the PDS, not a brochure headline.
Where exclusions are usually listed
Look in the general exclusions section first, then any specific exclusion for vermin, rodents, insects, pests, or animal damage. Some policies use a separate list of excluded events. Others bury the wording inside a broader “what we do not cover” section. Either way, that clause often decides the claim.
Terms to search for in the wording
- Vermin
- Rodents
- Pests
- Insects
- Animal damage
- General exclusions
- Loss caused by
- Damage caused by
What insurers may pay
Insurers may review the full damage path, not just the obvious bite marks. Chewed wiring is the clearest claim item when it is visible and documented. Cabin insulation, nesting material, air filters, and hoses can also come into play if the policy wording allows rodent damage and the repair need is directly tied to the incident.
Chewed wiring
This is often a core issue in vehicle claims. The insurer will want proof that rodents physically damaged the harness, connector, or insulation. Photos of exposed copper, gnawed sheathing, or debris near the wiring help. A repair invoice that identifies the affected circuit is stronger than a general “electrical fault” description.
Cabin insulation and nesting debris
Nesting material in the dash, under seats, or behind trim may be included if the policy covers the event and the cleanup is part of restoring the vehicle. A blocked blower path, shredded sound-deadening material, or contaminated insulation can matter when the inspection shows a direct link to rodent activity.
Air filters, hoses, and secondary electrical faults
Chewed intake hoses, clogged cabin filters, and damaged vacuum lines can be part of the claim if they were directly damaged by rodents. Secondary electrical faults are harder. Insurers often want an inspection that ties the later failure to the rodent damage rather than to wear, age, or a pre-existing defect.
Picture a car that sat in a driveway for two weeks, then develops a dead blower motor and a nest behind the glovebox. The claim question is not whether rodents were present; it is whether the policy covers that kind of damage and whether the failed part can be linked to the chewing or debris.
Rodent damage checklist
Use this checklist before you authorize repairs. It helps you separate what is likely payable from what may draw an exclusion. Keep the wording, photos, and repair notes together so the adjuster can trace the claim quickly.
| Damage type | Likely policy wording trigger | Evidence to gather | Claim risk level |
|---|---|---|---|
| Chewed wiring | Accidental damage or animal-related damage, unless vermin or rodents are excluded | Close-up photos, repair estimate, damaged harness or connector, inspection notes | Medium to high |
| Cabin insulation | Comprehensive cover with no pest exclusion for interior damage | Photos of torn insulation, interior trim removal notes, cleanup invoice | Medium |
| Air filters | Direct rodent damage to intake or cabin components | Photo of nesting debris, removed filter, mechanic’s report | Medium |
| Nesting debris | Cleanup covered under direct loss, if not barred by vermin language | Photos before removal, towing record, labor invoice | Medium |
| Secondary electrical faults | Resulting damage accepted only if linked to the rodent incident | Diagnostic scan, fault codes, technician explanation, timeline of symptoms | High |
How to file the claim
Move quickly, but do not rush past documentation. Photograph the damage, report it, and wait for the insurer’s inspection instructions before authorizing repairs. Keep towing receipts, diagnostic notes, and every invoice that follows the loss.
- Photograph the damage from several angles before anything is removed.
- Note when the problem was first noticed and any warning lights or failures.
- Contact the insurer promptly and ask whether an inspection is required.
- Do not authorize repairs unless the insurer says you can or must.
- Keep towing, diagnosis, and repair invoices in one file.
Answers.com includes a user report that State Farm said it would cover auto rodent damage, but that is only an example of insurer-specific handling. It is not a universal rule. The same source also says the vehicle should not be repaired before an adjuster review, which fits the general claims process used by many insurers.
Does car insurance cover rodent damage in Australia, the UK, and the US?
It can, but the market and wording are not interchangeable. Australia commonly uses comprehensive car insurance and a Product Disclosure Statement. The UK often uses comprehensive motor insurance with similar exclusion language. In the US, comprehensive auto cover is also the usual starting point, but each insurer writes its own animal-damage language.
Why market terminology differs
Local terms can point to the same idea, but the details are not identical. A policy that says “vermin” in Australia may use different wording in the UK or US. That is why you should compare the actual exclusion clause, not the label on the front page.
How to compare local wording carefully
Look for the same three things everywhere: the comprehensive section, the exclusion list, and the definition of covered loss. Then check whether rodents, pests, insects, vermin, or animal damage are mentioned. If they are, that language may shut the claim even when the damage is real.
Does home insurance cover rodent damage to a car?
Usually no. A home policy generally will not pay for vehicle repairs, even if the rodent problem began on your property. The same source states rodent damage is not covered by home insurance, and that insurers treat it as preventable and foreseeable. For a car claim, the auto policy usually decides the result.
When a property policy may still matter
A property policy may matter for a garage, driveway structure, or contents inside the home. It is not the normal route for vehicle wiring, trim, or engine-bay repairs. If the same infestation damaged both the house and the car, each claim still needs its own policy review.
Frequently asked questions
Will comprehensive insurance cover rodent-chewed wires?
Often it can, but only when the policy wording allows animal-related loss and does not bar rodent or vermin damage. Insurers usually want visible proof of chewing, a repair estimate, and an inspection if needed. If the car is repaired first, part of the claim may be harder to prove.
How do I know if rodent damage is excluded from my policy?
Read the exclusions section of the Product Disclosure Statement. Search for vermin, rodents, pests, insects, animal damage, and general exclusions. If those terms appear, the insurer may rely on them to deny the claim. Do not depend on the summary page alone; the PDS controls.
What kind of car insurance covers rodent damage?
Comprehensive car insurance is the main policy type to check. Third party property damage policies usually do not cover your own vehicle’s wiring or interior losses. Even with comprehensive cover, the exclusion wording can still block payment if the insurer lists vermin, rodents, or pests.
Does insurance cover rodent damage?
Sometimes, but the answer depends on which policy you mean. Home insurance often excludes rodent damage, while auto comprehensive cover may consider it if the wording allows. The key question is not whether rodents caused harm, but whether the contract excludes that kind of loss.
Does car insurance cover rodent damage in Australia?
It can, mainly under comprehensive car insurance, but Australian policies vary widely. The PDS is the source that matters. Find the exclusions and look for vermin, rodents, pests, insects, or animal damage. If those terms appear, the insurer may deny all or part of the claim.
Does car insurance cover rodent damage uk?
It may under comprehensive motor insurance, but UK wording can differ from Australian and US policies. The same claim can turn on a pest, vermin, or animal-damage exclusion. Check the policy booklet and claims wording before starting repairs, because the insurer will rely on that text.
Does homeowners insurance cover rodent damage to a car?
Usually not. A homeowners policy generally covers the house and contents, not vehicle repairs. Even if the infestation started in a garage or driveway area, the car claim is usually handled under the auto policy. Check both policies only if the same incident also damaged a covered structure.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.