Can You Claim Hail Damage Twice on a Car? What to Know
Yes, you can file a second hail claim on the same car if the new storm caused separate damage, but insurers usually deny dents that were already there, unrepaired, or tied to the first loss. Miss the deadline or the documentation, and you may pay a deductible for damage that is not covered twice. This guide explains when a second hail event is a new claim, what proof insurers look for, and when filing is worth it.
Can you file a second hail claim?
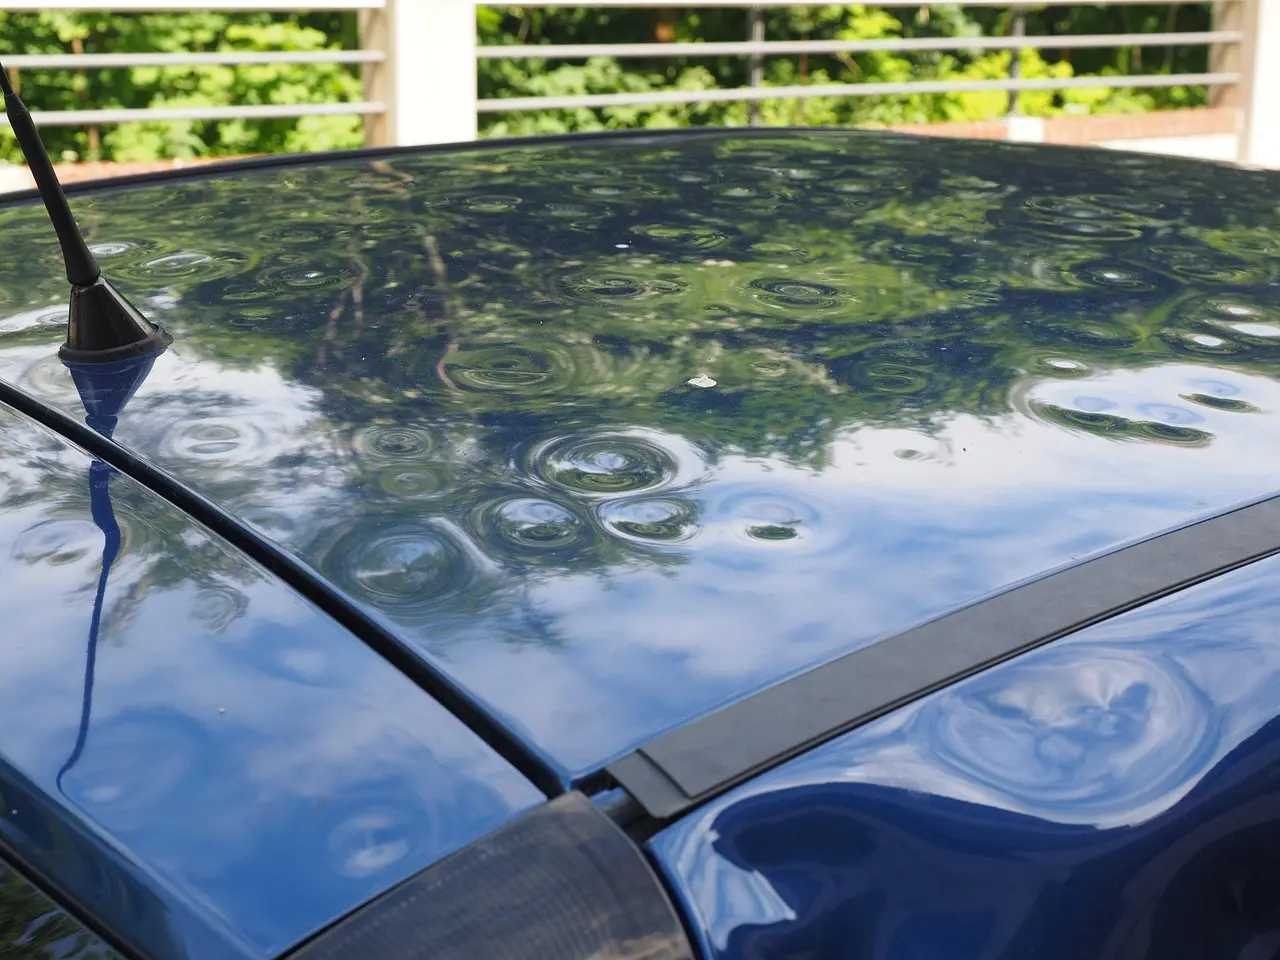
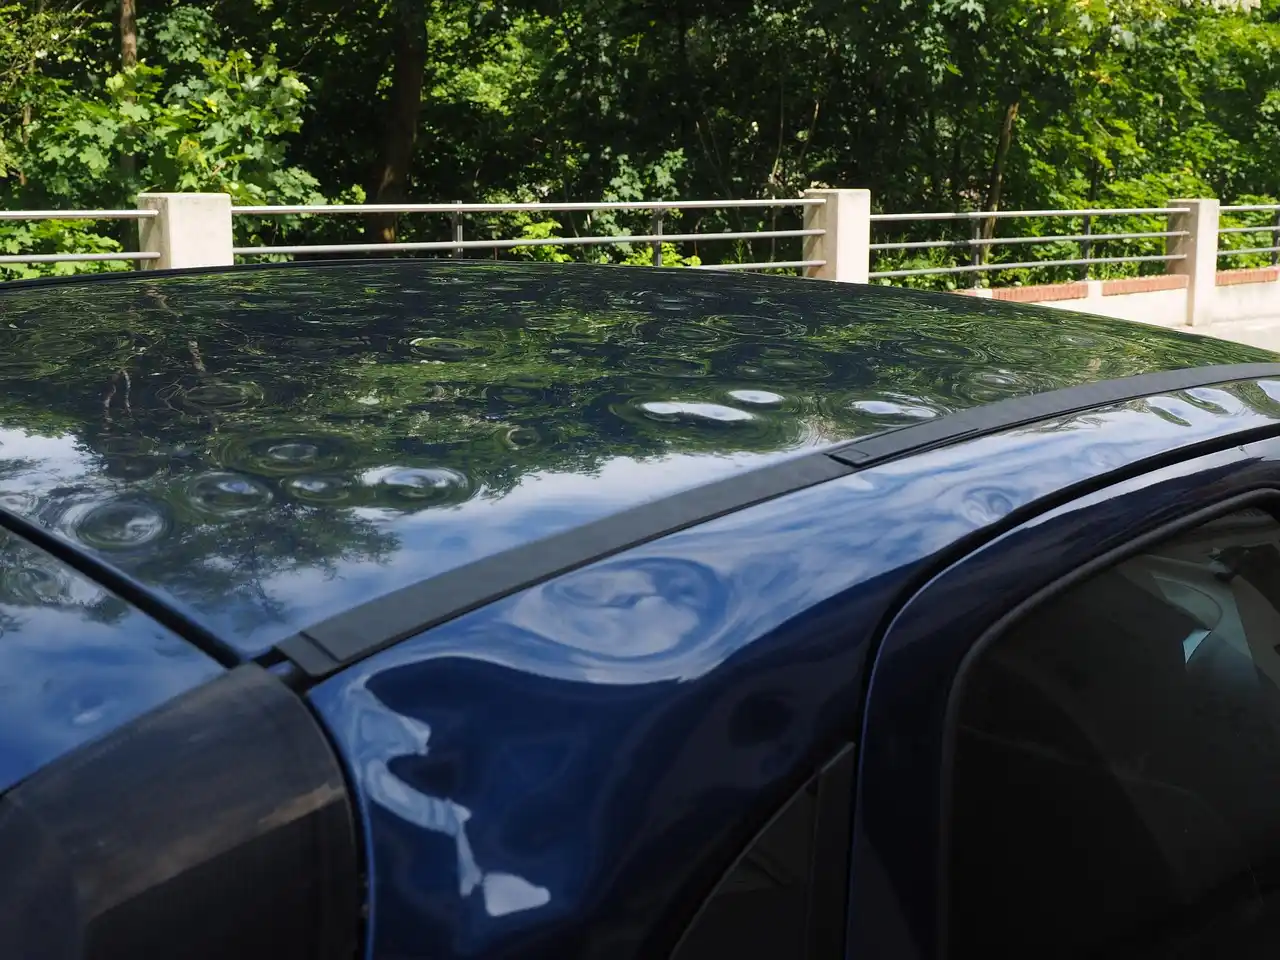
A second hailstorm can count as a separate covered loss when it has its own date, time, and location. Two separate hailstorms are normally treated as two separate losses, and insurers may open two claims for hail damage. The question is not whether the car has dents. It is whether those dents belong to the later storm.
That distinction matters because the first open claim covers the damage documented at that time, and a new storm is generally a new claim. An insurance adjuster will compare current dents with prior damage and decide whether the newer marks can be tied to a later event. If they cannot, the insurer may treat the dents as pre-existing.
What makes the same dents ineligible for another payment
Insurance does not pay twice for the same covered loss. If the second file is only a repeat request for damage already listed on the first claim, the carrier can limit payment or deny the overlap. That is why claim timing, inspection notes, and repair status matter as much as the visible dents themselves.
Say your roof and hood were dented in a storm on Monday, and the adjuster documented those panels that day. If a second storm hits Friday and leaves new dents on the roof edge and doors, the insurer may treat the Friday damage as a separate loss if you can show the dates and locations clearly.
Comprehensive coverage and deductibles
Comprehensive coverage is the policy section that usually pays for hail damage. If the car only has liability coverage, hail damage is typically not covered. A separate comprehensive deductible may apply to each claim, so a second hail claim can mean a second deductible if the insurer accepts it as a new loss.
That deductible can make a second claim expensive. If the deductible is near the repair estimate, filing may not be worthwhile. Compare what you would pay out of pocket with the likely repair bill for the new damage.
When the deductible can outweigh the claim
Hail repair is often priced panel by panel, and the estimate can include the hood, roof, doors, moldings, trim, and other operations. If the damage is light, the repair estimate may stay below or only slightly above the deductible. In that case, a second claim may bring little financial benefit.
A common first-timer mistake is filing without checking the second estimate first. If the new damage looks minor and the deductible is substantial, the claim may cost more than it pays. The insurer still reviews the loss, and the deductible still applies if the claim is covered.
Second hail claim checklist
This checklist shows how claim status changes the evidence burden. It also shows why the insurer’s questions shift from “what happened?” to “what changed since the first storm?”
| Claim status after storm one | What evidence to gather | Likely insurer question | Recommended next step |
|---|---|---|---|
| No first claim filed | Photos, videos, storm date and time, weather report, inspection history | Can the second storm be tied to the damage you are reporting now? | File promptly and document the later event clearly |
| Open first claim | Prior estimate, adjuster notes, current photos, new storm records | Which dents were already documented on the open file? | Tell the insurer about the second storm and request a reinspection |
| Repaired first loss | Repair order, completion photos, invoice, before-and-after images | Did the repaired panels show new hail after completion? | Show the repair record and the later storm evidence together |
| Cash settlement accepted | Settlement letter, estimate, unspent repair funds status, new storm evidence | Was the earlier claim resolved, and is this damage separate? | Separate the old loss from the newer one in your file |
| First loss never repaired but claim closed | Closed claim file, photos, weather records, panel-by-panel comparison | Which dents were old, and which are clearly new? | Expect a stricter review and stronger proof of timing |
| Cost comparison | Deductible versus likely repair-cost range | Will the new damage exceed the deductible by enough to matter? | File only if the second estimate justifies the deductible |
Read the checklist the right way
The first column carries the most weight. Insurers treat an open first claim, a repaired first loss, a cash settlement, and a closed but unrepaired claim differently. The file may be paid, partly paid, reopened for review, or denied if the new dents cannot be separated from the old ones.
If the first loss was never repaired, the baseline dispute risk is higher. Previous unrepaired hail damage can make it harder to prove that later dents came from a new storm. Stronger documentation matters more in that setting because the adjuster needs a cleaner before-and-after comparison.
What proof insurers want
Proof of loss should show what the car looked like before and after each storm. Insurers want photos and videos, storm date and time, weather reports, and any prior estimate or repair record. Keep photographs and documents in their original form if possible, because timestamps and file details can help confirm when the damage was recorded.
Documentation that helps most
- Photos of the car before the second storm, if available.
- Photos and video after the second storm, taken as soon as possible.
- The date, time, and location of each hail event.
- Weather reports showing hail in your area on those dates.
- The first estimate, supplement, repair order, or settlement letter.
- Any inspection notes from the first claim.
Suppose the first storm hit a parked car at home and the second one struck at work three days later. If you have timestamped photos from both locations, plus weather reports for both dates, the insurer has a better way to separate the losses. Without that paper trail, the claim can turn into a dispute over whether the dents were already there.
How adjusters separate old dents from new damage
An insurance adjuster compares current dents with the prior loss record and looks for what changed. The estimate is built panel by panel, and estimators consider the number and size of dents on each panel. Hail damage is evaluated panel by panel on major body parts, so the roof, hood, and doors often get the closest review.
Estimating systems may also sort dents by coin-size categories such as dime, nickel, quarter, or half-dollar. That does not settle the claim by itself, but it helps the adjuster describe the severity and spread of damage. If a panel already had a documented pattern of dents, the later file must show what is new.
Why unrepaired hail complicates attribution
Previous unrepaired hail damage creates a baseline dispute risk. The insurer may ask which dents existed before the second storm and which ones did not. If the first claim was open, the file should already contain damage documented at that time, which can help define the earlier baseline and narrow the dispute.
Panels that were untouched after storm one are often the hardest to sort out. If a roof had older dents and the second storm hit the same roof again, the adjuster may still pay the new loss, but only if the evidence separates the later damage from the earlier marks.
When a second claim may not be worth it
The deductible versus likely repair cost is the main financial check. If the second hail damage is small, paying a deductible for the new claim may not make sense. That is especially true when the estimate is close to the deductible or when the damage is limited to a few minor dents.
Paintless dent repair is a common hail repair method for minor to moderate dents, and it often preserves factory paint. Because PDR is often less expensive than conventional bodywork, the second estimate may still come in below the point where filing helps. Check the cost before you file, not after.
Total loss can enter the picture
A total loss threshold can become relevant when hail repair costs approach or exceed vehicle value. That cutoff varies by insurer and state. If the damage is severe enough, the carrier may consider whether repair costs make economic sense, rather than simply approving a routine dent repair.
Hail can also reduce resale value in the Oklahoma market, which is one reason repeated hail claims deserve a careful review. That does not mean every second claim is a problem. It does mean repeated comprehensive claims may receive closer underwriting attention later, depending on the insurer.
PDR and total loss basics
Paintless dent repair is the usual starting point for minor to moderate hail damage because it can remove dents without repainting the panel. Repaired PDR can restore a vehicle so no sign that damage occurred remains. That is useful when the paint is intact and the metal can be massaged back into shape.
Once paint is broken, PDR may no longer be enough for that panel. The adjuster then has to decide whether the repair scope includes conventional bodywork, replacement parts, or a different solution. Hail estimates may include hood, roof, doors, moldings, trim, and other operations, so the final number can climb quickly on a heavily damaged car.
Why factory paint matters
Factory paint is one reason PDR is preferred when possible. Preserving the original finish usually keeps the repair simpler and less invasive. If the second hail event affects panels that were already repaired, the insurer will likely want proof that the repaired work was completed before the later storm.
That is another reason to keep every repair record. A closed claim with a completed repair is easier to separate from new damage than a closed claim with no repair record at all.
Frequently asked questions
Can you claim hail damage twice on the same car?
Yes, if there were two separate hailstorms and the second one caused new damage. You generally cannot collect twice for the same dents. The insurer will compare the current loss against the first file, so the date, location, and documentation for each storm are what make the second claim possible.
What happens if your car gets hit by hail again before you repair it?
The second storm can still be a new claim, but the review gets harder because the car already had unrepaired hail damage. The insurer will try to separate old dents from new ones. Strong photos, weather records, and the first estimate become much more important when the car was never repaired.
Do you need a new insurance claim for each hailstorm?
If each hailstorm is a distinct loss, yes, a new claim is usually needed. Two separate hailstorms are normally treated as two separate losses, and the insurer may open two claims. If the second event only repeats damage already documented, the company may fold it into the first file or deny overlap.
Will insurance deny a second hail claim if the first one is still open?
Not automatically. An open first claim can still be followed by a second claim if the later storm caused additional damage. The insurer will use the open file as the baseline for the first loss, then inspect the car again to see what changed after the second event.
Do you have to pay your comprehensive deductible twice for hail damage?
Often yes, if both hailstorms are covered as separate losses. A separate comprehensive deductible may apply to each claim. That is why the second claim should be compared against the repair estimate first. If the new damage is small, the deductible may take most of the payment.
What proof do insurers want for a second hail damage claim?
They usually want photos, videos, storm date and time, weather reports, and any prior estimate or repair record. Timestamped evidence is especially helpful if the first claim is open or the car was never repaired. The clearer the split between the two storms, the smoother the claim review tends to be.
Can hail damage be claimed if the same panels were already dented before?
Yes, but only the new damage should be claimed. If the same panels were already dented, the adjuster will compare the old and new conditions panel by panel. Previous unrepaired hail damage creates baseline dispute risk, so the second claim needs stronger proof that the later storm added new dents.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.