Does Car Insurance Go Down at 25? The Real Answer, with Numbers
Usually, car insurance gets cheaper at 25, but the drop is often modest if nothing else changes, around 5% to 15% at the next renewal rather than a full reset. Miss the renewal timing or carry a ticket, crash claim, or coverage change, and the age drop can disappear. This guide shows when the cut appears, what blocks it, and how to tell whether 25 will actually lower your bill.
Quick answer
Usually, yes. In many pricing models, age 25 moves you out of the youngest-driver tier, so the premium often falls at the next renewal if your record and coverage stay stable. It does not drop because of the birthday itself. The insurer recalculates the rate when the policy renews.
One widely cited benchmark puts the average 25-year-old premium at $146 per month, with the average 24-to-25 decrease at $21 per month. Another dataset pegs the average 25-year-old at $1,752 annually and says a 24-year-old average sits around $3,597 in a different full-coverage comparison. The exact numbers vary because the vehicle, state, and coverage setup vary.
That is also why 25 is not always the biggest age break. Insurers often pull the steepest age-based reductions earlier, especially around 21, when the risk profile changes more sharply.
How much does it drop at 25?
The short answer is: enough to notice, but often not enough to transform the bill. InsureMojo says the national average decrease from 24 to 25 is 11%, and MoneyGeek cites an average $21 per month drop. For a driver paying several hundred dollars a month, that is meaningful. For a driver with another surcharge, it can be lost in the noise.
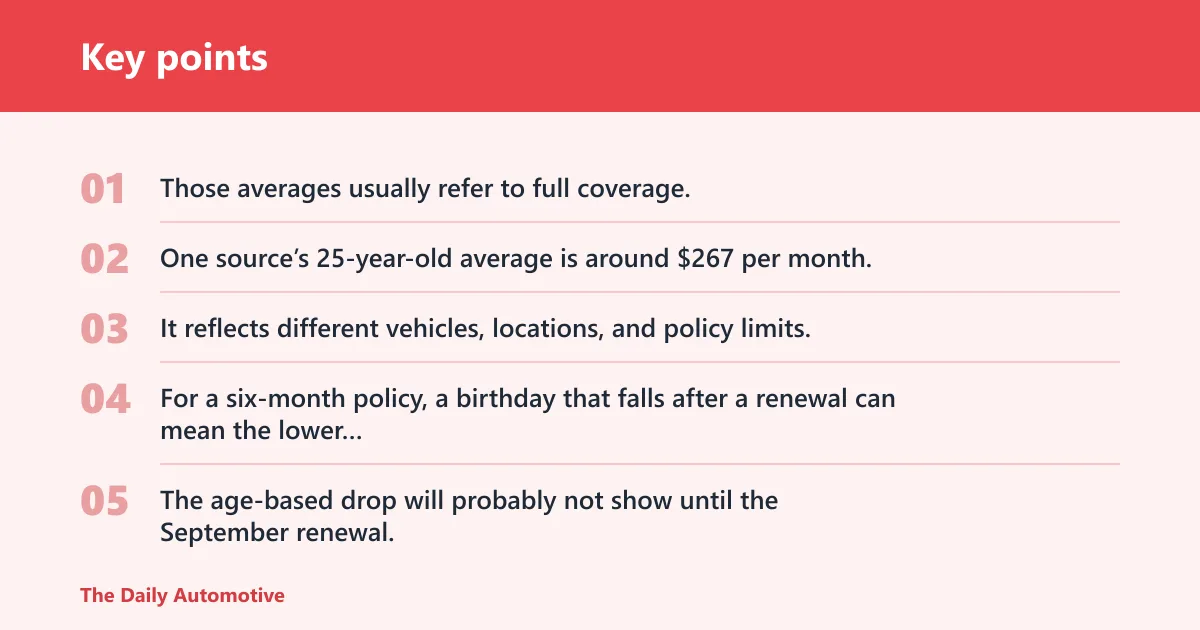
Those averages usually refer to full coverage, which is the benchmark most ranking pages use. One source’s 25-year-old average is around $267 per month, while another cites $146 per month. That spread is not a contradiction. It reflects different vehicles, locations, and policy limits.
Age-25 savings reality check
| Scenario | Expected direction of change | What factor controls it | Will the age-25 discount likely appear? |
|---|---|---|---|
| Clean record on renewal | Down | Age tier changes at the renewal date | Yes, this is the clearest case |
| Birthday after renewal | Flat until the next term | Policy term length and renewal timing | Yes, but delayed for months |
| Recent speeding ticket | Small drop, flat rate, or slight increase | Ticket surcharge and insurer formula | Maybe, but the ticket can hide it |
| Recent DUI | Up sharply or stay elevated | DUI surcharge, risk tier, and state rules | Unlikely to be visible |
For a six-month policy, a birthday that falls after a renewal can mean the lower 25-year-old rate may not appear until the next renewal. The age-based drop will probably not show until the September renewal, because the carrier usually prices the next term using the age you are at renewal. That means the “25 savings” can arrive five months late.
Suppose a driver pays $260 a month at 24 on a full-coverage policy. If a carrier mirrors the common average $21 monthly reduction, the bill might fall to about $239 at renewal. But a single speeding-ticket surcharge or a different vehicle factor can wipe out that change completely.
Does car insurance change on your 25th birthday or at renewal?
At renewal. That is the rule that matters. Six-month and twelve-month policies are common, so the insurer normally updates the rate when a new term starts, not the day you turn 25. If the birthday falls right after a renewal, the lower age tier may not show up for months.
This timing issue is why two drivers with the same birthday can see different results. One renews the week after the birthday and gets the lower price almost immediately. Another renewed two months earlier and waits until the next cycle. The age change is real in both cases, but the timing changes the date you see it.
- Check your policy expiration date first.
- Compare your current term to the next renewal window.
- Ask whether the company updates age-based pricing at renewal only.
- Quote the same coverage limits before switching carriers.
Why your rate may not fall much at 25
Age is only one part of the rate. A recent violation, a claim, poor credit-based insurance score, state limits on age rating, or a different car can all swamp the age effect. If any of those changed, the “25 discount” may be too small to notice.
Driving record can cancel the age cut
A speeding ticket can matter more than turning 25. MoneyGeek says a speeding ticket raises premiums by 22%, and a DUI adds 93%. Either one can more than erase a modest age-based decline. Recent at-fault crashes can also keep rates high for multiple renewal cycles, depending on the carrier and state.
Violations stay on record for years in many pricing systems, so the insurance company can still charge for the risk long after the court case is over. That is why a “clean 25-year-old” and a “25-year-old with a recent ticket” are not remotely the same pricing profile.
Credit-based insurance scores matter in most states
Most states let insurers use credit-based insurance scores, and those scores can change the final premium. Better credit can add to the age-25 savings. Poor credit can flatten it or hide it entirely. California and Massachusetts limit age-based pricing, so state rules can narrow the age effect before credit is even considered.
A driver who improves credit between 24 and 25 may see a bigger drop than the age change alone would predict. A driver whose credit worsens can see the opposite. The birthday does not control the full quote.
Coverage and vehicle profile change the math
Competitor averages usually model full coverage, often with 100/300/100 liability limits. That matters. A lower deductible, higher comprehensive and collision limits, or a different vehicle can change the dollar savings more than age does. A 2012 Toyota Camry is a common benchmark in one source, but the same age on a different car can price very differently.
That is why average percentages are only useful when the coverage setup matches. If one quote assumes a Camry with standard full coverage and another quote assumes a newer SUV with broader protection, the “age 25” comparison stops being apples-to-apples.
Which carrier is cheapest for a 25-year-old?
There is no fixed winner. Carrier rank can flip at 25 because each insurer weights age, credit, claims, vehicle choice, and location differently. A company that is cheapest at 24 may not stay cheapest at 25, and the reverse can happen after a renewal.
InsureMojo cites a 13% age-25 drop for State Farm and a 4% drop for USAA in its comparison. That spread shows why you cannot assume every carrier reacts the same way. GEICO and Progressive often compare differently by driver profile, and the best quote for one 25-year-old can be expensive for another.
The practical rule is simple: get at least three quotes at your next renewal if your birthday lands just before or just after it. Switching usually makes the most sense when the new quote beats your current renewal by more than the amount you would expect from the age change alone. If the spread is tiny, staying put can be smarter once fees and coverage differences are added back in.
Start with the same liability limits, the same deductibles, and the same full-coverage setup on every quote. Otherwise the “cheapest” offer may simply be the one with less protection.
Ways to cut the bill beyond age
Age 25 can help, but it is rarely the only lever. If you want a lower bill, the fastest gains often come from your coverage choices, your deductible, and the discounts your carrier already offers. Age alone usually does not do all the work.
Adjust coverage limits and deductibles carefully
Raising deductibles can reduce the premium quickly, but only if you can cover the higher out-of-pocket cost after a claim. Reducing comprehensive or collision coverage can lower the bill even more, though that may not make sense for a newer or financed car. Keep liability limits realistic; cutting protection too far can backfire after a serious crash.
Use discounts that fit your driving pattern
Good-driver, low-mileage, telematics, multi-policy, and defensive-driving discounts can matter more than the birthday itself. Telematics can help if your driving is calm and predictable. A multi-policy discount can also move the quote enough that age no longer is the deciding factor.
A common first-timer mistake is waiting for age 25 to fix a rate that is being driven by a ticket or a high-cost coverage setup. The better move is to ask what part of the quote is age-related and what part is not. That tells you whether switching carriers, adjusting coverage, or waiting for the next renewal will produce the bigger savings.
Frequently asked questions
Does car insurance go down when you turn 25?
Usually, yes, but the lower price normally appears at renewal rather than on the birthday itself. If your policy renews before you turn 25, the reduction can wait until the next term. Tickets, claims, credit-based pricing, and vehicle choice can all reduce or erase the change.
How much does car insurance drop at 25?
Common averages point to a modest decline. MoneyGeek cites a $21 per month drop from 24 to 25, and InsureMojo says the national average decrease is 11%. Your result can be smaller or larger depending on carrier, state, coverage, and driving record.
Does car insurance go down at 25 if I had an accident?
Not necessarily. A recent at-fault accident can keep your premium elevated even after you turn 25. The age-based reduction may still exist in the background, but the claim surcharge or risk tier can absorb it. How long that effect lasts depends on the insurer and the state.
Why didn’t my car insurance go down when I turned 25?
The most common reasons are timing and offsetting risk factors. If your policy renewed before your birthday, the lower rate may be delayed. A speeding ticket, DUI, claim, poor credit-based insurance score, or different vehicle can also hide the age effect.
Is 25 the biggest age-related drop in car insurance?
Usually not. Some data show a larger drop around 21 than at 25, because insurers treat the move out of the youngest-driver group as a bigger shift. By 25, the pricing curve is often flatter, so the savings are real but smaller than earlier milestones.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.