Does Leasing A Car Come With Insurance? Read This First
Leasing a car usually does not include insurance; a common rule of thumb is to buy your own policy, and the lease often requires liability, collision, comprehensive, and gap coverage. Miss a required coverage and the lender can force-place insurance, bill you for it, or treat the lease as out of compliance. Here’s what the lease may require, what to verify before signing, and how to keep the car covered without paying for add-ons you do not need.
Does leasing a car come with insurance?
Usually no. A lease gives you the right to use the vehicle, but the lease agreement usually makes you the one who must carry insurance. The dealer may help start coverage, yet the policy itself is still yours, and the lease terms control what coverages, limits, and proof you must provide.
Why the lease agreement matters more than the dealer pitch
The lease agreement spells out who must carry insurance, whether proof is required before delivery, and how cancellation or loss-payee notices must be handled. A sales desk can describe the payment and the car, but the contract sets the coverage rules. Read the insurance section before you sign.
How leased cars differ from owned and financed cars
Owned cars usually need only the state minimum liability coverage, unless you choose more protection. Financed cars often need the lender named on the policy and may require collision and comprehensive. Leased cars usually sit at the stricter end: the lessor often wants liability, collision, comprehensive, and specific deductibles.
What insurance does a leased car need?
A leased car usually needs at least the state-required liability coverage and, under the lease, collision and comprehensive coverage as well. Gap insurance is often recommended because it can cover the gap between the lease payoff and the vehicle’s actual value after a total loss. The contract may set exact limits.
Liability insurance and state minimums
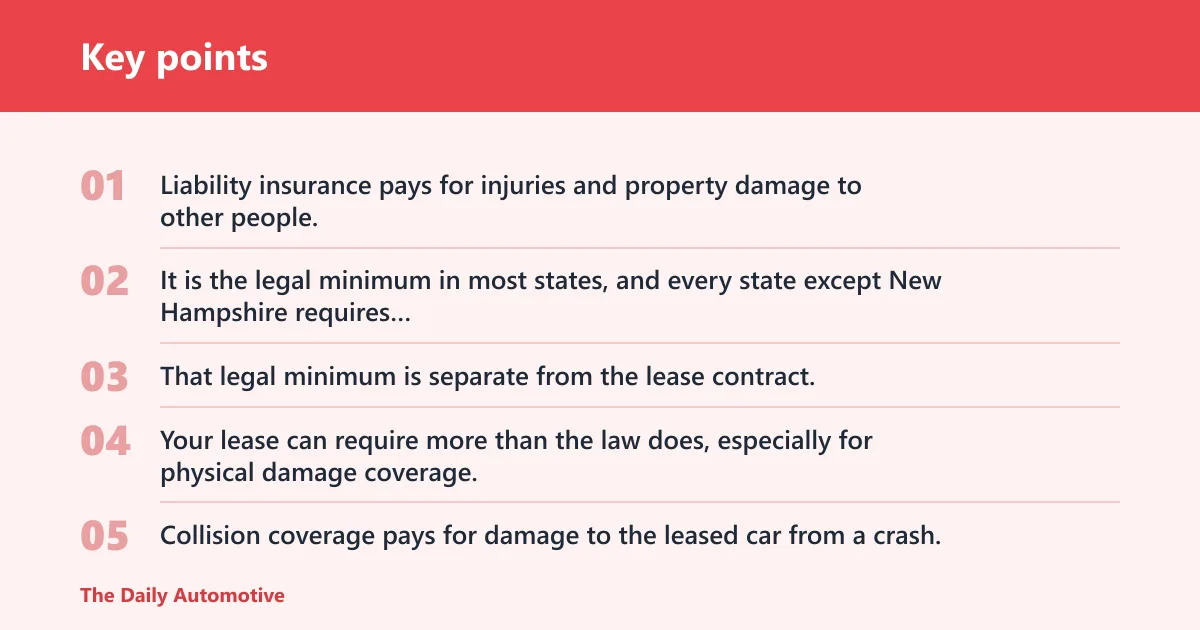
Liability insurance pays for injuries and property damage to other people. It is the legal minimum in most states, and every state except New Hampshire requires car insurance. That legal minimum is separate from the lease contract. Your lease can require more than the law does, especially for physical damage coverage.
Collision and comprehensive on most leases
Collision coverage pays for damage to the leased car from a crash. Comprehensive covers non-collision losses such as theft, fire, hail, vandalism, or falling objects. Many leasing companies require both because the car still belongs to them until the lease ends. Leave one out, and the lease may not meet contract terms.
When gap insurance makes sense
Gap insurance is often recommended for leases, especially if the car depreciates quickly or negative equity is rolled into the lease structure. It does not replace collision or comprehensive. Instead, it can help if the car is totaled and the lease payoff is higher than the car’s value.
Lease insurance checklist
Use this checklist before you sign or take delivery. It separates legal minimums from lease-required coverage, and it shows what proof the lessor may ask for. A missing deductible cap or missing lessor name can leave you technically insured but still out of compliance with the lease.
| Coverage type | Legal or lease-required | Who names the lessor | Typical deductible constraints | Proof document needed | Common mistake to avoid |
|---|---|---|---|---|---|
| Liability | Legal minimum in most states | Usually not named for liability alone | No deductible for liability claims | Declaration page showing limits | Assuming state minimums are enough for the lease |
| Collision | Usually lease-required | Lessor or lienholder may need to be listed | Lease may cap deductibles, often at a set dollar amount | Declaration page showing collision coverage | Choosing a deductible above the lease cap |
| Comprehensive | Usually lease-required | Lessor or lienholder may need to be listed | Lease may cap deductibles, often separately from collision | Declaration page showing comprehensive coverage | Leaving comprehensive off because the car is “new” |
| Gap insurance | Usually recommended, not always required | Not usually the key naming item | No standard deductible rule; contract may vary | Policy endorsement or lease addendum if required | Thinking gap coverage replaces collision or comprehensive |
Who pays for insurance on a leased car?
The lessee is usually responsible for paying for insurance on a leased car. That means the driver leasing the vehicle is generally responsible for buying the policy, keeping it active, and meeting the lease terms. The leasing company may set the rules, but it usually does not pay the premium for you.
Why the lessee usually pays
The lessor owns the car, but you are the one driving it and making monthly lease payments. The contract typically shifts insurance responsibility to you because the vehicle is still exposed to collision, theft, weather damage, and liability claims while you have possession of it.
What the leasing company can require
The leasing company can require collision and comprehensive, can set a deductible ceiling, and can require you to name the lessor as lienholder or loss payee. It may also require proof of coverage before delivery and reserve the right to reject a policy that does not match the lease terms.
How dealer-arranged coverage fits
A dealer may arrange insurance for a leased car, but that does not remove your responsibility to verify the policy. Check the declaration page, named insured, deductibles, and lessor information before you leave. A quick sign-up is not enough if the policy misses a lease condition.
How do you add a leased car to your insurance?
Get the VIN, the lease start date, and the lessor’s exact name before you call your insurer. Then add the vehicle with the required coverages and make sure the policy starts on the delivery date or earlier. Send proof to the lessor before pickup if the contract asks for it.
- Collect the VIN, lease agreement, and delivery date.
- Confirm the exact coverages the lease requires.
- Ask your insurer to add collision, comprehensive, and any required liability limits.
- Make sure the lessor is listed correctly if the contract requires it.
- Verify the deductible matches the lease cap.
- Obtain the declaration page and send it to the lessor if requested.
Match the policy start date to delivery
Line up new coverage before canceling the old policy. A cancellation date should match the new policy start date to avoid a lapse. A lapse is any period without active insurance, and even one day can count. Say your old policy ends Friday at 12:01 a.m.; the new one should begin at that same point.
Send proof before pickup
Many lessors want proof of insurance before the car leaves the lot. The insurance declaration page is the most common document because it shows the coverages, limits, deductible, and vehicle details. If the lessor needs the policy number or lienholder details, confirm those before you sign the lease papers.
Can you drive a leased car without insurance?
Usually no. Driving a leased car without insurance can put you in violation of the lease and applicable law, and it can create immediate financial risk if a crash or theft happens. A coverage lapse can also trigger fines, registration trouble, license problems, and higher premiums later.
What happens if coverage lapses
Do not let coverage lapse when moving into a lease or changing policies. Keep the new policy in place before canceling the old one, and do not cancel autopay too early. Insurance companies may charge more after a lapse, and some drivers may also face an SR-22 requirement after a lapse or violation.
Why late notice can cause lease trouble
If the lessor does not receive proof on time, it may treat the account as out of compliance and may force-place coverage. That coverage is often expensive and may protect the lessor more than it protects you. Late notice can also complicate registration or delivery timing.
Canceling the old policy the right way
You can cancel your car insurance whenever you want, and for any reason. Most companies make cancellation simple, usually by phone call or written request. If you paid in full, you may get money back after cancellation. Check your current policy for cancellation fees and notice rules first.
What the leasing company may require
The leasing company may require the lessor or loss payee to be named on the policy, may set deductible caps, and may ask for the declarations page as proof. These are contract terms, not guesses. If the lease and the policy conflict, the lease usually controls what counts as compliant.
Naming the lessor or loss payee
Many leases require the leasing company to be listed correctly on the insurance paperwork. This gives the lessor a financial interest in the vehicle if there is a loss. If the name is wrong, incomplete, or missing, the insurer may issue proof that looks fine to you but still fails the lease check.
Deductible caps
Some leases limit how high your collision or comprehensive deductible can be. A common mistake is choosing a lower premium by raising the deductible above the lease cap. That may save money on paper, but it can leave you noncompliant and responsible for more out of pocket after a claim.
Proof of insurance and cancellation notice rules
The lessor may request the declarations page before delivery and again after any policy change. Keep a copy handy and confirm the effective dates. If you cancel, set the replacement policy first, then cancel the old one only after the start time matches. That keeps the lease and the insurance aligned.
Picture a leased SUV with a contract cap of $500 for comprehensive deductible, but the new policy is written at $1,000. The driver has coverage, but not the coverage the lease asked for. That small mismatch can trigger a compliance problem long before any claim happens.
A common first-timer mistake is letting the dealer say “insurance is handled” and stopping there. The car may be insured, but the lease can still reject the policy if the lessor is missing from the paperwork or the declaration page does not show the required coverages.
Frequently asked questions
What insurance do I need for a leased car?
Start with the state minimum liability coverage, then check the lease for collision and comprehensive requirements. Many leases also recommend or require gap insurance. The exact answer depends on the contract, the state, and the lessor’s rules, so compare the policy against the lease before you sign.
Do I need full coverage on a lease?
In most cases, yes. “Full coverage” is a loose term, but lease contracts usually require liability plus collision and comprehensive. The lessor may also require a deductible ceiling and proof on the declarations page. Do not assume your current policy already satisfies the lease.
How do I add a leased car to my insurance?
Use the VIN, lease start date, and the lessor’s exact name to add the car to your policy. Ask for liability, collision, and comprehensive if the lease requires them, then match the policy start date to delivery. Send the declarations page to the lessor if requested.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.