How To Get A Car Loan When Self-Employed (It’s Possible)
Yes, self-employed buyers can get a car loan, and approval usually gets easier when you can show 2 years of tax returns, recent bank statements, and a stable debt-to-income ratio. Weak paperwork can mean a denial, a higher rate, or a smaller loan. This guide covers lender-friendly income proof, common underwriting signals, and when a personal auto loan is a better fit than business financing.
Can you get a car loan when self-employed?
Yes. Self-employed borrowers can qualify for car financing, but lenders usually want more proof than they ask from W-2 applicants. They often treat time in business like employment history, then compare reported income, cash flow, and debt obligations before deciding whether the payment fits.
The main issue is consistency. A lender cannot rely on a pay stub when income comes from invoices, app payments, client retainers, or seasonal jobs. Instead, the file has to show that money keeps coming in, even if the deposits vary from week to week.
Why lenders look for steadier proof
For a salaried worker, a recent pay stub and employer verification may be enough. For a self-employed borrower, the lender has to reconcile several records at once: tax returns, bank deposits, business expenses, and the monthly payment on the car. That is why underwriting is tougher.
A strong application does not need perfect income. It needs a pattern the lender can follow. If your deposits are regular, your debt load is manageable, and your paperwork matches, the file can still fit standard auto financing.
What documents do lenders want?
Lenders usually want tax returns, bank statements, and business records that connect reported income to current cash flow. Form 1040 is one of the most widely accepted proof-of-income documents, and lenders typically request the last two or three years of returns to see whether earnings hold up over time.
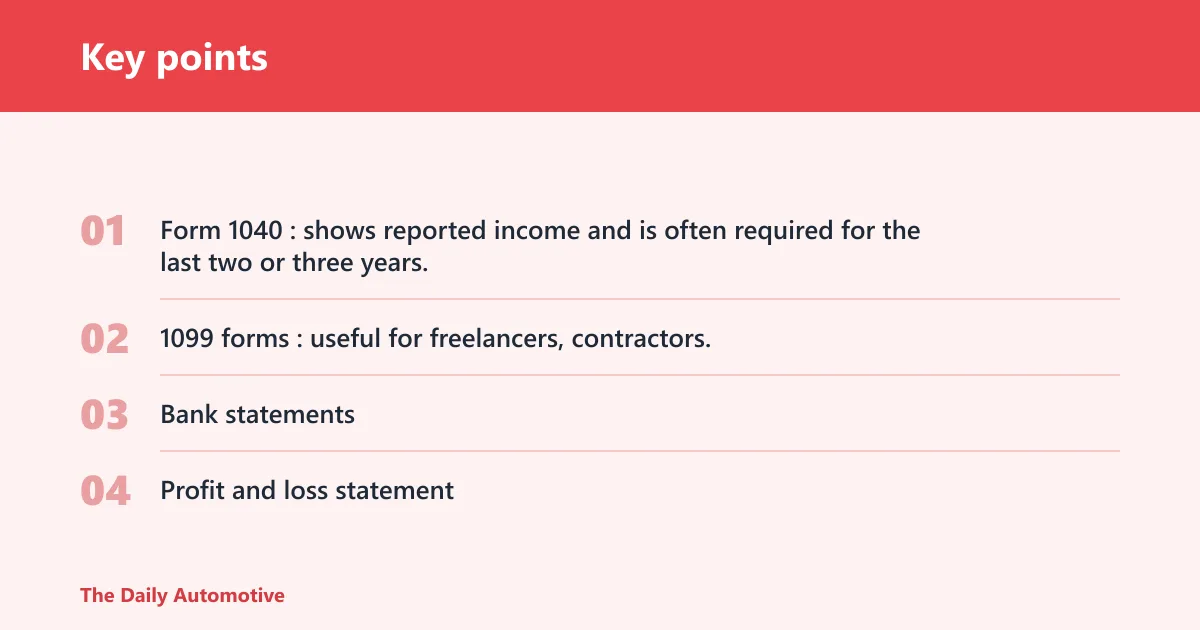
Core documents and what each one does
- Form 1040: shows reported income and is often required for the last two or three years.
- 1099 forms: useful for freelancers, contractors, and gig workers because they show annual earnings history from non-employee work.
- Bank statements: lenders may ask for six to twelve months to check recurring deposits and cash flow.
- Profit and loss statement: helps lenders judge current business health and can be year-to-date or annual.
Those documents do different jobs. Tax returns show what you reported to the IRS. Bank statements show what actually landed in your accounts. A profit and loss statement shows how the business is performing now, after expenses.
What if your tax returns look too low?
That is a common failure point. Heavy write-offs can make taxable income look much lower than actual cash flow, and recent losses can sink an application even when your business still moves money. If your return is thin, lenders may rely more heavily on bank statements, but they may still cap the loan amount or raise the rate.
Say your consulting business brought in steady deposits of about $8,000 a month, but your return shows far less after deductions. The lender may qualify you from the lower taxable figure, not the deposit total. That is why clean bookkeeping matters before you apply.
Self-employed income and loan documents
| Borrower type | Strongest proof documents | Likely weak spot | Best next step | Usually better fit |
|---|---|---|---|---|
| Freelancer | Form 1040, 1099 forms, 6 to 12 months of bank statements | Multiple clients and uneven payment timing | Match invoices to deposits and label recurring client payments | Personal auto loan |
| Gig worker | 1099 forms, bank statements, year-to-date profit and loss statement | Mixed app deposits and variable weekly earnings | Separate app income from transfers and keep a clean cash-flow log | Personal auto loan |
| Sole proprietor | Form 1040, profit and loss statement, bank statements | Write-offs that reduce qualifying income | Prepare a lender-facing summary that explains the expense structure | Personal auto loan |
| LLC owner | Form 1040, business bank statements, profit and loss statement, 1099s if applicable | Commingled business and personal funds | Show clean transfers and keep company accounts separate | Personal auto loan, unless the car is clearly business-only |
| Seasonal worker | Two or three years of tax returns, bank statements, profit and loss statement | Income swings during the off-season | Document last season’s peak and current reserves | Personal auto loan |
This table is the quick filter. If your income comes from several apps or clients, the lender wants a clean trail from source to deposit. If your business entity holds the income, then your paperwork has to explain why the money is available for a car payment now, not only on paper at tax time.
How do lenders judge your income?
Lenders judge whether the monthly payment fits your budget, and debt-to-income ratio is a key part of that review. Lower DTI signals stronger affordability. They also look at whether your income is stable enough to support the new loan without forcing you into a stretch payment.
DTI, cash flow, and reported income
DTI matters because it compares what you owe with what you bring in. If your current debts are already high, a car note can push the ratio too far. Even a strong business can run into trouble if personal obligations are heavy.
Recent losses and large deductions can also change the lender’s view of your file. A tax return that looks efficient from a tax standpoint may look weak from a lending standpoint. That gap is why self-employed buyers should review the numbers the way a lender will, not only the way an accountant will.
Why separate accounts make the file cleaner
Keeping business and personal finances separate improves document clarity. It makes income easier to verify, helps bank statements read cleanly, and reduces questions about whether a deposit is revenue, a transfer, or personal money moving around. Clean separation can save time and reduce friction in underwriting.
Suppose a rideshare driver deposits app payouts into one checking account and pays business fuel, repairs, and car wash charges from the same account. That makes the cash flow easier to trace than a setup where business income, rent, and household spending all move through one account.
Will a down payment or cosigner help?
Often, yes. A down payment of 10% to 20% can reduce financing needs, and a larger down payment may help cut monthly payments and improve rate prospects. A cosigner with strong credit can also help, but the cosigner takes equal responsibility for repayment.
How the down payment changes the deal
A bigger down payment lowers the amount financed. That can reduce the monthly payment, shorten the lender’s risk exposure, and make the file more workable if your income is irregular. It does not guarantee approval, but it can move a borderline application into a better range.
For self-employed buyers, that matters because the lender may already be cautious about income volatility. If the payment is smaller from the start, the budget test becomes easier to pass. A down payment can also help when the tax returns show less income than your business actually generates in cash flow.
When a cosigner makes sense
A cosigner is useful when your credit is weak or your income is hard to document. It can add another credit profile to the application and help offset inconsistency. But that person is fully on the hook if the loan goes unpaid, so this is a serious shared risk.
A common first-timer mistake is asking a parent or partner to cosign without explaining the payment plan. If the car note is about $420 a month and the business slows for two months, the cosigner still has to cover it. That obligation belongs to both borrowers.
How can you make approval easier?
Start before you submit the application. Check your credit score and fix errors before you shop, clean up your statements, gather the right documents, and use pre-qualification to estimate what terms may be available. U.S. News says car financing should be arranged early in the buying process, and that advice fits self-employed borrowers especially well.
- Pull your credit score and review any errors before shopping.
- Collect two or three years of tax returns, plus 1099s, bank statements, and a profit and loss statement.
- Make sure deposits are easy to trace to clients, apps, or contracts.
- Reduce revolving debt where possible so your DTI looks stronger.
- Save for a larger down payment if you can, ideally within the 10% to 20% range lenders often use as guidance.
- Use pre-qualification to compare offers before you pick a car.
Credit score still matters, and it affects both eligibility and rate. Zillow says self-employed borrowers may need a minimum 580 score for FHA, VA, and USDA loans, while conventional loans may require a 620 minimum score. Auto lending uses different rules, but the basic point holds: a higher score usually opens better terms, while weaker scores often mean a higher APR.
Bankrate notes that auto loan terms of 60 to 72 months or longer are widely available. Longer terms can lower the monthly payment, but they can also increase the total interest you pay over time. If your income is irregular, a longer term may help cash flow, but it should still fit your budget.
Should you use a personal or business loan?
A personal auto loan is often the cleaner fit when the car will be used for commuting, family errands, mixed driving, or day-to-day use. Business-purpose financing may make sense when the vehicle is clearly for company use and the paperwork supports that structure. The right choice depends on use, title, and how you want the loan treated.
When personal financing is usually better
If the vehicle will serve both work and personal driving, a personal auto loan is often easier to document. Lenders already understand that setup. You also avoid needing the car to fit a strict business-use file when your income already has enough moving parts.
When business-purpose financing may fit
Business-purpose financing can make sense when the vehicle is tied directly to company operations and the title needs to sit with the business. That structure is more common when the borrower wants the car to function as a company asset and can document the business need clearly.
That said, do not assume a business loan is the default just because you are self-employed. Many buyers are better served by a personal auto loan, especially when the income trail is simpler on the personal side than on the business side.
Frequently asked questions
Can I get a car loan if I’m self-employed?
Yes. Self-employed borrowers can get approved, but lenders usually want clearer proof of income than they ask for from W-2 applicants. Expect questions about tax returns, bank statements, and how long the business has been operating. Stronger credit and a lower DTI can improve the odds.
What documents do I need for a self-employed auto loan?
Most lenders want Form 1040, usually for the last two or three years, plus 1099 forms if you earn as a freelancer, contractor, or gig worker. Bank statements for six to twelve months and a profit and loss statement can also help show current cash flow.
How many years of tax returns do lenders want for self-employed income?
Lenders typically ask for the last two or three years of tax returns. They use those returns to see whether income is stable over time, not just strong in one season. If your recent return shows lower income because of deductions, bank statements may matter more.
Can I get approved for a car loan without a W-2 or pay stubs?
Yes, in many cases. Self-employed borrowers often qualify without W-2s or pay stubs, but they need other records that show consistent income and cash flow. Tax returns, 1099s, bank statements, and a profit and loss statement usually replace the employer-based documents.
Will a larger down payment help if I’m self-employed?
Often, yes. A down payment of 10% to 20% reduces the amount financed, and a larger amount may improve monthly payment affordability and rate prospects. It does not guarantee approval, but it can make a lender more comfortable with uneven income or thin documentation.
Should I use a cosigner for a self-employed car loan?
A cosigner can help if credit is weak or income is inconsistent, because the lender gets another credit profile on the file. The tradeoff is serious: the cosigner is equally responsible for repayment. Use this option only if both borrowers understand the risk.
How can I make my self-employed income easier for lenders to verify?
Keep business and personal finances separate, keep bank statements clean, and make deposits easy to trace back to clients or apps. Submit tax returns, 1099s, and a profit and loss statement that match your recent cash flow. Clean records reduce questions and speed up review.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.