How to Get Lower Car Insurance: 9 Ways to Cut Your Premium
The fastest way to get lower car insurance is to compare quotes from at least three insurers, raise your deductible, keep a clean driving record, and stack every discount you actually qualify for – combined, these moves routinely cut a premium by 20% to 40%.
The average U.S. driver now pays around $2,266 a year, or $189 a month, for car insurance, and full coverage runs closer to $2,926 a year according to 2026 Experian data. That number moves a lot based on your state, your driving record, and which discounts you actually claim – a single at-fault accident alone can add roughly 45% to your premium on average, sometimes far more depending on your insurer and state. The gap between a driver who does nothing and one who works the system below can easily be $1,000 or more a year.
This guide walks through nine specific, verifiable ways to lower your car insurance bill in 2026: protecting your driving record, comparing quotes correctly, adjusting your deductible, bundling policies, stacking real discounts, using your credit score where it still applies, adding safety features, choosing a lower-risk vehicle, and cutting your mileage. Each section includes the actual savings range you should expect, not vague promises.
1. Protect Your Clean Driving Record First
Nothing you do with quotes or discounts matters as much as this one. A single at-fault accident raises the average driver’s rate by roughly 45% nationally, and the increase can be far steeper depending on your insurer and state – State Farm’s average bump is around 14%, while some carriers raise rates by 70% or more for the same claim. The surcharge typically stays on your policy for three to five years, so one bad claim can cost well over $1,000 across that window.
Obeying speed limits, stopping fully at lights, and avoiding distracted driving keep tickets off your record, and tickets stack the same way accidents do. Ask your current insurer whether they offer accident forgiveness – many major carriers will waive the surcharge for your first at-fault claim if you have been claim-free for a set number of years, but you usually have to enroll before the accident happens, not after.
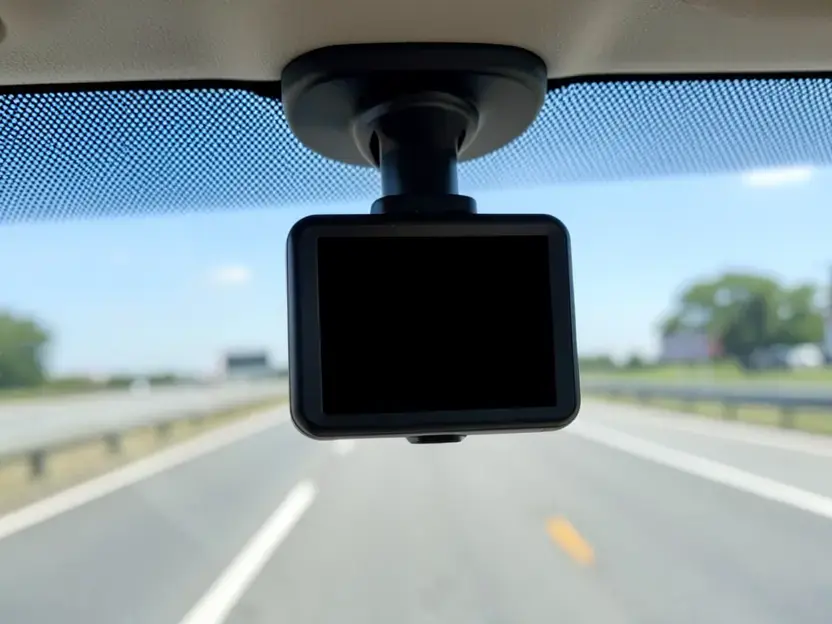
If you are ever in a collision where fault is disputed, documentation matters more than memory. This is the one place a dash cam earns its keep: it will not usually get you a direct discount from most major U.S. insurers, but clear video is often what keeps a contested claim from getting recorded against you at all.
PROTECT YOUR RECORD
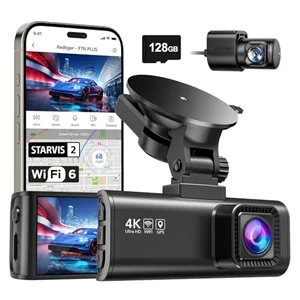 |
REDTIGER F7NP 4K Dash Cam – $129.99 Most insurers will not cut your premium just for owning a dash cam, but front-and-rear footage is exactly what settles a disputed-fault claim in your favor – and as this guide covers, one at-fault accident on your record is the single most expensive thing that can happen to your rate.
|
2. Compare Quotes From Multiple Insurers Every Renewal
Two drivers with identical records, cars, and coverage can be quoted hundreds of dollars apart by different companies, because each insurer weighs your state, ZIP code, and claims history differently. Get quotes from at least three companies – a mix of a national carrier, a regional insurer, and one online-only company tends to surface the widest price range. Do this at every renewal, not just when you first buy a policy; loyalty rarely earns you the lowest rate after the first year or two.
An independent agent can pull quotes across several carriers at once and explain what is actually driving the price difference, which is useful if your rate jumped for a reason that is not obvious from the renewal notice. Where you live changes the baseline more than almost anything else you control, which the table below makes clear.
| State | Average Monthly Full-Coverage Premium |
|---|---|
| New Hampshire (cheapest) | $127 |
| Vermont | $132 |
| Maine | $139 |
| New York | $304 |
| Connecticut | $326 |
| Maryland (most expensive) | $349 |
If you are quoted well above your state’s average, that is a signal to shop – not necessarily proof something is wrong with your record.
3. Raise Your Deductible – With a Real Example
Your deductible is the amount you pay out of pocket before your insurer covers the rest of a claim. Moving from a $500 to a $1,000 collision deductible typically lowers your premium by roughly 10% to 20%, depending on your insurer and driving history – on a $2,900 full-coverage policy, that can mean $290 to $580 back in your pocket every year.
The tradeoff is real: if you total your car or get in a major accident, you owe the higher amount before coverage kicks in. Only raise your deductible to an amount you could pay in cash today without financial strain. A good rule of thumb is to keep that difference sitting in a separate savings account rather than treating the extra premium savings as free money.
4. Bundle Your Insurance Policies
Combining auto insurance with your home, renters, or life insurance policy under one company typically saves 10% to 25% on both policies combined, according to industry-wide discount data for 2026. If you rent instead of own, bundling renters and auto insurance usually qualifies for the same kind of discount and is often the single easiest bundle to set up.
Ask your current insurer directly what bundle options they offer and get the combined quote in writing before switching – occasionally a specialist insurer beats a bundled rate even after the discount, so it is worth checking both ways.
5. Stack Every Discount You Actually Qualify For
Beyond bundling, insurers offer a long list of discounts that most drivers never ask about by name. The table below shows realistic ranges reported across major carriers in 2026 – treat the high end as achievable only if you qualify for the strictest version of that discount (a perfect driving score in a telematics app, for example, not just enrollment).
| Discount Type | Typical Savings |
|---|---|
| Safe driver / accident-free | 10% – 25% |
| Good student (typically 3.0 GPA or higher) | 10% – 25% |
| Usage-based / telematics program | 5% – 40% |
| Multi-policy bundle | 10% – 25% |
| Anti-theft device / immobilizer | 5% – 15% |
| Low annual mileage | 5% – 15% |
Telematics programs deserve a closer look because the range is so wide: most give you 5% to 10% just for enrolling and letting the app or plug-in device track your driving, then add up to another 30% to 40% if your actual braking, speed, and phone-use habits score well over several months.
One thing to know before you assume these all add up: discounts stack multiplicatively, not by simple addition. A 20% discount followed by a separate 10% discount gives you roughly 28% off total, not 30%, because the second discount applies to the already-reduced price. Ask your agent to show you the actual stacked percentage rather than adding the numbers yourself.
6. Improve Your Credit Score Where Insurers Still Use It
In most states, insurers are legally allowed to factor your credit-based insurance score into your rate, and the effect is large: drivers with poor credit pay roughly 98% more for full coverage on average than drivers with excellent credit, according to 2026 rate analysis. Paying bills on time, keeping credit card balances low, and avoiding new debt before you shop for insurance can meaningfully lower your quote.
Four states currently ban the practice outright: California, Hawaii, Massachusetts, and Michigan. Maryland, Oregon, and Utah apply partial restrictions instead of a full ban. If you live in one of those states, credit repair will not move your auto insurance rate at all – and as of 2026, lawmakers in Iowa, New York, Oklahoma, and Pennsylvania have introduced bills that would add their states to the restricted list, so this is worth rechecking if you live in one of those four.
7. Install Safety and Anti-Theft Features
Anti-theft devices make your car a less attractive target and typically qualify for a discount on comprehensive coverage. A factory or aftermarket alarm, a steering wheel lock, and a VIN etching kit are all inexpensive ways to qualify – ask your insurer which specific devices they recognize before buying, since not every brand is accepted the same way.
Advanced Driver Assistance Systems (ADAS) – automatic emergency braking, lane departure warning, and blind-spot monitoring – reduce the odds of the kind of accident that raises your rate in the first place, and a growing number of insurers now offer a modest discount for cars equipped with them from the factory. If you are shopping for a new car, ask the dealer which ADAS features are standard versus optional, since it can affect your insurance quote before you ever leave the lot.
8. Choose a Lower-Risk Vehicle Next Time You Buy
The car itself is one of the biggest inputs into your quote, separate from your driving record. Smaller engines, higher IIHS safety ratings, and lower theft rates all correlate with cheaper premiums, while high-horsepower engines, expensive-to-repair body panels, and models that show up often on theft-frequency lists push rates up regardless of how carefully you drive.
Before buying, ask your insurer for a quote on the exact trim and model year you are considering, not just the model name – a turbocharged performance trim of an otherwise ordinary sedan can carry a noticeably higher premium than the base version of the same car.
9. Drive Less, or Ask About Pay-Per-Mile Pricing
If you work from home, take transit part of the week, or simply do not put many miles on your car, say so – low annual mileage is its own discount category, separate from telematics enrollment, and typically saves 5% to 15%. Report your mileage accurately at renewal rather than guessing high out of habit.
If your annual mileage is genuinely low, ask specifically about pay-per-mile or usage-based programs, which bill you close to what a low-mileage driver actually costs to insure rather than a flat annual estimate built for an average driver. These programs are not the right fit for a long daily commute, but for a true low-mileage driver they can beat every other discount on this list combined.
Frequently Asked Questions
What is the single fastest way to lower car insurance?
Comparing quotes from at least three insurers at your next renewal is the fastest single action, since identical coverage can be priced hundreds of dollars apart between companies. Raising your deductible is the fastest way to see an immediate change on your current policy without switching carriers.
Does raising my deductible always save money?
It lowers your premium, typically by 10% to 20% when moving from a $500 to a $1,000 deductible, but it only saves you money overall if you can comfortably afford the higher out-of-pocket amount if you actually file a claim. If a higher deductible would strain your finances after an accident, the premium savings are not worth the risk.
Will bundling home and auto insurance always save money?
Usually, but not always. Bundling typically saves 10% to 25% combined, which beats separate policies most of the time, but a specialist insurer can occasionally beat a bundled rate on its own. Get both quotes in writing before you decide.
How much does one at-fault accident raise my rates?
On average, about 45% nationally, though the real number depends heavily on your insurer and state – it can range from roughly 14% at some carriers to over 70% at others, and the surcharge typically stays on your policy for three to five years.
Which states do not allow credit scores to affect car insurance rates?
California, Hawaii, Massachusetts, and Michigan ban the practice outright. Maryland, Oregon, and Utah apply partial restrictions. As of 2026, Iowa, New York, Oklahoma, and Pennsylvania have pending legislation that could add them to the restricted list.
Can I combine multiple car insurance discounts?
Yes, most discounts stack, but they multiply rather than simply add together. A 20% discount followed by a 10% discount results in about 28% total savings, not 30%, because each additional discount applies to the already-reduced price.
Conclusion
Lower car insurance almost never comes from one trick – it comes from stacking several of the moves above at the same time. Start with the two that cost nothing: compare quotes from at least three insurers and ask directly what discounts you already qualify for but have not claimed. From there, a clean driving record and a deductible you can actually afford will do more for your rate over the next few years than almost anything else on this list.
Review your policy every renewal, not just when your rate jumps – insurers change their pricing models often, and a company that was expensive two years ago may now be the cheapest option for your exact profile.