If You File Bankruptcy, What Happens to Your Car Loan?
Filing bankruptcy usually pauses repossession right away, but keeping the car depends on equity, chapter choice, and whether you can keep paying or cure missed payments through the case. Miss those payments or ignore the lender’s rights, and you can lose the car, face added fees, or turn a short-term cash problem into a repossession. This guide covers the stay, equity rules, Chapter 7 versus Chapter 13, and the payment math that decides whether keeping the car is realistic.
What happens to your car loan after filing?
The first effect is the automatic stay. It stops repossession immediately after filing, and it also halts collection calls and scheduled auctions in most cases. That pause is real, but it is not permanent. A lender can ask the court to lift the stay if the car is uninsured, the payments keep missing, or the lender is not adequately protected.
Think of the filing date as a hard stop for ordinary collection activity, not a free pass. The loan still exists, the lien still exists, and the payment due date does not disappear. If the case is dismissed or the stay is lifted, the lender can move again.
What the stay does not stop forever
The stay does not erase the loan balance. It does not give you an extra month simply because the case is open. And it does not block a lender from asking for relief if the car is losing value, uninsured, or far behind on payments.
Say your SUV is three payments behind when you file and the insurance lapses a week later. The stay still starts immediately, but the lender has a stronger basis to ask the court for permission to repossess. Filing buys time. It does not fix the account by itself.
Why the lender may still ask the court to lift the stay
Courts often look for risk to the lender’s collateral. If the car is not insured, if the loan is deeply delinquent, or if the payment stream has stopped for good, the lender may argue that the stay should come off. That is why the real question is not only whether filing stops repossession today, but whether the car can stay protected through the rest of the case.
Car equity and exemption guide
Car equity is the car’s market value minus the loan balance. If the result is positive, that is equity. If the result is negative, you owe more than the car is worth. Exemptions protect equity, not the vehicle itself, so the number that matters is how much value can be sheltered under the applicable exemption law.
The federal motor vehicle exemption protects up to $5,025 in equity. State law may give you more or less, and some states require you to use state exemptions instead of the federal ones. That is why the same car can be safe in one case and exposed in another.
When non-exempt equity gets trustee attention
The trustee looks at non-exempt equity. If the car’s value exceeds the exemption and there is enough value left after subtracting the lien, the trustee may try to sell the vehicle for the benefit of creditors. If the sale would produce little or nothing for unsecured creditors, the trustee may abandon the asset instead.
Suppose your car is worth $12,000 and the loan balance is $9,000. The equity is $3,000. If your exemption covers that amount, trustee interest is usually limited. If the exemption is lower than the equity, the trustee may care about the excess.
Why state law matters more than a single federal number
Exemption planning is not one-size-fits-all. Some states protect more vehicle equity than the federal system; others protect less. The same loan can lead to very different outcomes depending on where you filed, whether you can use federal exemptions, and how much equity sits in the car after subtracting the loan balance.
Chapter 7 car options
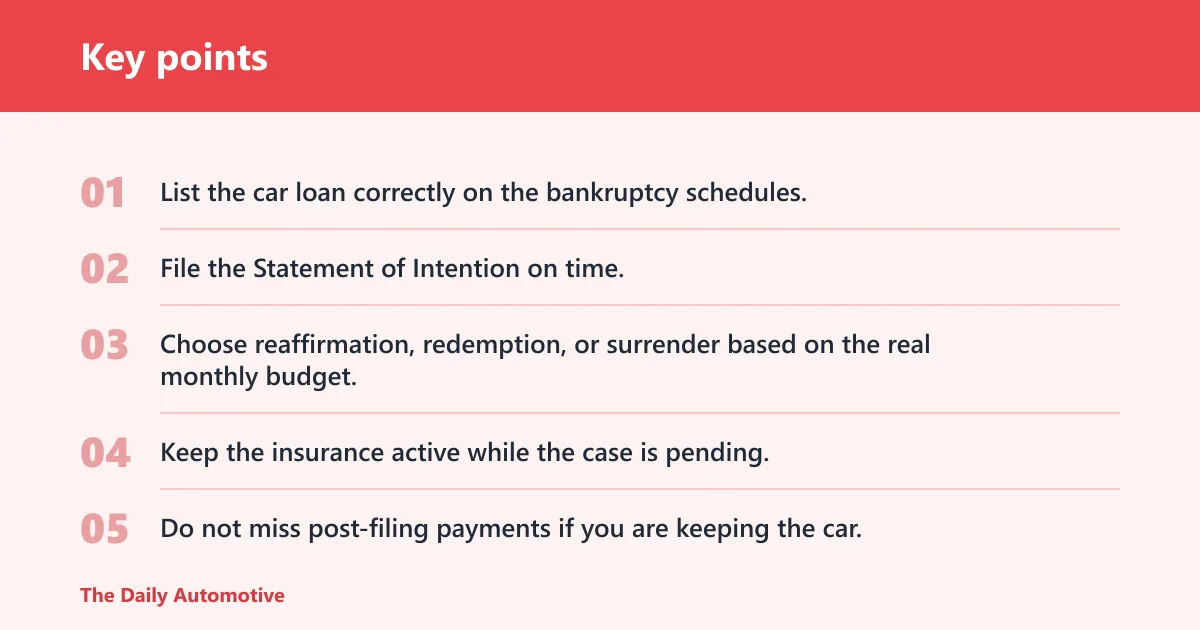
Chapter 7 is the liquidation chapter, and the common car choices are reaffirm, redeem, or surrender. The case moves fast, so the paperwork and deadlines matter. In many cases, a Statement of Intention for the car is due within about 30 days after filing the petition or by the meeting of creditors, whichever comes first.
That form tells the court and the lender what you plan to do with the vehicle. Missing it can complicate the result, especially if you want to keep the car and the lender expects a formal choice.
Reaffirmation: keep the loan alive after discharge
Reaffirmation keeps the full car-loan balance personally enforceable after bankruptcy. In plain English, you agree that the debt survives discharge. The lender may require the agreement to be filed with the court, and some cases call for court approval before it takes effect.
This can make sense if the payment is affordable, the car is reliable, and you want a clean path to keep the title and continue paying under the existing loan terms. It also keeps the downside: if you default later, the lender can pursue you on the reaffirmed balance.
Redemption: pay the car’s value in one lump sum
Redemption lets you buy the car at its current market value in one payment. It is not a new installment loan. It is a lump-sum payoff of the car’s value, which can help if the loan balance is much higher than what the car is worth and you can obtain the cash to redeem it.
For a high-mileage sedan worth $4,500 with a $9,000 balance, redemption can be appealing on paper. The obstacle is cash. Most borrowers do not have the lump sum sitting around, so redemption is available only when the numbers and the financing source actually work.
Surrender: return the car and address deficiency risk
Surrender means returning the vehicle to the lender. It does not, by itself, erase the remaining balance. The lender can sell the car, and if the sale leaves a shortfall, that shortfall is the deficiency balance. In many cases, discharge is what removes personal liability for that deficiency.
That distinction matters. Surrender ends the car payment obligation going forward, but the legal treatment of the leftover balance depends on the bankruptcy outcome and the chapter involved. Do not assume that handing back the keys automatically wipes out every dollar.
The Statement of Intention deadline you cannot miss
For Chapter 7, the car decision is deadline-driven. The Statement of Intention is usually due within 30 days after filing, or by the meeting of creditors, whichever is earlier. If you miss that window, the lender may argue that the chosen treatment is no longer available, or that the stay should be lifted so the lender can proceed.
- List the car loan correctly on the bankruptcy schedules.
- File the Statement of Intention on time.
- Choose reaffirmation, redemption, or surrender based on the real monthly budget.
- Keep the insurance active while the case is pending.
- Do not miss post-filing payments if you are keeping the car.
Chapter 13 and your car loan
Chapter 13 uses a 3- to 5-year repayment plan. It can catch up missed car payments over time while you keep the vehicle, which is the main reason many drivers use this chapter for auto debt. In some cases, it can also reduce the secured claim or strip a wholly unsecured junior lien.
The plan works best when the income can support both the ongoing car payment and the catch-up amount. If the budget cannot support both, the plan can fail and the car can still be lost later.
Catching up missed payments through the plan
Chapter 13 can spread arrears across the plan term, which reduces the need for a lump-sum cure. The ongoing monthly payment still matters, though. If you cannot keep up with the current payment and the plan payment at the same time, the cure does not solve the underlying affordability problem.
When cramdown may lower the secured debt
In some cases, Chapter 13 allows cramdown, which can reduce the secured portion of the claim to the car’s value. For a purchase-money vehicle loan, a common rule is the 910-day rule: if the car was bought for personal use within about 910 days before filing, cramdown is generally not available on that claim. Older purchase-money claims may qualify, subject to case details and local practice.
When lien stripping may apply in a rare second-lien case
If there is a second lien on the car and the first lien already uses up the vehicle’s value, the junior lien may be wholly unsecured. In that narrower situation, lien stripping may be possible in Chapter 13. That is a separate issue from the first loan, and it depends on value, lien priority, and chapter rules.
Can you keep the car?
Yes, you can sometimes keep the car if the payment is current or if Chapter 13 lets you cure the arrears. The real test is whether the car is protected by exemptions, whether the chapter gives you a workable path to stay current, and whether the monthly budget can support the loan after filing.
If the answer to those questions is no, keeping the car may be a poor fit even if the law technically allows it. Bankruptcy can stop repossession for now, but it cannot make an unaffordable vehicle affordable.
Current on payments and covered by exemptions
If you are current and the equity is protected, the car often stays with you. The lender still has the lien, but the trustee usually has less reason to sell the vehicle if there is no meaningful non-exempt equity. Reaffirmation may still come up in Chapter 7, but lender practice varies.
Behind on payments but able to cure in Chapter 13
If you are behind, Chapter 13 may be the better fit because it can spread the arrears over time. That option helps when the car is needed for work and the cash flow can support the plan. If the budget cannot support both the ongoing payment and the cure, the risk remains high.
Negative equity and why it can still be manageable
Negative equity does not automatically mean loss of the car. A vehicle worth less than the loan balance can still be protected if the exemptions cover the equity that exists and the payments are sustainable. The problem is not the negative number alone; it is the combination of debt, payment burden, and case treatment.
When keeping the car is not financially survivable
Keeping a car is not realistic when the payment crowds out housing, food, insurance, or the plan contribution. It is also a bad fit if the car needs repairs that the budget cannot handle. In those cases, surrender or replacement may be the cleaner choice, even if it is frustrating.
Decision table
| Borrower scenario | Can lender repossess right after filing? | Would the trustee likely care? | Does reaffirmation make sense? | Does surrender likely wipe out deficiency exposure? |
|---|---|---|---|---|
| Current on loan | No, the stay pauses repossession immediately after filing | Usually no, if equity is protected by exemption | Sometimes, if the payment is affordable and you want to keep the loan alive | Often yes, after discharge, but the sale still happens first |
| Behind on payments | Not immediately, but the lender may seek stay relief | Usually no unless non-exempt equity exists | Rarely, unless you can cure quickly and stay current | Often yes after discharge, though collection timing can depend on chapter treatment |
| Negative equity | No immediate repossession if the stay is in place | Maybe not, unless the car is worth enough beyond the exemption | Maybe, if the payment fits the budget and the car is worth keeping | Often yes after discharge, because the deficiency usually follows the sale |
| Car worth more than exemption | No immediate repossession, but stay relief or trustee action becomes more likely | Yes, the trustee may look at non-exempt equity | Sometimes, but it can be risky if the equity exposure is real | Often yes after discharge, but the trustee may sell the car first if value exists |
What can still go wrong after filing?
Three failures matter most: insurance lapse, repeated delinquencies, and missed post-filing payments. Any of them can give the lender a reason to seek stay relief. If the car is uninsured or the payment history stays broken, the case protection can narrow quickly.
Title loans and second liens create another layer. A title loan may have its own lien priority issues, and a second lien can change how equity is divided among creditors. Those cases need closer review because the car may secure more than one debt, and the clean Chapter 7 answer may not fit.
Insurance lapse and lender force-placed coverage
When insurance lapses, the lender may treat the car as exposed collateral. Some lenders will buy force-placed coverage and charge the cost back to the borrower. That does not solve the underlying problem. It usually makes the account more expensive.
Missed post-filing payments and repossession risk
Bankruptcy does not forgive the need to pay going forward if you are keeping the car. Missed post-filing payments can trigger default after the stay is lifted or after the plan fails. A car that is safe on filing day can become vulnerable later if the budget never stabilizes.
Repeated delinquencies and motion for relief from stay
If the pattern is repeated delinquency, the lender may ask the court for relief from the stay. That is especially common when the car is depreciating and the creditor sees no realistic cure. The legal protection exists, but it is not a shield against a broken payment pattern.
Frequently asked questions
What happens to my car loan when I file bankruptcy?
The filing usually stops repossession immediately and pauses collection activity. The loan and lien do not disappear. What happens next depends on the chapter, the equity in the car, and whether you can stay current or cure the arrears through the case.
Can you file bankruptcy on your car loan?
Yes. You can include the car loan in a bankruptcy case, but that does not automatically cancel the loan or guarantee that you keep the car. The outcome depends on whether you reaffirm, redeem, surrender, or cure missed payments under the plan.
What happens to your car loan when you file Chapter 7?
Chapter 7 usually gives you three choices: reaffirm, redeem, or surrender. The Statement of Intention is time-sensitive, and missing it can affect the result. If you keep the car, you still need a workable payment path and enough insurance to keep the lender protected.
What happens to my car payment after Chapter 7?
If you reaffirm, the car payment continues and the full balance stays personally enforceable after discharge. If you redeem, the old loan is replaced by a lump-sum payoff at value, not a new payment plan. If you surrender, the payment stops, but deficiency treatment still matters.
Can bankruptcy stop repossession of my car?
Yes, usually right away. The automatic stay freezes repossession immediately after filing and also halts collection activity and scheduled auctions in most cases. But the lender can ask the court to lift the stay later if the loan remains risky, uninsured, or badly behind.
Can I keep my car if I file Chapter 7 bankruptcy?
Often yes, if the payments are current or affordable and the equity is protected by exemption. Chapter 7 does not force a loss of the car in every case. The bigger question is whether the monthly payment, insurance, and loan terms still make sense after filing.
Do I still owe a deficiency after surrendering a car in bankruptcy?
Possibly, because surrender does not erase the sale shortfall by itself. The deficiency is the remaining balance after the lender sells the car. In many cases, discharge removes personal liability for that deficiency, but the timing and chapter treatment matter.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 Half Car Cover SUV,Top Cover with Red Reflective Strip, Hail Protector Car Cover with Cotton Liner, Sunroof & Windshield Cover for Ice and Snow, All Weather Car Body Cover for Sun, Rain, Dust
 Half Car Cover Top with Red Reflective Strip, Snow Car Cover with Cotton Liner, Sunroof & Windshield Cover for Ice and Snow, All Weather Car Body Cover Fit for Compact Sedan