What Does It Mean to Finance a Car? Loans, Rates and Terms
Financing a car means borrowing money to buy it, then repaying principal plus interest over a set term. Your monthly payment depends on the price, down payment, APR, and loan length. Miss those terms, and you can overpay by thousands or end up upside down on the loan. This guide covers loan structure, APR, payment math, down payments, trade-ins, and how to check the quote before you sign.
What it means to finance a car
To finance a car, you borrow from a lender and repay the balance in monthly installments over a fixed period. Most auto loans are secured by the vehicle as collateral, so the lender can repossess the car after default. The payment covers principal and interest, and the deal may also roll taxes, fees, and add-ons into the balance.
Auto loan basics
The principal is the original amount borrowed before interest. That balance starts the loan, but it is not always the same as the sticker price. If taxes, title work, documentation fees, extended warranty charges, or gap coverage get rolled in, the amount financed can be higher than the vehicle price alone.
That difference matters because a larger balance means a larger payment, more total interest, and more time before equity builds. Financing does lead to ownership after the loan is paid off, but the lender holds a lien until then.
Principal, interest, and monthly payments
Your monthly payment comes from three moving parts: how much you borrow, how long you borrow it for, and the APR attached to the loan. OneAZ notes that payment depends on loan amount, interest rate, and loan term. A bigger principal, a higher APR, or a shorter term each pushes the payment in a different direction.
Say your financed balance is $25,300 instead of $21,300 because you rolled fees and add-ons into the deal. At the same APR and term, the payment rises even though the car itself did not change. That is why shoppers should review the full contract, not only the vehicle price.
How car financing works step by step
Car financing follows a simple order: pick the vehicle, subtract any down payment and trade-in value, add taxes and fees, then apply the APR and term to get the monthly payment. The lender approves a specific amount, but the final contract should match the purchase sheet line by line. Pre-approval helps you set that ceiling before you shop.
- Choose the vehicle price.
- Subtract your down payment.
- Subtract any trade-in value.
- Add taxes, title, registration, doc fees, and any add-ons.
- Set the APR and loan term.
- Check the monthly payment and the total paid over the full term.
Where pre-approval fits
Pre-approval is a lender’s preliminary review of how much you may qualify to borrow. It helps you shop with a budget instead of guessing. It also gives you a way to compare the dealer’s offer against an outside quote, which matters if the dealer adds markups or product bundles to the contract.
APR vs. interest rate vs. loan term
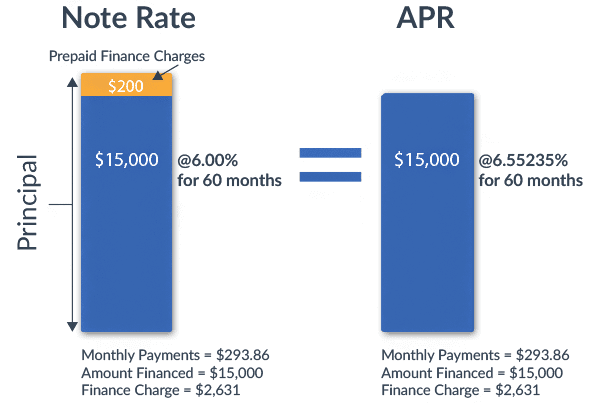
APR is the yearly cost of borrowing money, and it can include lender fees and other charges. A simple interest rate is only the interest portion. The loan term is the repayment length in months. They are related, but they are not the same number, and mixing them up makes payment comparisons useless.
What APR includes
APR gives a broader view of cost than a bare interest rate. Two loans can carry the same nominal rate but different APRs if one includes more fees. That is why APR is usually the better number to compare when you are choosing between lenders.
Better credit can qualify borrowers for a lower APR. The same source says good credit is typically 660 or higher for better rates. That does not guarantee approval, and it does not guarantee the same pricing at every lender, but it usually improves the odds of a better offer.
Why term length changes total cost
Typical auto loan terms range from 36 to 72 months. Longer terms usually lower the monthly payment because the balance is spread out over more months. The tradeoff is more total interest, because the lender charges for a longer period of time. (Caranddriver)
A 36-month loan can feel tight month to month but may save a meaningful amount in interest. A 72-month loan can fit a budget more easily, yet it can keep you in the loan longer and slow equity growth. That matters if you want to sell the car early.
How do down payment and trade-in affect what I finance?
A down payment is money you put toward the car upfront. A trade-in value is the amount the dealer or lender applies from your old vehicle. Both reduce what you finance, which can lower the payment, cut interest, and improve approval odds. A larger upfront contribution can also make the loan look less risky to the lender.
How each one reduces the balance
The same source says a typical down payment is 10–20% of the car’s price. That is a common target because it shrinks the principal quickly. Trade-in equity works the same way: if your old car is worth more than what you owe on it, that positive equity can reduce the amount financed on the next loan.
Suppose a car costs $28,000, you put $3,000 down, and your trade-in value is $4,000. That means $7,000 comes off the purchase before taxes and fees are added. If you skip both, you borrow much more, and the monthly payment rises even if the car is identical.
Why both can improve approval odds
Lower borrowing needs can help a borderline application because the lender has less money at risk. That can matter for first-time buyers and shoppers with limited credit history. It also matters when the buyer is close to the top of a lender’s loan-to-value comfort range.
Car finance quote checker
Use this table to check whether a quote makes sense before you sign. It turns the purchase into a budgeting equation: vehicle price minus upfront credits, plus taxes and fees, equals the amount financed. Then APR and term convert that balance into a payment and a total interest cost.
| Quote item | Sample amount | What it does | Check point |
|---|---|---|---|
| Vehicle price | $28,000 | Starting purchase price | Match the buyer’s order |
| Down payment | -$3,000 | Reduces the balance | Confirm cash is applied |
| Trade-in value | -$4,000 | Reduces the balance | Check for payoff if any loan remains on the trade |
| Taxes and fees | $2,200 | Raises the amount financed if rolled in | Ask for each fee line |
| Add-ons and gap coverage | $1,200 | Raises the amount financed if included | Decline anything you did not request |
| Amount financed | $25,300 | Principal the loan is based on | Check the math before signing |
| APR | 8.9% | Yearly borrowing cost | Compare against other lenders |
| Term | 60 months | Repayment length | See whether the payment still fits your budget |
| Estimated monthly payment band | $510 to $540 | Approximate range at nearby rates | Higher APR pushes it up; lower APR pulls it down |
| Total interest over the term | About $6,200 | Extra cost above the amount financed | Longer terms usually raise this number |
| Negative equity flag | Moderate | Risk if the car depreciates faster than the loan balance falls | Risk rises with a small down payment or a longer term |
Here is the failure case to watch for: suppose the dealer rolls $1,200 in add-ons, a warranty, and gap coverage into the loan without calling it out clearly. The payment may still look manageable, but the balance is larger than expected, interest costs rise, and equity builds more slowly. That is the kind of quote that deserves a hard pause.
Negative equity means you owe more on the loan than the car is worth. It matters if you sell, trade, or total the vehicle, because the loan balance can exceed the insurance payout or sale price. Gap insurance can cover that difference if the car is totaled or stolen and the loan balance is still higher than the vehicle’s market value. (Caranddriver)
How long can a car loan term be?
Common auto loan terms run 36, 48, 60, or 72 months, and some lenders stretch beyond that. Carmoola says car finance agreements typically last between one and six years. The right term depends on budget, vehicle price, and how long you expect to keep the car.
When a longer term may fit the budget
A longer term can make a newer or safer vehicle reachable if the shorter-term payment would strain your cash flow. That can be sensible if you need room in the budget for insurance, maintenance, or emergency savings. It can also help a first-time buyer avoid overcommitting early in ownership.
When a longer term raises risk
The downside is slower equity growth. If you put little money down and finance for a long term, the balance can stay above the car’s market value for a long stretch. That increases negative equity risk, especially on vehicles that depreciate quickly.
Picture a shopper who chooses a 72-month term to shave the payment down, then adds almost nothing at signing. The payment may feel easier in month one, but the buyer could be stuck owing more than the car is worth for years. That is where gap insurance becomes worth discussing.
Is financing a car better than paying cash?
Financing can preserve savings for emergencies, repairs, or other goals, while paying cash avoids interest and many loan fees. Neither choice is always better. The better option depends on how much liquidity you want, how comfortable you are with debt, and whether the payment still leaves room for your other bills.
When cash can be the cleaner move
Cash removes APR, monthly debt, and most loan paperwork. It can also simplify ownership because there is no lien release to wait for. If you have the money set aside and you would still keep enough reserve after the purchase, cash can be the lower-cost option.
When financing can be the safer move
Financing can be the safer call if paying cash would drain your emergency fund. That is especially true for used-car shoppers, where repairs can arrive early and without warning. In that case, a manageable payment may be better than an empty checking account.
Frequently asked questions
What credit score do I need for a better car loan rate?
There is no universal cutoff, but better credit usually improves approval odds and pricing. The same source says good credit is typically 660 or higher for better rates. Lenders still look at income, debt, the vehicle, and the size of the loan, so a higher score helps more than it guarantees.
What happens if I finance a car with bad credit?
Bad credit can mean a higher APR, a smaller approved amount, or stricter loan terms. The payment may still fit, but the total interest can rise quickly. A larger down payment, a shorter term, or a cheaper vehicle can help reduce the lender’s risk and improve the quote.
How do rates and terms change my monthly payment?
A higher APR increases the payment because borrowing costs more each month. A longer term lowers the payment by spreading the balance over more months. The catch is that longer terms usually raise total interest, so a lower payment can mean a more expensive loan overall.
What is the difference between APR, interest rate, and loan term?
Interest rate is the cost charged on the borrowed principal. APR is the broader yearly cost of borrowing and can include fees. The loan term is how long you repay the loan, measured in months. Two loans with the same rate can still have different APRs and payments.
What does it mean to finance a car?
It means borrowing money to buy a vehicle and repaying that loan in monthly installments over a set term. Most auto loans are secured by the car, so the lender can repossess it after default. The contract usually includes principal plus interest, and sometimes taxes, fees, or add-ons.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
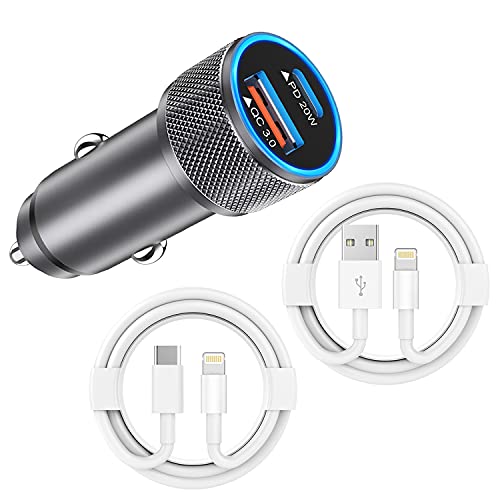 iPhone Car Charger,USB C Fast Car Charger[Apple MFi Certified] Apple Car Charging 38W Dual Port CarCharger Cigarette Lighter Adapter 2x3ft PD&QC 3.0 Lightning Cable for iPhone 14/13/12 Pro/11/Airpods
 FLORICH Leather Seat Cover, Car Seat Covers Front Set, Waterproof Car Seat Protectors, Front Seat Covers 2 Pack, Breathable Automotive Seat Covers Protector Fit for Most Cars Trucks SUV