What Percent Down Payment for a Car? 2026 Averages Explained
Experts still recommend putting 20% down on a new car and 10% down on a used one, but real buyers are not hitting that mark. The average new-car down payment fell to just 11.6% of the purchase price in the second quarter of 2026, according to Edmunds, the lowest share in nearly six years.
That gap has real financial consequences. On a $35,000 new car financed at 6.5% APR over 60 months, the difference between putting down 10% and 20% is about $68 in extra monthly payment and roughly $600 in additional interest paid over the life of the loan, on top of the $3,500 you did not put toward the price upfront. Down payment size also determines how quickly you build equity instead of owing more than the car is worth.
This guide breaks down what percent buyers are actually putting down in 2026, how that percentage shifts by credit score and loan type, what a bigger down payment actually saves you in dollars, and practical ways to boost your down payment before you shop.
How Much Down Payment Do You Actually Need for a Car?
There is no legal minimum down payment on a car loan. The 20% figure most sites repeat traces back to a personal-finance guideline called the 20/4/10 rule: put down at least 20%, finance for no longer than four years, and keep your total monthly vehicle costs (loan payment, insurance, and fuel combined) under 10% of your gross monthly income.
Lenders themselves are usually far less strict than that rule implies. Buyers with strong credit can often finance a new car with 0% down through a manufacturer promotion, and many banks and credit unions approve loans with as little as 5% to 10% down. The 20% figure is a savings target that protects your finances, not a number most lenders will refuse to go below.
The percentage matters more on used cars and with weaker credit. Used vehicles carry meaningfully higher interest rates than new ones, so a 10% minimum down payment is common advice for used-car buyers. Lenders working with below-average credit scores also frequently require 10% or more of the purchase price just to approve the loan in the first place, since a bigger down payment offsets some of the risk they are taking on.
AFTER YOU BUY: KEEP YOUR PAPERWORK ORGANIZED
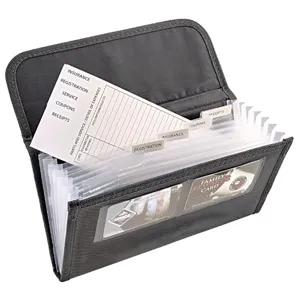 |
High Road Glove Box Organizer and Registration Holder – $12.99 Once you have made your down payment, you will be handed a loan contract, a temporary registration, and an insurance card, so this keeps all of it in one place in your glove box instead of loose in the cupholder.
|
Average Car Down Payment in 2026: What Buyers Are Actually Putting Down
Real down payment data has been sliding for the last two years as vehicle prices climb and affordability tightens. Here is how the average new-vehicle down payment has moved, according to Edmunds industry data:
| Quarter | Average New-Vehicle Down Payment |
|---|---|
| Q2 2025 | $6,433 |
| Q1 2026 | $6,206 |
| Q2 2026 | $5,815 (11.6% of purchase price) |
That 11.6% share is the lowest it has been since the third quarter of 2020. Used-car buyers put down less in dollar terms too, averaging about $4,016 in the second quarter of 2026. Meanwhile the average amount financed for a new vehicle hit a record $43,899 in the first quarter of 2026, meaning buyers are borrowing more while putting down a smaller share of the price than they were a year earlier.
Down Payment Percentage by Loan Type and Credit Score
The right down payment percentage for you depends heavily on your credit profile and how you are financing the car:
- New car, prime credit (roughly 700+): Many buyers qualify for 0% to 10% down, sometimes with a promotional 0% APR that makes the down payment size mostly a personal choice rather than a lender demand.
- New car, average or below-average credit: Lenders more commonly ask for 10% to 20% down to bring the loan-to-value ratio down and offset a higher-risk approval.
- Used car through a bank or credit union: Expect a 10% minimum in most cases, since used-car loan rates run much higher than new-car rates.
- Buy-here-pay-here or subprime lots: These often require the largest down payments, frequently 10% to 20% or more, because the lender is carrying most of the default risk itself.
- Leasing: A traditional down payment does not apply the same way. You typically pay a smaller upfront cost, a capitalized cost reduction, plus taxes, fees, and the first month, though a bigger upfront payment still lowers your monthly lease cost.
Interest rates make the down payment decision even more important on used cars. As of early-to-mid 2026, the average new-car loan rate runs around 6.39% to 6.94% depending on the lender and loan term, according to Experian and Bankrate data, while the average used-car loan rate sits far higher, around 11.43%. That gap means the same down payment percentage saves you more in total interest on a used car than on a new one, simply because the rate it is offsetting is so much higher.
Why a Bigger Down Payment Saves You Real Money
The math is straightforward: every dollar you put down is a dollar you are not paying interest on for the next several years. Here is what that looks like on a $35,000 new car financed at 6.5% APR over 60 months:
| Down Payment | Loan Amount | Monthly Payment | Total Interest Paid |
|---|---|---|---|
| 10% ($3,500) | $31,500 | $616.33 | $5,480.02 |
| 20% ($7,000) | $28,000 | $547.85 | $4,871.13 |
Moving from 10% to 20% down on this example saves about $68 a month and roughly $609 in total interest, on top of the extra $3,500 in equity you started with. A bigger down payment also improves your approval odds and, on the margin, your rate tier, since it lowers your loan-to-value ratio and signals to the lender that you are a lower-risk borrower.
The Real Risk of a Small or Zero Down Payment
A small down payment means a bigger loan, and a bigger loan means it takes longer for what you owe to fall below what the car is actually worth. New vehicles commonly lose a substantial share of their value in the first year alone, so a buyer who finances the full purchase price with 0% down can end up owing more than the car is worth within months of driving it off the lot.
This situation is called negative equity, or being underwater on your loan. It becomes a real problem the moment you need to sell, trade in, or the car is totaled in an accident: your insurance payout or trade-in value will not cover the remaining loan balance, and you are left paying the difference out of pocket or rolling it into your next car loan, which starts that new loan underwater too.
A small down payment also means a higher monthly payment and a higher risk premium, since lenders price in the extra default risk of a high loan-to-value loan. Even a modest down payment of a few thousand dollars meaningfully reduces how long you are exposed to negative equity.
How to Calculate the Right Down Payment for Your Budget
Instead of chasing a fixed percentage, work backward from what you can actually afford without draining your savings:
- Add up the true purchase price, including sales tax, registration, and dealer fees, not just the sticker price.
- Check your emergency fund first. Do not use money you would need for a real emergency, even if it means a smaller down payment.
- Decide on a target percentage based on the car type: aim for roughly 20% on a new car and at least 10% on a used one if your budget allows it.
- Run the numbers through a car loan calculator using your actual estimated interest rate, not a generic figure, since new and used rates differ by several percentage points.
- Compare the monthly payment at a few different down payment levels and pick the one that keeps your total monthly car costs comfortably under 10% to 15% of your gross income.
5 Ways to Boost Your Down Payment Before You Buy
- Use your trade-in equity. If you own your current car outright or have equity in it, that value rolls directly into your down payment on the next car.
- Open a dedicated savings account. Automate a transfer every payday into a separate account earmarked only for the down payment, so it is not tempting to spend.
- Check manufacturer incentives and rebates. Automakers periodically offer cash-back rebates that can be applied straight to your down payment, on top of any promotional financing.
- Know that the federal EV tax credit is gone. The $7,500 federal new-EV credit and $4,000 used-EV credit ended for vehicles acquired after September 30, 2025, so do not plan your down payment around it. Some states still offer their own EV rebates, and if you finance a new, US-assembled vehicle between 2025 and 2028, the interest on the loan itself may qualify for a separate federal deduction of up to $10,000 a year, subject to income limits.
- Sell what you are not using. Unused electronics, furniture, or a second vehicle can add a meaningful lump sum to your down payment fund in a single weekend.
Frequently Asked Questions
How much should I put down on a $30,000 car?
Using the traditional 20% guideline, that is $6,000. In practice, the national average is lower: buyers financed new vehicles with an average down payment of just 11.6% of the purchase price in the second quarter of 2026, according to Edmunds. On a $30,000 car, that works out closer to $3,480. Putting down 20% still lowers your interest cost and monthly payment, but it is a savings goal, not a requirement.
Is it smart to put 50% down on a car?
It can be, if the cash does not come from your emergency fund. A 50% down payment cuts your loan balance, interest charges, and monthly payment dramatically, and it protects you from ever owing more than the car is worth. The tradeoff is opportunity cost: that money is no longer available for savings, investments, or emergencies, so it only makes sense if you would otherwise leave the cash sitting idle.
Do you have to put 20% down on a car?
No. There is no legal or universal lender requirement to put 20% down. Many buyers with good credit qualify for financing with 5% to 10% down, and some manufacturer promotions offer 0% down on new vehicles. The 20% figure is a personal-finance recommendation, not a rule your lender will enforce, though skipping it usually means a higher monthly payment and more interest paid over the loan.
What percent is a typical down payment on a car today?
In the second quarter of 2026, the average new-car down payment was 11.6% of the purchase price, the lowest share since the third quarter of 2020, according to Edmunds data. Used-car buyers typically put down a smaller dollar amount, averaging around $4,016 in the same quarter. Financial advisors still generally recommend aiming higher, around 20% on a new car and 10% on a used one, even though the real-world average has been trending down.
Does a bigger down payment lower my interest rate?
Not directly, but it can help indirectly. Your interest rate is mainly set by your credit score and the lenders own rate sheet, not your down payment percentage. However, a larger down payment lowers your loan-to-value ratio, which some lenders reward with a slightly better rate tier, and it always reduces the loan balance that rate applies to, which lowers your total interest cost even if the rate itself does not change.
What happens if I cannot afford any down payment?
You can still finance a car with 0% down if you qualify for a manufacturer or lender promotion, but expect a higher monthly payment and a real risk of being underwater on the loan almost immediately, since new cars typically lose a meaningful chunk of their value in the first year. If a 0% down deal is your only option, consider a less expensive vehicle, a shorter loan term, or waiting a few months to save even a small down payment to protect yourself.
Conclusion
The traditional advice to put 20% down on a new car and 10% down on a used one still protects you financially better than the current 11.6% national average. But it is a guideline, not a requirement: what actually matters is putting down as much as you can without touching your emergency fund, understanding how your credit and loan type change what lenders expect, and running the real math on your loan amount before you sign.
A bigger down payment lowers your monthly payment, cuts your total interest, and protects you from owing more than the car is worth if your plans change. Even an extra few thousand dollars upfront makes a measurable difference over the life of a five- or six-year loan.