Will Applying For A Car Loan Hurt Your Credit? Find Out
Yes, an auto loan application can lower your credit score a little, but the drop is usually small and temporary. Multiple rate-shopping applications for the same type of loan may count as one inquiry in many scoring models when they fall inside the model’s shopping window, though the exact treatment can vary. This guide shows how to compare offers without turning a minor dip into a real financing problem.
Hard vs soft checks and loan impact timeline
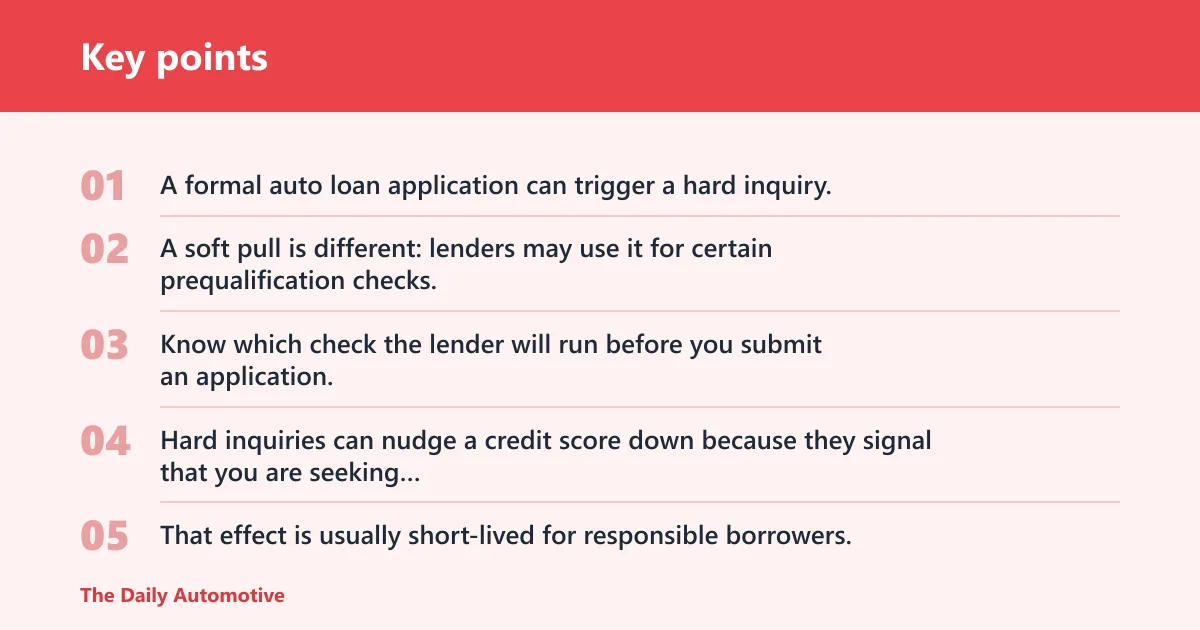
Hard inquiry vs. soft pull
A formal auto loan application can trigger a hard inquiry. A soft pull is different: lenders may use it for certain prequalification checks, account reviews, or promotional offers, and it usually does not affect your score. Know which check the lender will run before you submit an application.
Hard inquiries can nudge a credit score down because they signal that you are seeking new credit. That effect is usually short-lived for responsible borrowers. Hard inquiries generally stay on U.S. credit reports for about 2 years, even though the score effect is often shorter.
Why a loan application is different from paying the loan
Applying for a loan and carrying a loan are separate credit events. The application can cause a small dip. The loan itself can affect payment history, credit mix, and total debt after it appears on the account. Payment history is usually the biggest credit factor, so on-time payments matter far more over time than a single inquiry.
Suppose you submit one application on Monday and then make every payment on time after funding. The inquiry may fade from the score model quickly, while the payment record can support your score for much longer.
Does preapproval affect credit?
Auto loan preapproval may involve a credit check, so it can affect credit if the lender uses a hard inquiry. Prequalification is not the same thing. Prequalification is often lighter-weight and may use a soft pull, while preapproval usually gives a stronger estimate of terms before you commit.
Preapproval versus prequalification
Do not treat the two terms as interchangeable. A preapproval can show what a lender is willing to offer based on a fuller review of your credit file. Prequalification is usually a less formal screen. If you are comparing lenders, ask which type of check they use before you share a full application.
That distinction matters because score impact and approval impact are different problems. A soft pull may leave your score alone, yet a lender can still decline the request based on income, debt load, or other underwriting rules.
What changes on your report after you apply
A hard inquiry from an application can appear on your credit report after the lender checks your file. The inquiry itself is separate from the loan account. If you are approved and the loan funds, the new auto loan may then appear as an installment account on your credit report.
The funding step is separate from the application step. Do not assume the account shows up the moment you are approved, and do not assume final funding creates a new inquiry. Approval and funding are different stages.
Car loan inquiry table
| Action | Usual credit impact | How long it tends to matter | When to avoid it |
|---|---|---|---|
| Soft pull | Usually no score change | Typically no score effect to fade | Avoid if the lender says it will switch to a hard inquiry before you are ready |
| Hard inquiry | Can cause a small, temporary score drop | Score effect is usually short-lived; the inquiry can stay on the report for about 2 years | Avoid if you are about to apply for another major loan and every point matters |
| Multiple preapprovals | May create multiple inquiries, though some models treat rate shopping together | Usually short-lived on the score side if the applications are grouped in the model’s shopping window | Avoid stretching applications over many days or weeks without a plan |
| Final funding | Usually adds the loan to your credit file rather than a new inquiry | Can affect the file for the life of the loan and after payoff in reporting history | Avoid if the new payment would strain your budget or raise your debt load too far |
| Re-shopping after denial | Can add more inquiries if each lender checks your file separately | Each inquiry can remain visible for about 2 years, even if the score effect fades sooner | Avoid repeated applications without first fixing the reason for the denial |
How much does a car loan application lower your credit?
The drop is usually small, but the exact number varies by scoring model and by your starting profile. One inquiry generally does not cause a denial by itself. The larger issue is whether your overall file already looks stretched, thin, or recently active with other credit applications.
Why the score drop is usually small
Credit scores are built to weigh many factors, and a single hard inquiry is only one piece. Responsible borrowers often see the effect fade with time. Credit score effects from credit-seeking activity are usually short-lived, especially when payments stay current and no new delinquencies appear.
FICO Score 8 is a generic score model, and FICO Auto Score is industry-specific for vehicle lending. An auto loan can affect them differently. Lenders may use either one, or another version entirely, so a score move in one model does not guarantee the same move in another.
Why thin files and subprime files can feel it more
Borrowers with thin credit, subprime credit, or no prior auto loan history often have less room for extra hard inquiries. A small dip may matter more when the file already has few accounts, short history, or recent late payments. That does not mean you should avoid shopping. It means you should do it with tighter timing.
Picture a first-time buyer with one credit card and no installment history. Two well-spaced applications and a third one a week later can make the file look busy. If the same shopper groups offers from several lenders in a short period, the score impact is usually easier to manage.
Why final loan funding can matter more than the inquiry
Car loans can affect payment history, credit mix, and total debt. Credit mix can include open installment accounts and revolving credit accounts, so adding a car loan may change that balance. A paid-off loan can also remain on a credit report for up to about 10 years after payoff.
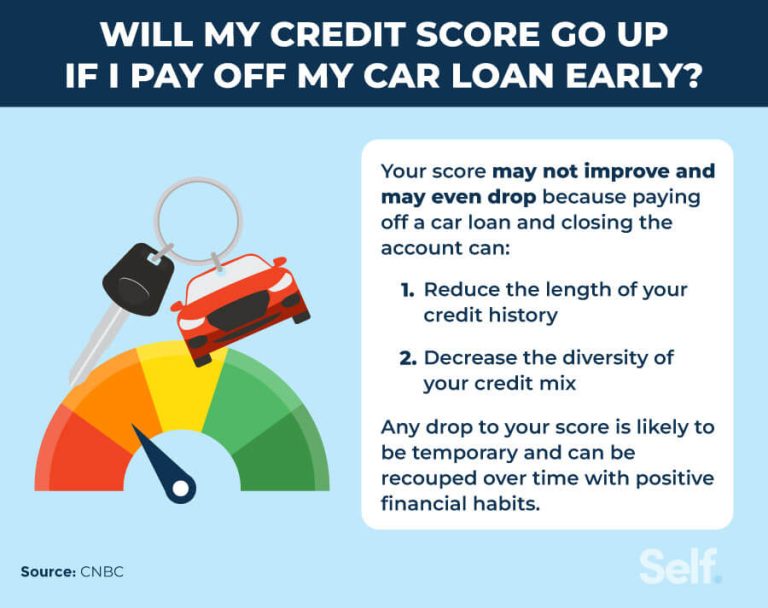
Paying off a car loan early may cause a small, temporary drop in credit scores. That does not mean early payoff is bad. It means the score model may briefly react to the change in account mix and installment history.
How to shop for rates without extra damage
Compare lenders before you choose a loan, and do it in a tight period rather than over several weeks. Rate shopping within a short scoring-model window can help multiple auto inquiries count like one inquiry in many cases, but treatment varies by model and version. That is why you should keep applications clustered, not scattered.
- Check your credit before you apply so you know where you stand.
- Ask each lender whether the first check is a soft pull or a hard inquiry.
- Collect quotes in the same shopping period instead of stretching the process out.
- Compare the rate, term, down payment, and total cost before you accept any offer.
- Skip extra applications once you have the best offer you are likely to use.
A common first-timer mistake is applying with one lender today, another next month, and a third after a dealer visit. That pattern can stack unnecessary hard inquiries. If the offers are for the same car loan search, keep the timing tight and keep your paperwork ready.
Time applications around other major credit needs
If you plan to apply for a mortgage or refinance soon, be careful with auto loan shopping. A temporary dip may matter when another lender is about to review your file. If a mortgage rate lock, refinance deadline, or other large borrowing event is close, waiting on the car loan may be the safer move.
That advice matters most when the rest of your credit profile is borderline. A modest score change can move pricing or approval terms, even if it does not cause a full denial.
Check your credit before you apply
Checking your own credit usually does not hurt your score. It helps you spot errors, see recent inquiries, and estimate how a lender may view your file. If you find a late payment, a wrong balance, or an unfamiliar account, fix that before you shop for a loan.
What lenders look at beyond the application
Approval depends on more than the score. Payment history is still the biggest credit factor. Credit mix matters too, and debt-to-income ratio is a lender factor that sits outside the credit score. DTI can matter for future borrowing even when the score looks strong.
Payment history
Making car payments on time can help credit. Missing a payment or paying late can hurt credit scores. This is the part of the loan that can help over time if handled well, and hurt fast if it is not.
Credit mix
Credit mix can include installment and revolving accounts together. Adding a car loan may improve the mix for some borrowers, especially those with only revolving accounts on file. It can also change the shape of the profile in ways lenders notice beyond the score.
Debt-to-income ratio
DTI matters because lenders use it to judge whether a new monthly payment fits your budget. It is not the same as a credit score factor. A borrower can have a fair score and still fail a lender’s income or DTI screen.
Score impact versus approval impact
A hard inquiry can lower a score a little, but approval also depends on income, existing debt, employment stability, and the size of the requested payment. A small score dip does not automatically mean denial. It does mean you should avoid stacking extra applications when you already know your file is tight.
Frequently asked questions
Will applying for a car loan hurt your credit score?
Usually yes, but only a little. A formal application can trigger a hard inquiry, which may cause a small, temporary dip. That does not mean you should avoid comparing lenders. It means you should keep the applications grouped and avoid unnecessary repeats.
How many auto loan applications can I submit without hurting credit?
There is no universal number. Many scoring models treat rate-shopping applications for the same type of loan as one inquiry if they fall inside the model’s shopping window, but the window varies. The safest approach is to submit only the offers you truly need and do them close together.
Does rate shopping for a car loan count as one inquiry?
Sometimes it does, but not in every model and not in every situation. Rate shopping is meant to let you compare offers without being punished for every single lender check. The best protection is to shop quickly, within one organized period, and avoid spreading applications out.
How long does a hard inquiry from an auto loan last?
The score effect is usually short-lived for responsible borrowers, but the inquiry can remain on a U.S. credit report for about 2 years. That visible record does not mean your score will keep dropping for 2 years. The score impact typically fades much sooner than the report entry.
Should I check my credit before applying for a car loan?
Yes. Checking your own credit helps you catch errors, estimate your rate range, and decide whether you should wait before applying. It is especially useful if you have thin credit, recent late payments, or a major borrowing event coming up soon.
What credit factors matter most when you apply for a car loan?
Payment history matters most, followed by the rest of your profile: credit mix, total debt, income, and DTI. Lenders also look at the specific score they use, which may be FICO Score 8, a FICO Auto Score, or another version. Approval is broader than the inquiry alone.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.