How Much Should You Spend on a Car? Budget Rules
A common car budget guideline starts with an all-in monthly cap: keep your total car costs at or below about 10% to 15% of take-home pay, and lean toward the lower end if you have student loans, high rent, or variable income. Spend too much and the payment can crowd out insurance, fuel, maintenance, and savings, turning a “new car” into a monthly squeeze. This guide shows you how to set that cap, subtract ownership costs, and work backward to a maximum purchase price.
Start with take-home pay
Take-home pay is the safer budgeting base because it is the money that actually reaches your checking account after taxes and deductions. Gross income can help with loan shopping, but it can overstate what you can safely spend if it ignores payroll taxes, health premiums, retirement contributions, and other deductions.
The practical rule is to work from monthly net pay first, then compare the car against your full household budget. A common guideline puts the monthly car payment at 10% to 15% of take-home income, while total transportation costs should stay around 15% to 20% of take-home income.
That gap matters. A payment can look “comfortable” on paper while insurance, fuel, and maintenance push the real cost well past your limit.
Where gross income can mislead buyers
Some lenders and calculators still lean on gross income because it is easy to verify. That can make a car look affordable before you subtract taxes, rent, student loans, child care, or other fixed bills.
One guideline says the total car price should not exceed 35% of annual gross income. That can be useful as a ceiling check, but it is not a spending target. If your monthly budget is tight, your real limit is lower.
What should your car payment be?
A reasonable monthly car payment usually stays in the 10% to 15% range of take-home pay, with the lower end working better when your budget is already tight. That rule applies to principal and interest only, so it is not the same as what you should spend on transportation overall.
A lower payment can still hide a vehicle that costs too much if the loan term is long or the APR is high. Approval is not a budget. If a lender offers more than your target, you still need to stay with the number that fits your life.
Why approval amount is not your limit
Approval limits are built around the lender’s risk, not your monthly comfort. A larger approved loan can simply mean you qualify for more debt, not that the payment leaves room for insurance, repairs, or savings.
Suppose a buyer can be approved for a payment that fits the loan officer’s formula but leaves only a thin cushion after rent and groceries. That buyer should cut the target price, not stretch the term to make the monthly number look easier.
Count total transportation costs
The payment is only one line in the budget. Total transportation costs should include the loan payment, insurance, fuel or charging, maintenance, repairs, and a buffer for taxes, registration, and first-year service.
That is why the total transportation benchmark of 15% to 20% of take-home pay is more useful than payment alone. It captures the costs that show up after the sale, when a “good deal” can become expensive fast.
Insurance before you buy
Insurance can move the budget more than buyers expect. It varies by age, location, driving record, and vehicle type, so the same car can cost very different amounts to insure.
Get a quote before you commit. A sporty trim, a large SUV, or a model with expensive parts can push your monthly total above your cap even if the payment looks fine.
Fuel or charging in the monthly total
Fuel or charging belongs in the monthly budget because commute length and vehicle efficiency change the cost of ownership. A small commuter car and a three-row SUV will not drain the same amount of cash, even if their payments are similar.
That matters most for buyers with long commutes or mixed city and highway driving. The same car can be a budget fit for one driver and a mismatch for another.
Maintenance, repairs, and first-year fees
Oil changes, tires, brakes, and unexpected repairs should be budgeted monthly. So should taxes, registration, and any initial service you know will be due soon after purchase.
A first-year buffer is one of the most overlooked parts of car budgeting. A set of tires, a registration fee, or a scheduled service can arrive right after you buy, when your savings are already thinner.
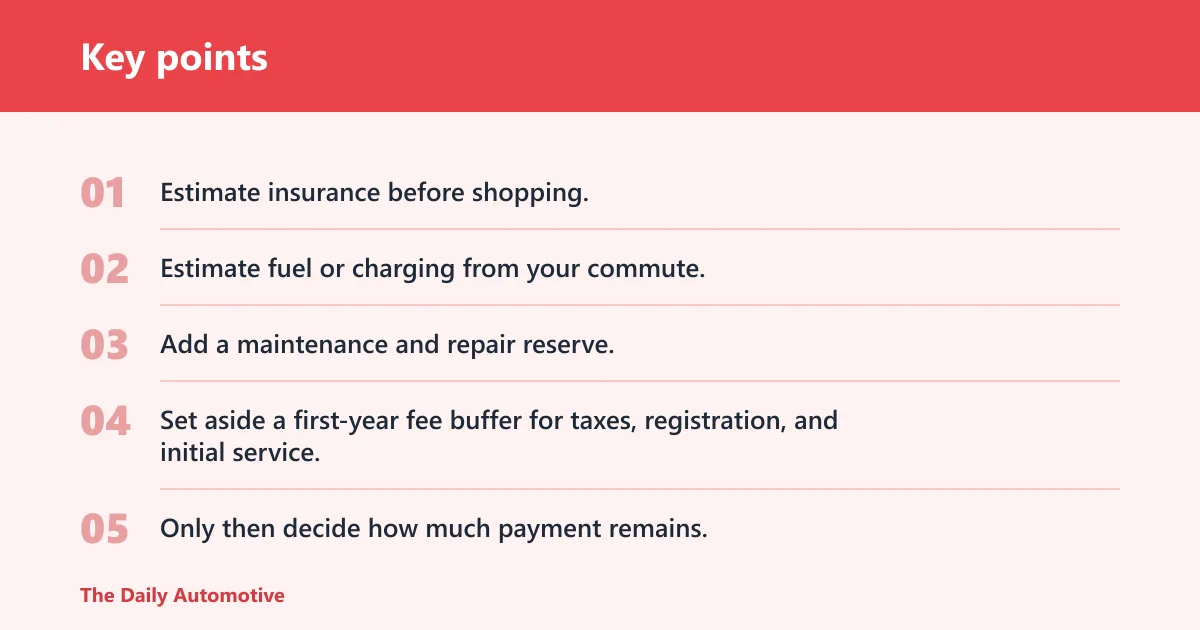
- Estimate insurance before shopping.
- Estimate fuel or charging from your commute.
- Add a maintenance and repair reserve.
- Set aside a first-year fee buffer for taxes, registration, and initial service.
- Only then decide how much payment remains.
How the 20/4/10 rule works
The 20/4/10 rule is a financing framework, not a comfort guarantee. It uses about 20% down, limits financing to no more than 4 years, and aims to keep the payment near 10% of income.
It is popular because it reduces the amount financed and keeps the loan short enough to limit interest costs. If you follow it, you are less likely to end up upside down on the car before you have built much equity.
Why 20% down matters
A 20% down payment reduces the amount financed, lowers the monthly payment, and cuts interest over the life of the loan. It also lowers the odds that you will owe more than the car is worth early in the loan.
The bigger the down payment, the less room there is for a stretched loan to hide an overpriced vehicle. That is one reason buyers who can put money down usually have more budget control.
Why 48 months is the strict target
A 48-month loan term is the stricter version of the rule because it keeps the car paid off faster. That matters when you want to avoid paying years of extra interest on a vehicle that loses value quickly.
Longer terms can make a car look affordable by shrinking the monthly payment. They do not make the car cheaper.
When a longer term starts to backfire
Once a loan stretches to 60 or 72 months, the payment may fall enough to fit a weak budget, but the total interest rises and the price of the vehicle can be hidden by the lower monthly number. That is how buyers end up with a car that only works on paper.
Long terms can also trap you in negative equity, especially if you roll taxes, fees, or old debt into the loan. The car may depreciate faster than the balance falls.
How much car can you afford with debt?
If you already have student loans, high rent, or uneven income, you should shrink the car budget instead of stretching the term. The safe move is to stay toward the lower end of the payment and total-transportation ranges, then leave room for months that are worse than average.
Debt payments compete with your car payment for the same take-home dollars. If those obligations are already heavy, the car budget needs to be conservative, not optimistic.
Student loans and high rent
Student loans and high rent reduce the room left for a car because they are fixed monthly obligations. That means the payment benchmark alone is not enough; the full transportation budget needs to fit after those bills are paid.
A common first-timer mistake is to use the lender’s approval number and then hope the rest of life stays stable. It often does not.
Variable income and uneven expenses
Variable income calls for a wider safety margin. If your pay changes month to month, use the lower end of the transportation range and keep a cash buffer for slow months.
Uneven expenses matter too. If you already know that some months bring child care spikes, seasonal bills, or irregular overtime, build the car budget around the leaner months, not the best ones.
When to shrink the budget, not stretch the term
If the payment only works after you move to a longer loan, the budget is probably too high. The better fix is to choose a cheaper car, increase the down payment, or wait until other debt falls.
That choice is especially important if you are close to the edge already. A longer term can reduce stress on paper while increasing stress later.
Car budget reversal worksheet
This worksheet turns income into a car budget in the right order: start with take-home pay, subtract non-car bills, set the transportation cap, and then work backward to the maximum payment. The example uses the $4,000 monthly take-home figure and the payment and transportation ranges above.
| Monthly take-home pay | Essential non-car bills | All-in transportation cap | Maximum payment |
|---|---|---|---|
| $4,000 | Set aside rent, food, debt, utilities, and savings first | $600 to $800 | $400 to $600 |
| $4,000 | Higher fixed costs or variable income | Choose the lower end, then subtract insurance, fuel, and maintenance | Often closer to the low end of the range |
The table is not a permission slip to spend every dollar in the cap. It is a ceiling that still has to absorb insurance, fuel or charging, maintenance, and first-year fees.
Say your monthly take-home pay is $4,000 and your non-car bills are already heavy because of rent and student loans. In that case, the payment should probably stay below the middle of the range, because the transportation cap has to leave room for the rest of your budget.
Price ceiling by loan term
Once you know the maximum payment, you can convert it into a price ceiling by choosing a loan term and APR. A shorter term gives a lower ceiling because more of each payment goes to principal, while a longer term raises the ceiling only because it spreads the balance over more months.
The same APR assumption is used across the examples below so you can compare the effect of term length instead of mixing variables. These are estimates, not quotes.
| Loan term | Estimated price ceiling at $400 payment | Estimated price ceiling at $500 payment | Estimated price ceiling at $600 payment |
|---|---|---|---|
| 48 months | about $18,000 | about $22,500 | about $27,000 |
| 60 months | about $21,000 | about $26,000 | about $31,500 |
| 72 months | about $23,500 | about $29,000 | about $35,000 |
These ceilings show why a longer loan can be dangerous. The payment may fit, but the vehicle price climbs fast, and the total interest climbs with it.
Should you buy new or used if you want to stay on budget?
Used cars often protect the budget better because someone else absorbed the steepest early depreciation. New cars can still make sense if the price gap is small, the warranty coverage matters, or the financing terms are unusually strong, but the total cost still has to fit your cap.
Do not compare only the sticker price. Compare insurance, taxes, registration, fuel, maintenance, and expected depreciation too. A cheaper used car with high repair risk can cost more than a newer one if you need predictable monthly spending.
What to compare beyond the sticker price
Look at the full first-year cost, not just the sale price. That includes the down payment, monthly payment, insurance quote, fuel estimate, registration, taxes, and a repair reserve.
If two cars have similar payments, the one with lower insurance and better fuel economy may be the better budget fit. That is especially true for commuters and first-time buyers who need predictable cash flow.
Frequently asked questions
How much should I spend on a car based on my income?
Use monthly take-home pay, not gross income, as the safer base. A common guideline keeps the payment at 10% to 15% of take-home pay and total transportation at 15% to 20%. If you have student loans, high rent, or variable income, stay near the lower end.
What percent of my income should a car payment be?
A commonly used guideline is 10% to 15% of take-home income for the monthly car payment. That range is for principal and interest only, so it should not be treated as the full transportation budget. Insurance, fuel, and maintenance still need their own room.
What is the 20/4/10 rule for buying a car?
The 20/4/10 rule uses 20% down, a loan term of no more than 4 years, and a payment target near 10% of income. It is a financing discipline meant to reduce interest and keep the loan from running too long, not a promise that any approved car fits your budget.
How much car can I afford if I have student loans?
Student loans reduce the amount left for transportation, so the car budget should shrink rather than stretch. Start from take-home pay, subtract your fixed bills, and use the low end of the payment and transportation ranges. If the loan only works with a longer term, the car is probably too expensive.
Should I budget for insurance and gas too when buying a car?
Yes. Insurance, fuel or charging, maintenance, and repairs belong in the monthly budget because they change the real cost of owning the car. A payment-only budget can be badly wrong if the car is expensive to insure or uses more fuel than your commute can support.
Is a longer car loan a good way to afford a more expensive car?
Not usually. A longer term lowers the monthly payment, but it raises total interest and can hide a car that is too expensive for your budget. If the deal only works at 60 or 72 months, it is usually better to lower the price, raise the down payment, or keep shopping.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.