Additional Car Insurance for Rental Cars: What You Need
Additional car insurance for rental cars is worth buying only if gaps remain after you check your auto policy, credit card benefits, and the rental counter waiver. The main misses are loss of use, diminished value, admin fees, and medical or liability limits your own policy may not cover. Ignore those gaps and you can owe the rental company or another driver hundreds or thousands after a minor crash or theft. This guide gives you a coverage-gap checklist so you can decide whether to buy the add-on or skip it.
Do you need extra rental coverage?
If your personal auto policy already includes liability, collision, and comprehensive coverage, you may already have enough protection for a U.S. rental. Even then, deductibles, policy limits, exclusions, and fees such as loss of use can still leave you exposed, so the answer is not a simple yes or no.
When your own auto policy may already be enough
If your policy has liability, comprehensive, and collision coverage, you likely already have the main protection for a standard rental.
When a deductible makes add-on coverage more appealing
A covered claim on your own policy still triggers your deductible, and that can be the reason to buy the rental-company waiver or a third-party policy. If your deductible is around $1,000 and the daily add-on is modest, paying extra can buy a cleaner, potentially cheaper way to transfer risk for a short trip.
Where liability-only drivers face the biggest gap
Drivers with liability-only coverage usually lack protection for damage to the rental vehicle. Drivers without car insurance or with underinsured coverage may benefit from the rental company’s extra protection. This is the group most likely to need temporary add-on coverage for a short rental period.
What your auto policy may cover
Your personal auto policy may cover a rental through liability, collision, and comprehensive coverage, but the claim still runs through your own policy terms. That means policy limits, deductibles, and exclusions can matter more than the rental desk pitch.
Liability coverage and what it pays
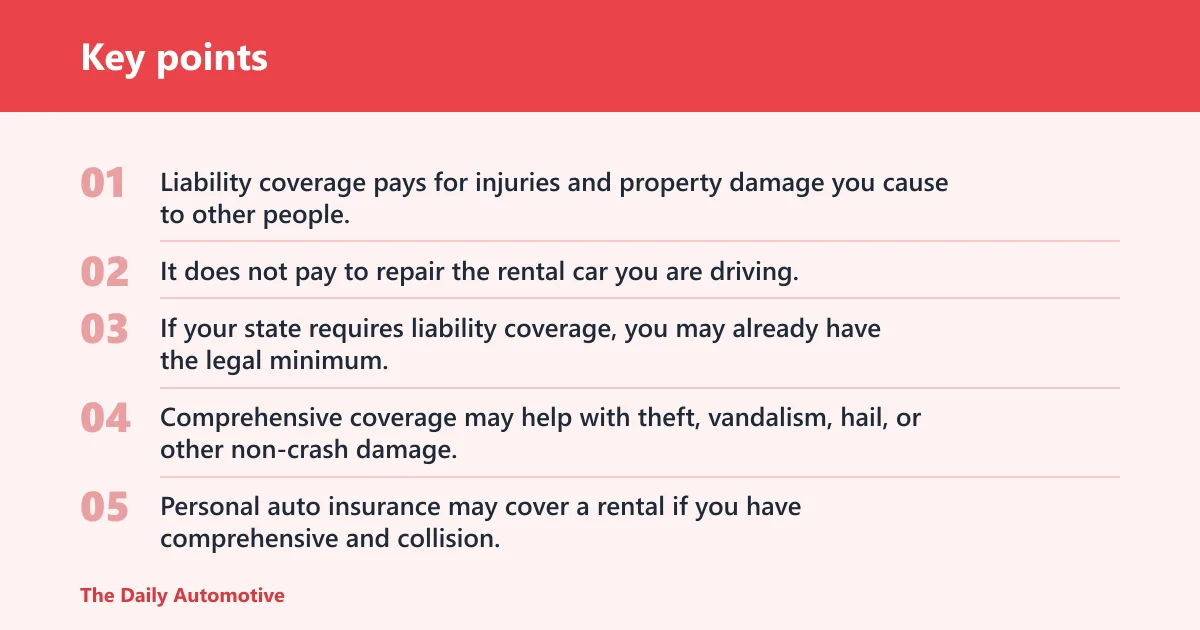
Liability coverage pays for injuries and property damage you cause to other people. It does not pay to repair the rental car you are driving. If your state requires liability coverage, you may already have the legal minimum, but minimums can be too low for a serious crash.
Collision and comprehensive coverage for rental damage
Comprehensive coverage may help with theft, vandalism, hail, or other non-crash damage, while collision coverage may help with crash damage to the rental vehicle. Personal auto insurance may cover a rental if you have comprehensive and collision. The deductible still applies on a covered rental claim.
Deductibles, limits, and exclusions to check first
Policy limits cap how much your insurer pays. Exclusions can include business use, luxury or specialty vehicles, or renting outside your normal coverage area. If you lease a car, check the terms of the lease and your auto policy carefully before you rely on any rental coverage.
A common first-timer mistake is checking only the rental company’s damage waiver and forgetting the loss of use clause in the contract. If the car sits in a shop for about eight days after a parking-lot crash, the bill can include more than bodywork alone.
Does your credit card cover rentals?
A credit card may add rental-car coverage as a perk, but it is not universal and it is rarely a full substitute for auto insurance. Many cards cover damage to the rental vehicle only, often as secondary coverage, and many exclude liability entirely.
Primary versus secondary card coverage
Some cards are primary, which means they can pay before your personal auto insurer. Others are secondary, which means they sit behind your own policy. The card benefit often requires you to charge the entire rental to that card and decline the rental company’s collision damage waiver.
Why liability is usually left out
Credit card rental benefits often focus on physical damage to the rental car. Liability, which covers injuries and property damage to others, is usually excluded. That gap matters if you cause a crash that injures someone in another vehicle or damages a guardrail, storefront, or parked car.
How card charging rules can affect coverage
Many issuers require the rental to be paid with the eligible card, and some also require the driver to be the cardholder or an authorized user. Miss that detail and the benefit can disappear. Check whether the card covers the vehicle class, the rental length, and the country.
Rental car coverage decision table
This checklist table shows what is covered, what remains a gap, and whether extra coverage is usually worth buying in common scenarios. Use it after you check your auto policy, your card benefit, and the rental contract.
| Scenario | Likely covered already | Common gaps | Extra coverage worth buying? |
|---|---|---|---|
| Full coverage | Liability, collision, and comprehensive on your auto policy; possibly card damage coverage | Deductible, policy limits, loss of use, admin fees, towing, exclusions for business or specialty vehicles | Maybe, if the deductible is high or the trip involves a luxury, one-way, or business rental |
| Liability-only | Damage to others up to your liability limits | Damage to the rental car, theft, most counter fees, loss of use, your own medical costs unless covered elsewhere | Yes, especially for collision damage and theft protection |
| No car insurance | Usually only what the credit card or rental contract adds | Nearly everything: rental damage, liability, theft, medical bills, and contract fees | Yes, and the rental desk or a third party may be the fastest path |
| International rental | Sometimes only a card benefit, if valid abroad | Local liability requirements, damage coverage rules, theft, medical costs, and country-specific exclusions | Usually yes, unless your policy and card clearly apply in that country |
Suppose you rent a compact car for four days and your personal policy has a $500 deductible. If the rental company’s waiver costs less than the combination of your deductible, any excluded fees, and the chance of a claim, the add-on may be easy to justify. If the fee is much higher and your card gives primary collision coverage, the desk option may be redundant.
What the rental desk sells
The rental company usually offers several add-ons at pickup. The main products are commonly damage protection, liability coverage, personal accident insurance, and personal effects coverage.
Collision damage waiver and theft protection
The collision damage waiver, or CDW, is the main counter add-on people buy. It can reduce your responsibility for damage to the rental vehicle and may also cover theft, but the exact terms vary by company and country. It can still leave some fees or charges in place depending on the contract.
Liability coverage, personal accident insurance, and personal effects coverage
Liability coverage from the rental company helps pay for injuries and property damage to others, which matters if your own policy is weak or absent. Personal accident insurance can help pay medical bills for you and passengers. Personal effects coverage can reimburse stolen items such as phones, laptops, and similar belongings.
Loss of use, towing, and admin fee gaps
Loss of use fees are charged when the rental car is out of service, and your personal auto insurance may or may not cover them depending on the policy, state, and proof requirements. Towing and administrative fees may also be excluded from a personal policy or a card benefit. Those are the charges that often surprise renters after a small accident or theft claim.
Are loss of use fees covered when you damage a rental car?
Often no. Loss of use fees are a common gap because they are tied to the rental company’s lost income while the car is unavailable, not just the repair bill. Your auto insurer, your card, or a waiver may cover some damage but still leave this charge in place.
Is third-party coverage worth it?
Third-party rental car insurance can be cheaper than the rental-counter option, and it can be worth buying when you want lower daily cost without relying on your personal policy. The tradeoff is that the claim process often depends on who sold the policy and how reimbursements are handled.
When a lower daily price may still make sense
Allianz says its OneTrip Rental Car Protector provides primary coverage up to $75,000 and costs $13 per calendar day. That can make sense for a short trip when the desk price is high and your own policy deductible is steep.
When reimbursement after payment changes the math
Some third-party policies require you to pay the rental company first, then submit for reimbursement. Others, including some policies sold by booking platforms or online brokers, may handle claims differently. That can be fine if you can float the charge and keep your paperwork. It is less useful if you want instant acceptance at the counter or want the rental company to handle the claim directly.
How to compare flexibility versus counter coverage
Counter waivers can be simpler if you want one bill and less claim work. Third-party coverage may be cheaper and broader in some cases, but it can have tighter paperwork rules. Compare vehicle class limits, country coverage, reimbursement timing, and exclusions before you book.
What to check before you book
Before you reserve the car, separate damage protection for the rental vehicle from rental reimbursement coverage for your own car being repaired. Those are different products. Car and Driver notes that rental-car reimbursement coverage depends on your policy, and it does not protect the rental car itself.
Rental reimbursement coverage versus rental-car damage protection
Rental reimbursement coverage pays for a substitute car while your own vehicle is in the shop after a covered claim. It is not the same as rental-car insurance. You can have one without the other, and confusing them can leave you either overinsured or completely exposed at the counter.
International rentals, luxury cars, one-way rentals, and business use
International rental rules can differ outside the U.S., and some countries include mandatory basic protections in the rental rate already. Extra protection may still be needed, but the value of an add-on depends on what is already included. One-way rentals, luxury vehicles, and business use can also trigger exclusions or higher rates. If you are renting abroad, assume your domestic policy and card benefit may not transfer cleanly until confirmed in writing.
Questions to confirm with your insurer and card issuer
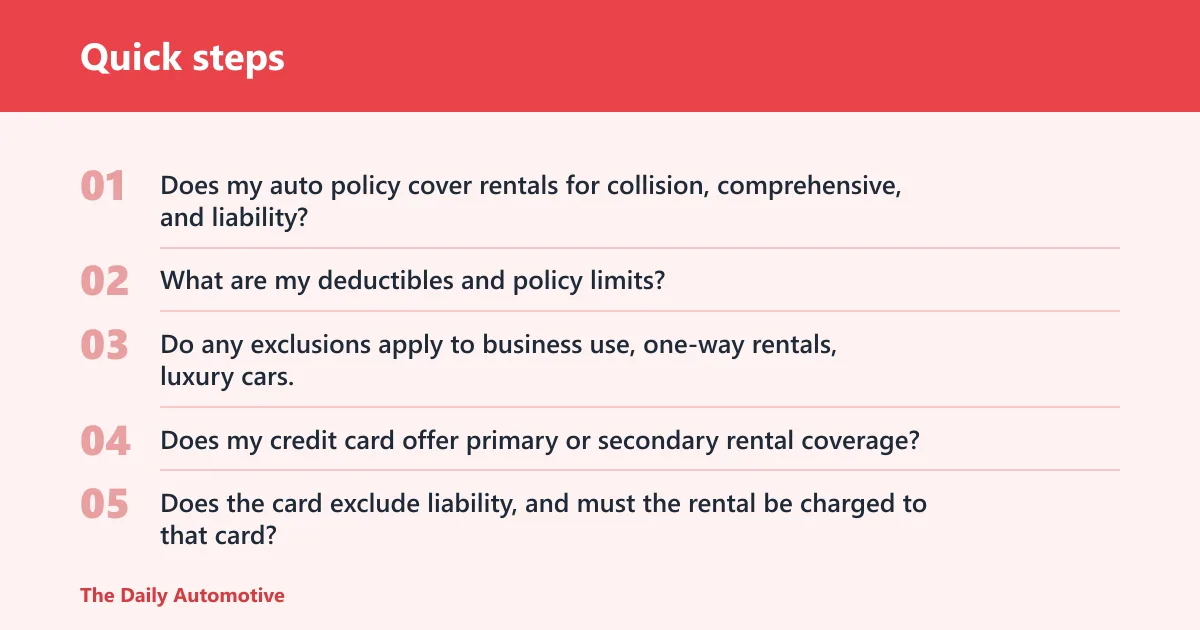
- Does my auto policy cover rentals for collision, comprehensive, and liability?
- What are my deductibles and policy limits?
- Do any exclusions apply to business use, one-way rentals, luxury cars, or international travel?
- Does my credit card offer primary or secondary rental coverage?
- Does the card exclude liability, and must the rental be charged to that card?
- Will my insurer cover loss of use, towing, or admin fees?
Can the rental company require me to buy insurance?
In the U.S., rental-car insurance is optional if you already have coverage, but a rental company can still set its own contract terms and may require proof of certain coverage or a deposit. Outside the U.S., local rules can be different, so the answer changes by country and by vehicle class.
Frequently asked questions
Do I need additional insurance for a rental car if I already have auto insurance?
Maybe not. If your personal policy already includes liability, comprehensive, and collision, you may already have the core protection for a U.S. rental. The catch is the deductible, policy limits, and exclusions. If those gaps are small enough, the add-on may be redundant.
What does rental car insurance cover that my own policy might not?
Rental-car add-ons can cover the rental vehicle itself, theft, liability from the counter, personal accident insurance, personal effects coverage, and sometimes administrative charges. Your own policy often leaves gaps in loss of use, towing, and fee recovery. It may also require you to pay the deductible first.
Does my credit card cover rental cars?
Sometimes. It is an optional card perk, not a given, and coverage can be primary or secondary depending on the card. Many card benefits exclude liability and require you to charge the rental to the eligible card. Read the benefits guide before you rely on it.
What is a collision damage waiver and do I need it?
A collision damage waiver can reduce your responsibility for damage to the rental vehicle, and it may include theft coverage too. It is often the simplest counter add-on. You may not need it if your auto policy and card already cover the car, but it can reduce claim friction.
What happens if I rent a car internationally?
Coverage rules can differ outside the U.S., and your domestic policy or card may not apply the same way. Some countries require local liability or limit what a waiver covers. For international rentals, extra coverage is often worth checking before you arrive at the counter.
Is rental car reimbursement coverage the same as rental car insurance?
No. Rental reimbursement coverage helps pay for a car while your own vehicle is being repaired after a covered claim. Rental-car insurance protects the car you are driving from the rental company. They solve different problems, and one does not replace the other.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.