Does Renting a Car Affect Your Credit Score? What Happens
A standard car rental usually does not affect your credit score unless the company runs a hard credit check, sends an unpaid balance to collections, or a disputed charge becomes delinquent. Skip the fine print, and a damage fee or no-show charge can turn into collections and hurt your score. Here’s what happens with reservations, deposits, payment methods, and unpaid rental disputes.
Does renting a car affect your credit score?
Most rentals leave your credit score alone. A routine reservation, a card authorization, and a returned car with no unpaid balance usually do not create a new account or report to the bureaus. Credit risk starts when a rental issue turns into a debt problem, especially if it reaches collections or follows a hard credit pull.
When a rental stays off your credit report
A standard rental is not the same as opening a loan. No installment account appears just because you picked up a sedan or SUV, and a security deposit is usually only a temporary authorization, not borrowed money. That means the rental itself does not normally change payment history, debt load, or credit mix.
Credit scores generally range from 300–850. The biggest score drivers are payment history, at 35% of a FICO Score, and amounts owed, not a one-time rental authorization. Credit mix accounts for 10% of a FICO Score. A rental only matters if it creates a reportable debt or inquiry.
When rental problems can turn into credit damage
Late returns, damage claims, tolls, and no-show fees do not automatically hit a credit file. The risk starts when the bill stays unpaid long enough for the rental company or a collector to report it. A disputed charge can also become a problem if the account ages into delinquency instead of being resolved.
Suppose a compact car is returned two days late and the company bills a late fee plus a cleaning charge. If the renter pays it, credit impact is usually over. If the bill sits unpaid and gets assigned to collections, the account can show up as a negative item and hurt the score.
Credit score basics for renters
A credit score is a three-digit number built from credit report data. Lenders use it for loans, cards, and other credit products. A rental counter agent is usually checking identity, payment risk, or deposit policy, which is a different process from approving a loan.
Hard inquiries can lower a credit score by a few points or more. The hit is usually temporary. For auto loan inquiries, the scoring models usually treat multiple inquiries within 14 days as one inquiry, and newer FICO Score models extend the shopping window to 45 days. That shopping rule is for auto loans, not routine rental pickups.
| Rental scenario | Likely credit impact | What to ask the counter agent before signing |
|---|---|---|
| Credit card hold | Usually no credit report impact; the card issuer may place an authorization hold | How much is being authorized, and when is the hold released after return? |
| Debit card rental | May trigger extra screening; some brands or locations check more carefully | Will a debit card change the deposit amount or require additional ID? |
| Premium vehicle | May require a larger deposit or stricter screening; credit check rules can vary | Does this vehicle class require a hard pull, soft check, or no credit check? |
| One-way rental | May bring higher fees or different approval rules, but not a score hit by itself | Are one-way fees prepaid, and does that change the payment method or deposit? |
| Prepaid booking | Usually no credit report impact; card issues can still block pickup | What happens if the card used online is declined at the counter? |
| Declined card | No score hit from the decline alone, but rental may be refused | Can another card be used, and will that require a new authorization? |
| Unpaid damage claim | Can become a collections account and hurt credit if unpaid | What documentation supports the charge, and how long before it is sent out? |
| Collections escalation | Negative credit file entry is possible; collections can remain on the report for years | Which department handles disputes before the account is transferred? |
Does a rental car company run a hard credit check?
Sometimes, but not always. Many rentals only involve identity verification and card authorization, not a hard pull. A hard credit check is more likely when the company’s policy treats the rental as higher risk, or when the payment method, vehicle class, or branch location calls for extra screening.
Identity checks versus hard pulls
A soft identity or fraud check is not the same as a hard credit inquiry. A hard inquiry is triggered by applying for credit, appears on a credit report, and can lower a score slightly for a short time. A rental reservation may involve checking whether the name, ID, and card match, without pulling a full credit file.
Do not assume every counter check is a credit inquiry. Some systems verify identity and flag fraud risk; others may review a credit file only for certain rentals. The wording matters. Ask whether the company is doing a soft check, a hard pull, or no credit check at all.
Why brand, location, and vehicle class matter
Deposit policy can vary by brand and by branch. Airport locations often follow different rules from neighborhood offices, and premium or specialty vehicles may trigger stricter approval standards. A one-way rental can also carry different screening rules because it changes where the car is returned and how much fee risk the company takes on.
Payment method matters too. A debit card, prepaid booking, or declined card can lead to extra review. A credit card usually gives the company a cleaner path for authorizing the rental deposit, but it still does not guarantee a hard inquiry will not happen if the branch policy calls for one.
How payment method can change the screening rule
Debit card vs credit card payment is a major split. Credit cards often support a temporary authorization hold with fewer hurdles. Debit cards can bring stricter fraud controls, more ID checks, and a larger deposit requirement. Some companies limit debit card rentals to certain locations or vehicle categories.
Picture a midsize rental reserved with a debit card at an airport counter. The agent may ask for a return flight, extra ID, or a different deposit than a credit-card customer would see. None of that automatically harms credit, but the added screening can make approval less predictable.
Can a car rental deposit show up on your credit report?
Usually no. A rental security deposit is commonly an authorized hold, not a loan or a new debt account. It may reduce available credit while the hold is active, but it does not normally appear as a reported balance or new tradeline.
How authorization holds work
A hold reserves funds for the rental, fuel, tolls, or incidental charges. The company is not collecting that money as a final charge unless it needs to. On a credit card, the issuer may show the available credit as temporarily lower until the hold clears. On a debit card, the bank may reserve cash from the account.
The hold is temporary. Release timing after return can vary by card issuer, company policy, and how quickly the final rental amount is closed out. That delay can be annoying, but it is not the same as a credit score hit.
Why a hold is usually not a new debt
A hold does not usually count as a collections account, a loan, or a missed payment. It only becomes a credit problem if the underlying charge turns into an unpaid balance and the company pursues it. If the renter disputes a charge, the dispute process matters more than the hold itself.
Some renters mistake a lower available limit for damage to their credit file. That is a cash-flow issue, not a reportable negative item. The score risk comes later, if the account goes unpaid and the company escalates it.
Can a rental problem become a collections account?
Yes. Damage charges, tolls, late fees, smoking fees, and no-show fees can become collections accounts if left unpaid. The rental itself is not the problem; the unpaid debt is. Once a collector gets involved, the account can affect the credit file and hurt the score.
Damage charges, tolls, and late fees
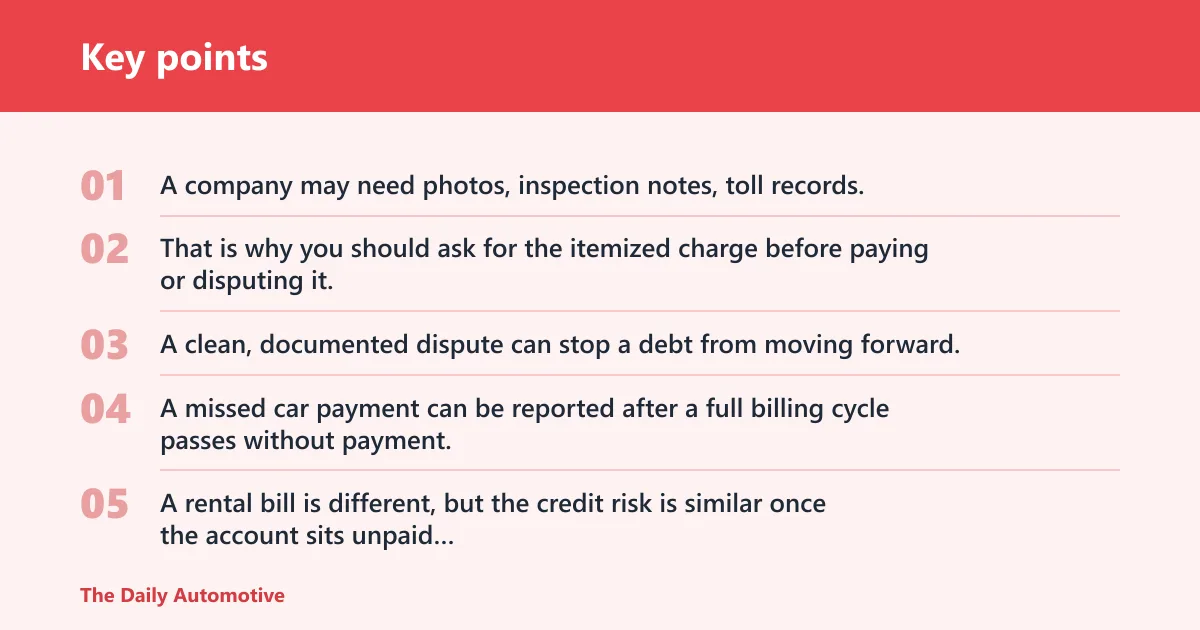
Not every charge is automatic or final. A company may need photos, inspection notes, toll records, or contract terms to support the bill. That is why you should ask for the itemized charge before paying or disputing it. A clean, documented dispute can stop a debt from moving forward.
A missed car payment can be reported after a full billing cycle passes without payment. A rental bill is different, but the credit risk is similar once the account sits unpaid long enough. If the company treats the balance as delinquent, the issue can move from a customer-service dispute to a credit reporting issue.
What happens after an unpaid bill
First, the company usually bills the renter or attempts collection internally. Next, the account may be transferred or sold to a collection agency. If that happens, the collection can be reported to the credit bureaus and remain on the report for years, depending on reporting rules and account history.
That is the point where a rental problem can become a score problem. Payment history carries heavy weight in scoring models, so a negative collection entry can do real damage. The safest move is to resolve the bill before it ages out of the company’s internal billing cycle.
How disputes and reporting timelines work
Disputes should be filed early, with receipts, photos, and the rental agreement if possible. If the company cannot resolve the issue, ask when the account becomes eligible for external collection. Once a debt is reported, correcting it can take time and documentation.
Do not wait for a collection notice if the charge looks wrong. Ask the counter agent or billing department which office handles post-rental damage disputes, and get the case number before leaving. That gives you a record if the charge later appears on a credit file.
What to ask before you sign
Ask the right questions at the counter so the deposit, screening, and return rules do not surprise you later. Most problems come from unclear payment rules, not the rental itself. A few direct questions can tell you whether the company uses a hard pull, how much it will authorize, and what happens if the card is declined.
- Ask the exact deposit amount and whether it is an authorization hold or a final charge.
- Ask when the hold is released after return and which card type releases fastest.
- Ask whether the company uses a soft check, a hard credit check, or no credit check for your booking.
- Ask how debit cards, prepaid cards, and corporate accounts are handled.
- Ask whether one-way rentals or premium vehicles change the screening rule.
- Ask what happens if a card is declined at pickup and whether a second card changes the approval path.
- Ask how credit freezes are handled if your file is locked.
Ask about debit cards, freezes, and one-way rentals
A credit freeze may block some new credit pulls, and it can interfere with certain verification checks. It does not always stop a rental, but it can complicate the checkout process if the company wants to verify identity through a bureau. If your file is frozen, ask whether a temporary lift is needed before pickup.
Debit card rentals and one-way rentals deserve special attention because policy varies by location. The safest plan is to confirm the rules before arriving, especially for a premium vehicle or a trip that ends in a different city. That reduces the chance of a refusal at the counter.
Frequently asked questions
Does using a debit card for a rental car avoid a credit check?
No guarantee. Some companies use stricter screening for debit card rentals, and some locations may still check credit or require extra ID. Debit cards can also bring larger holds or different approval rules. Ask whether the branch treats debit-card customers differently before you get to the counter.
Can renting a car hurt your credit score if you return it late or damaged?
Not automatically. The late return or damage charge only hurts credit if it becomes an unpaid debt and is reported or sent to collections. Paying the bill on time usually ends the issue. If the charge is wrong, dispute it quickly with documents before it escalates.
What happens if the rental company sends an unpaid bill to collections?
The account can be reported as a negative item, which may hurt your credit score. Collections can stay on a credit report for years, and the impact is usually worse than the original bill. Resolve the charge early if possible, and ask for written proof of any disputed damage or fee.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.