How Much Car Insurance Do I Need? Practical Coverage Guide
Most drivers should start at 100/300/100 liability, raise property damage to at least $100,000 if you own assets or drive a newer car, and keep full coverage on financed or leased vehicles until the loan is below the car’s value. Too little coverage can leave you paying a large claim or lawsuit out of pocket. This guide helps you size limits by assets, vehicle value, loan or lease status, and commuting risk.
What car insurance do you actually need?
Start with the legal minimum in your state, then add coverage based on what you could lose in a crash. Liability is the floor in most states, but the right package depends on your assets, your vehicle’s value, and whether you still owe money on the car. Minimum coverage is often too thin for a serious claim.
Separate required coverage from optional protection
Liability coverage pays for damage you cause to other people and property. Collision and comprehensive pay for your own car, but they are not required by law. Some states also require uninsured/underinsured motorist coverage, and PIP is likely required in no-fault states.
Identify the gaps minimum limits leave open
State minimum insurance requirements are a legal floor, not a target. In Texas and California, bodily injury minimums are 30,000 per person and 60,000 per accident, which can be wiped out quickly in a multi-injury crash. If your limits run out, you may have to pay the rest yourself.
How much liability coverage should you carry?
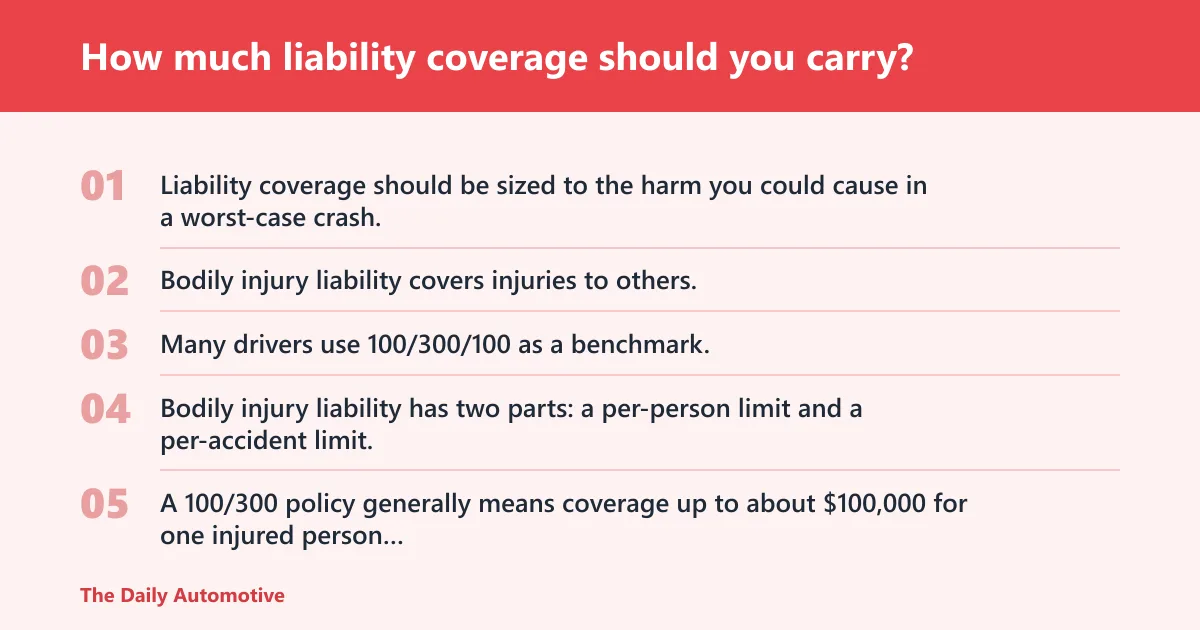
Liability coverage should be sized to the harm you could cause in a worst-case crash, not just to the cheapest legal requirement. Bodily injury liability covers injuries to others, while property damage liability covers cars, fences, buildings, and other property you damage. Many drivers use 100/300/100 as a benchmark.
What bodily injury liability limits mean
Bodily injury liability has two parts: a per-person limit and a per-accident limit. A 100/300 policy generally means coverage up to about $100,000 for one injured person and up to about $300,000 total for one crash. That matters because medical bills, lost wages, and legal claims can stack up fast after a severe collision.
How property damage liability affects your risk
Property damage liability pays for repairs or replacement of the other vehicle and any other property you strike. State minimums vary by state, and low limits can be a problem if you hit a late-model SUV, a commercial van, or a building. Higher local repair costs argue for higher property damage limits.
Why 100/300/100 is a common benchmark, not a rule
100/300/100 is a common starting point, not a universal answer. If you drive in dense traffic, carry passengers often, or own assets, higher limits can make more sense. If your state minimum is far below that level, treat the legal minimum as a floor while you price the next tier up.
How do your assets change the answer?
Your home, savings, investments, and business assets are a key driver of liability limit choice. If you cause a serious crash and your liability coverage is too low, an injured party may try to collect the unpaid amount from your assets. Renters with few exposed assets and homeowners with equity do not face the same risk.
Match liability limits to what could be exposed
Look at what you would want to protect in an at-fault lawsuit: home equity, bank balances, brokerage accounts, retirement accounts that are reachable in your state, and business assets if you own a business. If the numbers are meaningful, raise bodily injury and property damage limits above the state minimum.
Why renters and homeowners may need different limits
A renter with modest savings may still need solid liability coverage, but a homeowner usually has more on the line. A house, equity, and larger cash reserves can be pursued after a judgment. That is why many homeowners should compare quotes at 100/300/100 or higher.
When higher limits matter more than a low premium
A small premium increase can buy a large jump in protection. That matters most when the next tier shields assets that took years to build. If you own a home, have investments, or run a business, higher liability limits are often the cheapest way to protect the balance sheet.
When are collision and comprehensive worth it?
Collision and comprehensive are usually worth buying when your vehicle still has enough actual cash value to matter to your finances. For collision and comprehensive, the coverage limit is typically the vehicle’s actual cash value. If the car is worth little and the deductible is high, full coverage may stop making sense.
Use actual cash value to judge the payout ceiling
Actual cash value, or ACV, is the vehicle’s fair market value at the time of the loss. It is the usual basis for collision and comprehensive claims. That means your insurer will not pay a new-car price for an older car, only the vehicle’s current value minus the deductible.
How deductibles affect the break-even point
Higher deductibles lower the premium, but they also raise the amount you must cover before insurance pays. If a car’s ACV is around $4,000 and the deductible is around $1,000, a smaller loss may not justify a claim. Price the policy both ways: the premium and the deductible exposure.
When older-car coverage may not pencil out
If an older paid-off car has low ACV, high mileage, and a large deductible, collision and comprehensive can become poor value. A common first-timer mistake is paying for coverage that would only return a small amount after a crash. At that point, the owner may choose liability only.
What should you buy if you finance or lease a car?
If you finance or lease a car, collision and comprehensive are often required. Lenders and lessors want the vehicle protected because they have money tied to it. The exact requirement can vary by contract, so check the loan or lease agreement before you sign.
Why lenders and lessors often require full coverage
Financed and leased vehicles are usually protected against both crash damage and non-collision losses such as theft, hail, vandalism, and fire. That is why collision and comprehensive are often required when you lease or finance a car. The lender’s collateral is the vehicle itself.
How loan balance and lease terms affect coverage choices
Keep full coverage while the loan balance is still higher than, or close to, the car’s value. If the car is totaled and you owe more than ACV, gap exposure can be expensive. Lease contracts can also set deductible limits and require specific coverages, so verify those terms directly.
What to verify before you sign
- Check the lender or lease requirement for liability, collision, comprehensive, and deductibles.
- Compare the vehicle’s ACV with the remaining loan balance.
- Confirm whether the contract requires extra protection for glass, roadside help, or gap coverage.
- Price the required package before accepting the vehicle.
How do UM/UIM, PIP, and medical payments fit in?
Uninsured/underinsured motorist coverage protects you if the other driver has no insurance or too little of it. PIP covers medical expenses after a crash and is likely required in no-fault states. Medical payments coverage helps pay medical costs for you and passengers, and it can overlap with health insurance.
What uninsured and underinsured motorist coverage does
UM/UIM can pay when the at-fault driver cannot cover your losses. Some states require it, while others make it optional. It is especially useful if you are hit by a driver carrying only the state minimum, because those limits may be far below the cost of treatment and lost wages.
Where PIP is required and why no-fault states use it
PIP is common in no-fault systems and is likely required if you live in a no-fault state. It generally covers medical expenses after a crash, and in some places it can also help with lost income and related costs. State rules differ, so confirm how your state treats PIP.
How med-pay interacts with health insurance
Medical payments coverage can help with immediate bills for you and passengers, often without waiting to sort out fault. It can overlap with health insurance, but it may still be useful for deductibles, copays, or short gaps in coverage. If your health plan is strong, med-pay may be optional.
Coverage decision matrix for common driver profiles
Use this matrix as a starting point, then adjust for state rules, vehicle value, and budget. It turns the usual insurance terms into a simple choice: what must you buy, what should you likely buy, and what can you skip if the numbers no longer make sense?
| Driver profile | Liability | Collision | Comprehensive | UM/UIM | PIP / med-pay |
|---|---|---|---|---|---|
| Paid-off older car | 100/300/100 if budget allows; otherwise above state minimum | Often skip if ACV is low and deductible is high | Often skip if ACV is low and loss would not change finances much | Buy if available and affordable | Health insurance may cover most costs; med-pay optional, PIP if required |
| Financed car | At least state minimum, usually higher | Usually keep until loan is below ACV or paid off | Usually keep while lender requires it | Strongly consider | Buy required PIP; med-pay depends on health coverage and state rules |
| Homeowner with assets | 100/300/100 or higher | Based on ACV and ability to replace the car | Based on ACV and theft/weather risk | Yes, if priced reasonably | PIP or med-pay based on state and health plan |
| Renter with low assets | Above state minimum if affordable | Only if the car’s ACV supports it | Only if theft or weather risk is meaningful | Often a good value | Choose based on health insurance and state rules |
| High-mileage commuter | 100/300/100 or higher | Often yes if the car still has meaningful ACV | Often yes for theft, hail, and road exposure | Yes | PIP or med-pay may help with frequent-collision exposure |
How to compare deductibles, vehicle value, and quote prices
Price the same liability limits across several insurers, then compare collision and comprehensive with different deductibles. A higher deductible can make full coverage cheaper, but only if you can absorb the out-of-pocket cost after a claim. The key question is whether the premium fits the protection gap you are closing.
Frequently asked questions
How much car insurance do I really need if I own my car outright?
If you own the car outright, start with strong liability limits and then decide whether the car’s value justifies collision and comprehensive. If the vehicle is older and worth little, liability-only coverage may be enough. If it still has meaningful value, full coverage can still make sense.
Is state minimum car insurance enough for most drivers?
Usually no. State minimum insurance requirements are the legal floor, and they can be far too low after a serious crash. Liability is required in most states, but a major injury claim can exceed those limits quickly, especially if multiple people are hurt.
How much liability coverage should I carry beyond the legal minimum?
Many drivers use 100/300/100 as a starting point. From there, increase limits if you own a home, have savings or investments, or drive in higher-risk traffic. Property damage liability should also reflect local repair costs and the price of modern vehicles.
Do I need collision and comprehensive coverage on an older car?
Only if the car’s ACV is high enough to justify the premium and deductible. For an older paid-off car with low market value, those coverages may not pencil out. If a claim would only pay a small amount after the deductible, many drivers drop full coverage.
What car insurance do I need if I finance or lease a vehicle?
Financed or leased cars often need collision and comprehensive. Check the contract for exact requirements, including deductible caps and any gap coverage terms. Keep full coverage until the loan balance drops below the car’s value or the lease ends.
How do my assets affect how much car insurance I should buy?
Assets raise the cost of being underinsured because they can be exposed in an at-fault lawsuit. If you have home equity, savings, investments, or business assets, higher liability limits are usually worth a close look. The more you have to protect, the less attractive bare minimum coverage becomes.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 Half Car Cover SUV,Top Cover with Red Reflective Strip, Hail Protector Car Cover with Cotton Liner, Sunroof & Windshield Cover for Ice and Snow, All Weather Car Body Cover for Sun, Rain, Dust
 Car Cover for Hail Protection, Thickened Multi-Layer, Waterproof, Hail Cover for Car SUV Size A6 Fit for Toyota RAV4 /4Runner, Honda CRV, Hyundai Santa Fe, Audi Q5 (182-190 inch)