Is a Car Rental Business Profitable: Unlocking Lucrative Opportunities
A car rental business can be profitable, but only when utilization stays high, repair losses stay controlled, and monthly fixed costs are covered with margin. If you underprice cars or let downtime rise, the fleet can look busy while cash runs negative. This guide breaks down startup costs, revenue ranges, break-even math, and which rental models tend to work best.
What separates profitable fleets from losing ones
Yes, but profitability depends on the numbers, not hope. A fleet can produce solid gross revenue and still miss net profit if insurance, repairs, registration, staff, and downtime eat the spread between what customers pay and what each car costs to keep available.
When the model makes money
Profit usually shows up when three variables line up: utilization stays near or above a practical target, average daily rate holds without heavy discounting, and fixed overhead is spread across enough active vehicles. A useful benchmark is about 70% utilization, paired with pricing close to a $50 ADR in many mainstream markets.
That benchmark is not a promise. It is a planning anchor. A fleet with steady bookings, controlled accident claims, and predictable maintenance can turn decent top-line revenue into net profit. The same fleet can lose money if one weak line item spikes for a few months.
When profit disappears on paper
Profit often vanishes when the fleet is technically rented, but not efficiently rented. Too many discount bookings, long turn-around times, or cars sitting idle after minor damage can make revenue look acceptable while cash flow tightens. Insurance spikes are especially painful because they hit every unit, not just the ones on the road.
Car rental profit drivers
Three drivers matter most: utilization rate, average daily rate, and fleet mix. Add-ons help, but they rarely rescue a weak core model. The business works best when the fleet earns often, prices sensibly, and avoids long idle stretches between bookings.
Utilization rate and average daily rate
Utilization is the percentage of the fleet rented out. It drives revenue directly and also affects break-even speed because fixed costs are easier to absorb when more cars are billed more often. A car that earns at a modest rate for many days usually outperforms a higher-priced car that sits unused.
ADR is the daily rental price per vehicle. It changes by market and car class. Economy cars usually support lower ADRs but simpler costs, while luxury and exotic units can command higher rates with more severe capital risk if demand softens.
Fleet size and vehicle mix
Fleet size changes everything. Small fleets of 5–10 cars can be easier to start and manage, but each vehicle carries a bigger share of overhead. Medium fleets of 20–50 cars can often spread fixed costs better. Large fleets of 50+ cars can often scale revenue, but they may also increase capital needs and operational complexity.
Vehicle mix matters too. Economy cars usually carry thinner pricing power but often have lower exposure to cost shocks. SUVs can bring stronger daily rates. Luxury and exotic units can post high gross margins in some cases, but their demand is less forgiving and downtime is more expensive.
Add-ons and ancillary revenue
Ancillary revenue can add meaningful income. GPS units, child seats, insurance packages, fuel plans, and other add-ons raise average transaction value. They do not replace utilization, but they can widen the gap between gross revenue and break-even by improving revenue per rental day.
For a small fleet, add-ons often matter most when bookings are already steady. They are a margin tool, not a demand fix. If demand is weak, add-ons alone will not cover insurance and depreciation.
Car rental cost structure
Startup costs and operating costs deserve separate treatment. Startup capital covers the vehicles, permits, deposits, software, branding, and working cash. Operating costs cover the monthly drag that determines whether the business stays profitable after the fleet is on the road.
Startup costs and vehicle acquisition
One competitor says startup capital can be as low as $60, but that figure is not a realistic fleet-start number for most operators because vehicle acquisition is usually the largest upfront item. Buying cars requires more cash up front. Leasing can lower the initial outlay, but it changes payback timing and monthly commitments.
Vehicle acquisition often decides whether the business survives its first slow season. A low-capital setup may work for a single listing or a peer-to-peer model with one owned vehicle, but a multi-car operation needs enough cash to cover insurance, registration, and repairs before revenue stabilizes.
Insurance, maintenance, and registration
These are the cost lines that most often break the model. Insurance can jump after claims or when the fleet expands. Maintenance and repairs rise with mileage, accidents, and older units. Registration and licensing are easier to forecast, but they still scale with fleet count.
Downtime is another hidden cost. A car that waits for body work earns nothing while still carrying insurance and depreciation pressure. Accident-related costs can wipe out several weeks of profit from one vehicle.
Staffing, marketing, and software
Staff salaries and training matter once the fleet gets beyond owner-operator size. Marketing and advertising can be light in the beginning, then become a constant expense if you rely on paid demand. Software costs are smaller than vehicle costs, but they matter because they support bookings, turnarounds, and fewer manual mistakes.
An effective technology stack usually includes online booking platforms, fleet management software, GPS tracking, and contactless rentals or automated check-in. Those tools help reduce friction, improve dispatch, and cut idle time. They do not compensate for a weak market or bad pricing.
Profit stress test by fleet size
Here is a simple planning table for three fleet sizes. The numbers are scenario assumptions, not promises. They show how utilization, ADR, and overhead can push the same business above or below break-even.
| Fleet size | Assumed utilization | ADR | Monthly revenue | Estimated operating costs | Break-even status |
|---|---|---|---|---|---|
| 5 cars | 55% | $45 | $3,713 | $4,200 | Below break-even |
| 20 cars | 70% | $50 | $21,000 | $18,500 | Above break-even |
| 50 cars | 75% | $55 | $61,875 | $56,000 | Thin profit, close to break-even |
The break-even line moves fastest when insurance, maintenance, and accident downtime rise together. Marketing can also break the model if customer acquisition costs climb while pricing stays flat. Staff costs matter most as the fleet grows and turnover rises.
Say your 5-car fleet rents mostly economy sedans in a local market. If utilization slips from 70% to 55% because one car waits on repairs, monthly revenue drops quickly, but insurance and storage costs do not drop with it. The fleet can still feel active while cash turns negative.
How much can a car rental business make per year?
Annual earnings vary by fleet size, market type, and pricing discipline. Small fleets can make modest income, medium fleets can support a full operating business, and larger fleets can scale revenue if the operator controls capital costs, repair cycles, and booking quality.
Small fleet earnings
One source estimates small fleets can generate $75,000–$250,000 in annual revenue, with small-fleet net profit margins at 12%–18%. Another competitor says average annual revenue is $65.2K, with monthly revenue at $5.44K and average weekly revenue around $1.36K. Those numbers are useful as reference points, not guarantees.
Medium fleet earnings
Medium fleets are described as 20–50 cars, and the same source estimates annual revenue at $300,000–$1.1M. That range makes sense because more cars can spread fixed costs, but only if the operator keeps utilization high and avoids letting the fleet grow faster than demand.
Large fleet earnings
Large fleets are described as 50+ cars. At that scale, revenue can rise quickly, but overhead, financing costs, staff needs, and insurance exposure rise too. The bigger the fleet, the more important it becomes to have tight dispatch systems and reliable demand channels.
What is the real profit margin?
Profit margin depends on which margin you mean. Gross margin measures revenue after direct vehicle-related costs. Net profit margin measures what remains after all operating costs, overhead, and losses. A business can show a healthy gross margin and still produce a weak net margin.
Gross margin versus net margin
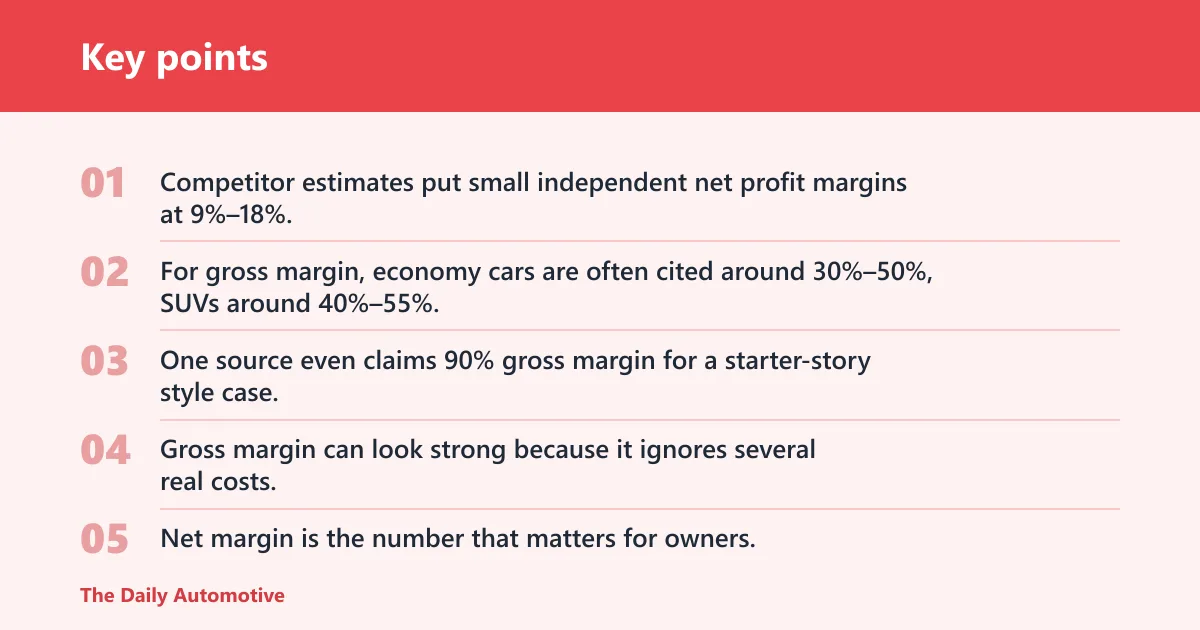
Competitor estimates put small independent net profit margins at 9%–18%, while another source cites 5%–25% depending on model. For gross margin, economy cars are often cited around 30%–50%, SUVs around 40%–55%, and luxury or exotic fleets around 60%–70%. One source even claims 90% gross margin for a starter-story style case, which should be treated as an outlier rather than a planning standard.
Gross margin can look strong because it ignores several real costs. Net margin is the number that matters for owners. It shows whether the business can pay for claims, payroll, marketing, and debt while still leaving profit.
Why margins vary by segment
Owner-operators often run leaner and can protect margin if they keep the fleet small and close to demand. Peer-to-peer fleets may have lower overhead, but they can face uneven utilization and platform fees. Airport-focused operators may enjoy stronger pricing but also face higher access costs and more intense competition.
Franchise-style operators can benefit from systems and brand recognition, yet they usually carry higher fixed commitments. That can help in strong demand periods and hurt badly when volume dips.
How to improve utilization and margins
The most effective profit work is practical: raise utilization, trim downtime, and choose a fleet mix that fits the market. Price matters, but pricing alone will not rescue a fleet that spends too much time off the road.
Pricing and demand management
Dynamic pricing can help during peak travel periods and soften during slow periods, but the goal is not to chase every booking. The goal is to protect average transaction value while keeping cars moving. A good price is one that fills the calendar without erasing margin.
Tourism, business travel, and seasonal demand still matter. A local market with weekday corporate traffic may support different pricing than an airport operation that spikes on weekends and holidays.
Fleet mix and downtime control
Choose the fleet mix with repair cost and demand resilience in mind. Economy cars can be easier to keep in service. SUVs may earn more per day. Luxury units can be profitable in the right location, but they can sit longer if demand weakens. Fast turnaround after returns is just as important as the car class.
Suppose a 20-car fleet shifts two units from older sedans to newer SUVs in a market with family travel. If those SUVs hold higher ADR and stay booked, revenue rises. If they sit idle because the market is price-sensitive, the financing and insurance costs can outweigh the benefit.
When buying beats leasing
Buying usually helps when you want lower long-run monthly pressure and can tolerate larger upfront cash needs. Leasing can help if preserving cash is the priority and the market has reliable demand, but lease payments can shorten the runway if utilization slips. Buying often improves payback timing once the fleet is stable.
For a startup, the better choice depends on cash flow. For a mature fleet with proven demand, ownership can improve long-term economics. For a thin-margin market, leases can create too much fixed pressure unless bookings are very consistent.
How many cars do you need to break even?
There is no universal fleet count that guarantees break-even. The better question is how many revenue-producing rental days are needed to cover fixed costs. A business with low overhead may break even with fewer cars. A business with high insurance, payroll, and lease payments may need far more.
Break-even logic
Use break-even as a planning metric, not a guarantee. A common example is a 50-car fleet rented 20 days each month. If fixed costs and variable costs stay under the income from those rental days, the business can clear break-even. If insurance or repairs rise, the threshold moves upward immediately.
Why fixed costs matter more than fleet count
Fleet count matters because it changes revenue capacity, but fixed costs decide how much revenue is required before profit starts. A 5-car fleet with low overhead can outperform a larger fleet that carries heavy payroll and costly parking. The right target is not a car count. It is a cost structure that the market can support.
Frequently asked questions
Is a car rental business profitable?
Yes, it can be profitable when utilization stays high, pricing is disciplined, and insurance and repairs are controlled. The business becomes much less attractive when cars sit idle, accident costs rise, or fixed overhead is too heavy for the size of the fleet.
How much money can a car rental business make per year?
Profit is lower than revenue, of course, because insurance, maintenance, staff, and marketing all take a cut before owners see net earnings.
What is the average profit margin for a car rental business?
Small independent operators are often estimated at 12%–18% net profit margin, while another source gives a broader 5%–25% range depending on the model. Gross margin is higher than net margin, so do not confuse the two when comparing businesses.
How much does it cost to start a car rental business?
Startup cost can be low for a very small, asset-light setup, and one competitor says as low as $60. For a real fleet, vehicle acquisition is usually the largest upfront expense, followed by insurance, registration, software, and working cash for the first few months.
How many cars do you need to break even in a car rental business?
There is no fixed number. Break-even depends on fixed costs, vehicle type, utilization, and daily price. A 20-car fleet can break even in one market while a 10-car fleet misses it in another if insurance, payroll, or financing costs are too high.
Is leasing or buying cars better for a rental business?
Buying usually improves long-term economics if you have enough capital and can handle repair exposure. Leasing can reduce upfront cash needs, but it raises fixed monthly pressure. If demand is uncertain, leasing can hurt break-even timing faster than ownership does.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.