Can You Finance A Car Without Social Security
Some lenders may let you finance a car without a Social Security number if they accept an ITIN or passport-based ID, and some may also consider Social Security income alone if the benefits are documented and appear sufficient to cover the payment. Bad fits lead to denials, higher rates, larger down payments, or a loan you cannot support. This guide explains which lender types fit each case, what papers they ask for, and how your credit profile changes the path.
How lenders evaluate identity versus repayment
Yes, but the real question is which lenders will accept your identity documents and which will accept your income documents. An SSN issue is an identity issue. A Social Security income issue is a repayment issue. Lenders often treat those separately.
What lenders are really checking
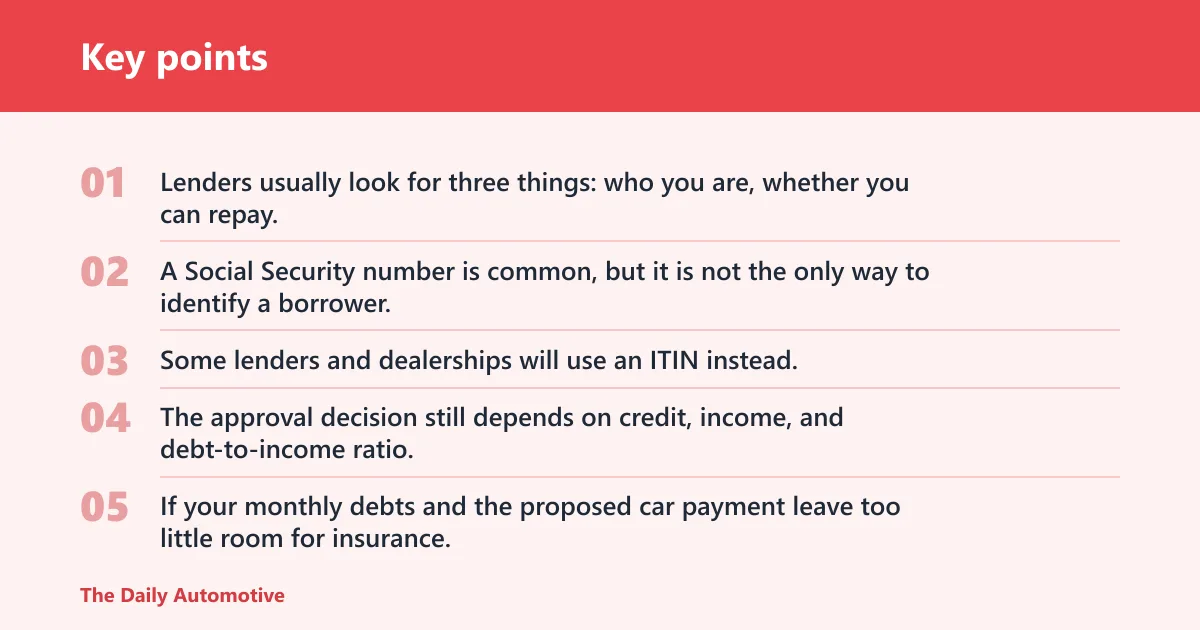
Lenders usually look for three things: who you are, whether you can repay, and whether the loan amount fits the car and the risk. A Social Security number is common, but it is not the only way to identify a borrower. Some lenders and dealerships will use an ITIN instead, and some will also accept passport-based identification with other supporting documents.
The approval decision still depends on credit, income, and debt-to-income ratio. If your monthly debts and the proposed car payment leave too little room for insurance, fuel, taxes, and fees, the lender may say no even if your identity documents are in order.
Why an SSN is not the same as proof of income
An SSN helps identify you, but It does not prove you can pay. A lender can still reject an applicant with complete identity paperwork if the income is too low, too hard to document, or already tied up in other obligations.
That separation matters for borrowers on fixed benefits. Retirement income, SSDI, and SSI may all be countable in some lending decisions, but lenders may document and underwrite them differently.
Where ITIN-based applications fit
For borrowers without an SSN, an Individual Taxpayer Identification Number is a common alternative identifier. Some dealerships and lenders accept an ITIN for financing or leasing in place of an SSN. Sansone Toyota says financing or leasing without a Social Security number is possible with an ITIN, and it frames the ITIN as the alternative for customers with no Social Security number.
Sansone Toyota also says an ITIN is an IRS-issued identifier used by foreigners working in the U.S., and it recommends building credit after getting one. That does not mean every lender will accept it. It means the path exists, especially when your credit file, address history, and income are strong enough to support the deal.
Social Security income and auto loans
Yes, Social Security income can count toward auto-loan approval, but it is not treated the same way by every lender. Retirement benefits, SSDI, and SSI can each be reviewed differently. The key is whether the lender can verify the benefit and whether the total monthly obligation still fits your budget.
Retirement benefits
Social Security retirement benefits can count as verifiable income if the lender is satisfied with the documents and the debt load is manageable. Mytips says retirement or disability benefits can count toward financing decisions. That usually means the lender will look at the benefit amount, the stability of the payment stream, and the rest of your monthly obligations.
SSDI income
Social Security Disability Insurance is monthly benefit income, and some lenders will accept it if you can document it clearly. SSA paperwork or bank deposits are the usual proof. Auto Credit Express says Social Security can count as income for a car loan, and it notes that subprime lenders often want monthly income of $1,500 to $2,000 before taxes from one source.
That does not mean SSDI always qualifies you. It means the lender may see a stable benefit stream as acceptable if the payment is modest enough and your other debts are limited.
SSI income
Supplemental Security Income is often treated differently from SSDI. It is fixed-benefit income, and some lenders are cautious because it may leave very little room for a car payment after rent, insurance, and daily expenses. If a lender accepts SSI, it usually wants the benefit documented clearly with an SSA award letter or benefit verification and recent bank statements.
The same source says earned income is different from Social Security, which it calls unearned income. It also says Social Security income alone can block approval with a subprime lender. That is why SSI applicants often need a lower payment, a larger down payment, or a co-borrower.
What lenders want to see on paper
Expect lenders to ask for an SSA award letter or benefit verification, recent bank statements showing the deposits, a driver’s license or state ID, proof of address, and your ITIN if you do not have an SSN. If the lender needs to match deposits to the award amount, the bank statements matter as much as the award letter.
What if you have no SSN?
If you have no SSN, an ITIN is often the cleanest substitute, but approval is not automatic. Lenders also want a stable address, proof that you control the bank account receiving the income, and enough documentation to tie your identity to the application. Some dealers will still decline if the file is thin or the car payment is too high.
Identity documents that usually matter
- ITIN or other tax ID
- Driver’s license or state ID
- Proof of address, such as a utility bill or lease
- Recent bank statements
- SSA award letter or benefit verification if the income is from Social Security
When a dealer still may say no
A dealer may turn down the deal if the car is too expensive for the income, if your proof of residence is weak, or if your bank statements do not match the declared benefit. A common first-timer mistake is assuming an ITIN alone solves the file. It does not. It solves the identifier gap, not the repayment gap.
Suppose your income is only SSI and the lender sees a $390 monthly payment plus full coverage insurance. If that pushes your obligations too high, the lender may decline even with perfect identity documents. The fix is usually a cheaper car, a larger down payment, or a different lender type.
Which financing route fits your situation?
The best lender path depends on whether your problem is missing identity, limited income, thin credit, or all three. Use this matrix to match your document set to the most likely lender type and the risk level you are taking.
| SSN status | Income type | Credit profile | Likely lender type | Key documents | Approval risk |
|---|---|---|---|---|---|
| No SSN, ITIN available | Wages or Social Security retirement | Good or fair credit | Credit union or community lender | ITIN, ID, proof of address, bank statements, pay stubs or SSA award letter | Moderate |
| No SSN, ITIN available | SSDI only | Thin credit | Community lender or in-house dealer | ITIN, ID, proof of address, SSA award letter or benefit verification, recent bank statements | High |
| No SSN, ITIN available | SSI only | Poor or thin credit | Buy here pay here dealership | ITIN, ID, proof of address, SSA award letter, bank statements | High |
| No SSN, no ITIN yet | Wages or benefits | Fair credit | Some dealers with alternative ID policies | Passport, ID, proof of address, income proof, bank statements | High |
| SSN absent in file, co-signer available | Social Security retirement or SSDI | Thin credit | Credit union, community lender, or standard lender with co-borrower | Co-borrower ID and income proof, SSA award letter, bank statements, address proof | Moderate |
| SSN present | Social Security retirement | Fair credit | Credit union or mainstream lender | SSN, ID, SSA award letter, bank statements, proof of address | Moderate |
| SSN present | SSDI only | Limited credit history | Subprime lender or community lender | SSN, SSA award letter, bank statements, proof of address, ID | Moderate to high |
| SSN present | SSI only | Thin credit and low reserves | Buy here pay here dealership | SSN, SSA award letter, bank statements, proof of address, ID | High |
| SSN present | Fixed income plus small side income | Good or fair credit | Credit union | SSN, ID, proof of address, bank statements, income proof | Moderate |
| SSN present | Thin credit with used-car budget | Thin credit | Credit union, community lender, or in-house dealer | SSN, ID, proof of address, bank statements, proof of income, down payment | Moderate to high |
Can a co-signer help?
Yes. A co-signer or co-borrower can improve approval odds when the primary income is nontraditional, fixed, or too small to stand on its own. The same source says a cosigner or co-borrower may help if their income is garnishable. That extra income can make the loan easier to justify for the lender.
Co-signer vs. co-borrower
A co-signer promises to repay if you do not. A co-borrower is usually on the loan from the start and shares responsibility for the payment. In both cases, the lender may count that person’s income in the file, which can matter a lot if Social Security income is your only income source.
When this route is worth using
Use this path when your own file is close but not strong enough on its own. If the payment works only when another borrower’s income is added, that is a sign the loan amount is too high for a solo application. Do not use a co-borrower to stretch into a vehicle that will strain both budgets.
What documents do lenders want?
Lenders usually want a clean paper trail that connects your identity, your address, and your income. For Social Security income, that means an SSA award letter or benefit verification plus bank statements that show the deposit history. For no-SSN applications, the identity file matters just as much as the income file.
- Gather your ID, ITIN if you have one, and proof of address.
- Print or download your SSA award letter or benefit verification.
- Collect recent bank statements that show the benefit deposits.
- Add any other income proof, such as wages or retirement benefits.
- Bring down payment information if you plan to reduce the loan size.
How to improve approval odds
Start with the payment, not the car ad. A larger down payment lowers the loan amount and the monthly bill. A cheaper used vehicle can do the same thing, and that matters because fixed-income borrowers have less margin for insurance, taxes, fees, and repairs.
The same source says buy here pay here dealerships operate as both dealerships and lenders, often do not check credit, and focus on whether you can afford the payments. That can help when documents are unusual, but it is not a free pass. Rates, terms, and vehicle condition can be less favorable than at a credit union or community lender.
Practical steps
Keep the proposed payment inside a debt-to-income range that leaves room for ownership costs. The same source says lenders commonly want total monthly obligations to stay within about 40% to 50% of income. If your benefit income is fixed, that range matters even more because there is no overtime to absorb a higher bill.
Picture a buyer on SSDI who wants a small used sedan. If the down payment trims the loan enough to lower the monthly bill, the lender may view the file differently than it would with a newer SUV and a longer term. The car choice can change the approval path more than the ID card does.
Frequently asked questions
Can you finance a car without a Social Security number?
Yes, some lenders will finance a car without an SSN if you can provide an ITIN or another acceptable form of identification. Approval still depends on income proof, credit, address history, and the size of the payment. If those pieces are weak, the lender may decline or ask for a larger down payment.
Can you finance a car with no Social Security?
Yes, but the lender has to accept your alternative identifier and your income file. ITIN-based financing is the most common path, and some dealers will also consider passport-based ID with other records. The loan still has to fit your budget, especially if your income is fixed.
Can you finance a car with Social Security income?
Yes, Social Security retirement, SSDI, and sometimes SSI can count as income for an auto loan. The lender will want proof through an SSA award letter, benefit verification, and bank statements. Approval is more likely when the payment is modest and your other debts are limited.
Do you need your Social Security card to finance a car?
Not always. Some lenders want an SSN, but others will accept an ITIN or other identity documents instead. What matters is whether the lender can verify your identity and income. If you do have a Social Security card, it can help with the file, but it is not the only path.
Can you get a car loan on Social Security?
Yes, if the lender accepts the benefit as verifiable income and the debt-to-income ratio works. Retirement and SSDI are often easier to document than SSI, but no benefit type guarantees approval. The vehicle price, payment size, and insurance cost all affect the decision.
What documents do lenders accept instead of an SSN?
Common substitutes include an ITIN, a passport, a driver’s license or state ID, proof of address, bank statements, and income proof such as an SSA award letter. Some lenders may ask for more, especially if the credit file is thin or the income is nontraditional. The exact list depends on the lender.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.