How Much Car Can You Afford on Your Salary?
A safe rule is to keep total car costs at or below 15% to 20% of take-home pay, with the monthly payment closer to 10% if your budget is tight. Go higher, and insurance, fuel, repairs, and depreciation can squeeze your cash flow. This guide shows how to turn salary into a monthly payment ceiling and a total car budget. (Thedrive)
This guide is part of our Car Dealer Money Guide: Negotiating, Financing, Leasing, Trading In and Selling series.
How much car can you afford?
Start with monthly take-home pay, not the sticker price. A car budget that fits your net income leaves room for insurance, fuel, maintenance, registration, and parking, which can turn an otherwise manageable payment into a strain. A simple ceiling is 10% of take-home pay for the loan payment, then 15% to 20% for the full monthly ownership cost.
Set a payment ceiling you can live
If your budget is already tight, use the lower end of that range. The payment is only one part of the bill, and a larger loan payment can crowd out savings or raise the risk of late payments. A five-year loan equals 60 months of payments, so even a small jump in rate or term can add up fast.
Leave room for insurance, fuel, and repairs
Do not use your entire take-home pay for the car payment. The real monthly cost should include insurance, fuel, routine maintenance, registration, and a buffer for repairs. If you commute far, drive a larger vehicle, or pay high insurance rates, the ownership cost ceiling matters more than the payment alone.
Say your take-home pay is $3,000 a month. A 10% payment cap would be about $300, but a safer all-in car budget might stay around $450 to $600 once insurance and fuel are included. That gap is why monthly affordability beats sticker-price shopping.
Salary to car budget table
This table works backward from gross salary to a realistic monthly budget. The take-home pay ranges are estimates because payroll taxes, health premiums, retirement deductions, and state taxes vary. The sample purchase prices assume a standard auto loan, a 7% sales tax, and a down payment or trade-in that covers part of the upfront cost.
| Gross annual salary | Estimated monthly take-home pay range | Safe car payment ceiling | Estimated all-in ownership cost ceiling | Sample max purchase price, 48 months | Sample max purchase price, 60 months |
|---|---|---|---|---|---|
| $35,000 | $2,250–$2,450 | $225–$245 | $338–$490 | About $11,500 | About $13,000 |
| $50,000 | $3,050–$3,350 | $305–$335 | $458–$670 | About $16,500 | About $18,500 |
| $65,000 | $3,900–$4,250 | $390–$425 | $585–$850 | About $21,000 | About $24,000 |
| $100,000 | $5,900–$6,500 | $590–$650 | $885–$1,300 | About $33,500 | About $38,000 |
These purchase-price examples assume a smaller loan with a down payment, and they are not the same as the total cost of ownership. A longer term can make the monthly payment look easier while raising total interest paid. Interest increases the cost of a car, so the payment alone can hide the real price.
How to use the table in under five minutes
- Find your gross annual salary row.
- Check the estimated monthly take-home pay range, not just the salary.
- Keep the payment near 10% of take-home pay if you want more breathing room.
- Add insurance, fuel, maintenance, and registration to test the full monthly cost.
- Use the 48-month and 60-month figures to see how the loan term changes the price you can carry.
Gross salary vs take-home pay
Gross annual salary is your pay before taxes and deductions. Net income is the money left after those deductions, and it is the better starting point for a car budget because it matches the cash available each month. A buyer with a strong gross salary can still be overextended if benefits, taxes, child care, rent, or debt payments already take a large share of take-home pay.
Why gross income is only a starting point
Gross salary helps set a purchase ceiling, but it does not tell you what is safe to spend every month. Payroll taxes, retirement contributions, health insurance, and state tax rates can change take-home pay enough to shift the answer by hundreds of dollars. That is why a car payment based only on gross income can be too high.
When net income gives a more accurate budget
If your deductions are large, or your budget is already stretched, use net income first. That is the more realistic number for payment planning because it reflects actual cash flow. A car loan that looks fine on paper can still feel tight if you are already committing too much of your monthly net income elsewhere.
How loans change the number
Auto loans change affordability in four major ways: interest rate, loan term, down payment, and sales tax. The rate depends on credit score and lender pricing, and it can change the total vehicle cost even when the sticker price stays the same. A longer term lowers the monthly payment but usually raises total interest paid.
Interest rate and credit score
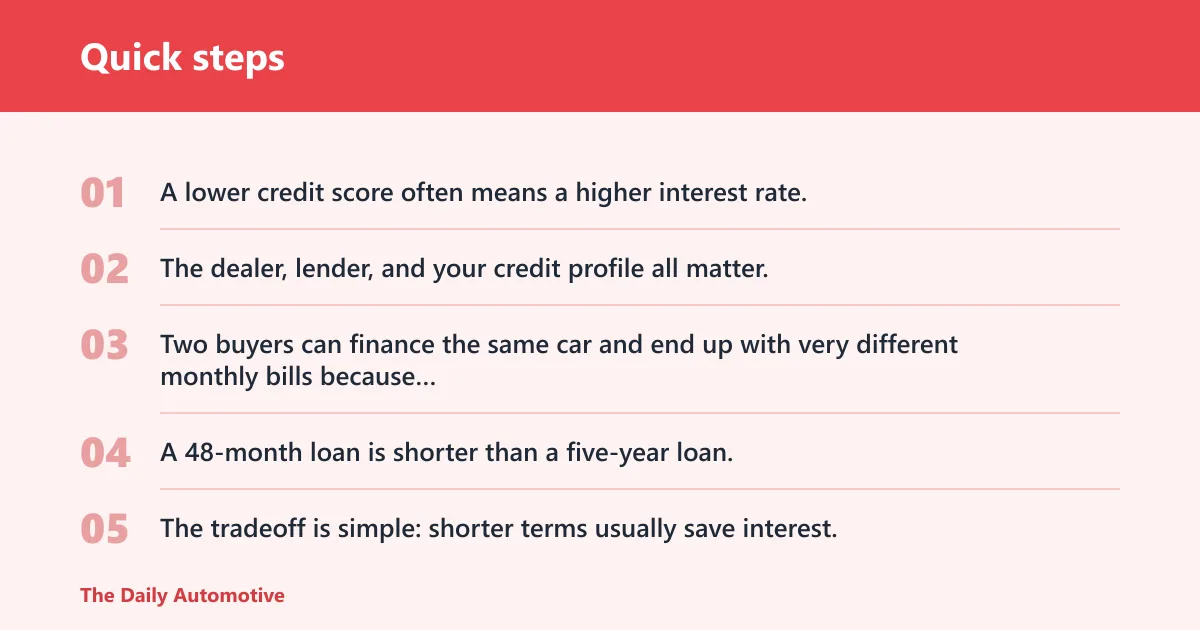
A lower credit score often means a higher interest rate, and a higher rate means more of each payment goes to interest instead of principal. The dealer, lender, and your credit profile all matter. Two buyers can finance the same car and end up with very different monthly bills because the rate changed the math.
Loan term and total interest paid
A 48-month loan is shorter than a five-year loan, so the monthly payment is usually higher. The tradeoff is simple: shorter terms usually save interest, while longer terms usually cost more over time. A longer term can also leave you upside down on the loan longer if the car loses value faster than you pay it down.
Down payment, trade-in value, and sales tax
Down payment and trade-in value reduce the amount financed, which can make the payment easier to manage. Sales tax must be included in the loan math, and depending on location and lender, it may be financed or paid at signing. That means your real cash need can be higher than the sticker price suggests.
Suppose a buyer targets a $24,000 car and puts $3,000 down with a $2,000 trade-in. That does not make the car “cheap.” It simply reduces the financed amount. If sales tax, title, and fees are added to the loan, the final monthly cost can still climb beyond the original target.
Can you afford more on 50k or 65k?
A 65k salary usually supports a noticeably higher car budget than a 50k salary, but the gap is smaller than many shoppers expect once taxes, insurance, and loan terms are included. If your budget already has heavy rent, child care, or debt payments, start below the maximum. The safest choice is the car that leaves room after every fixed bill is paid.
What a 50k salary usually supports
On a 50k salary, a practical payment ceiling often lands around the low-$300s per month, with all-in ownership closer to the mid-$400s to about $670 depending on insurance and driving costs. That usually points to a modest used car or a lower-priced new vehicle with a strong down payment.
What a 65k salary usually supports
On a 65k salary, the payment ceiling can rise into the upper-$300s to low-$400s, and the monthly ownership budget can reach the high-$500s to around $850. That opens more vehicle choices, but it does not make every higher-priced model sensible. A long loan can still produce a payment that looks affordable while raising total interest.
When to start below the maximum
If your emergency fund is thin, your commute is long, or your existing debt already takes a large chunk of net income, choose a lower number than the table suggests. A common first-timer mistake is spending up to the maximum payment and then having no room for tires, higher fuel costs, or a surprise repair.
Buying vs leasing
Leasing can produce a lower monthly payment than buying, which is why it often looks easier on paper. But lease payments do not buy equity, and the contract usually brings mileage limits, wear charges, and end-of-lease costs. Buying is often the better fit if you drive a lot or want to keep the car for many years.
Why lease payments can look lower
A lease payment covers depreciation during the lease term, not the full vehicle price. That is why the monthly outlay is often lower than a loan payment for the same model. The tradeoff is that you give the car back unless you buy it at lease end, and any excess wear or mileage can add to the bill.
Mileage limits and end-of-lease costs
Lease contracts usually include a mileage cap. If you exceed it, the extra charges can erase part of the monthly savings. End-of-lease fees, disposition fees, and wear-and-tear charges can also change the real cost, so a lower monthly payment is not the same thing as lower total cost.
When buying is the better fit
Buying usually fits better if you want to drive beyond the mileage limit, keep the car after the loan ends, or avoid lease-end charges. It can also be better if you plan to pay the vehicle off and keep ownership costs low for several more years. Leasing can work, but only if the lower payment matches your driving pattern and budget.
Frequently asked questions
How much car can I afford based on my income?
Use take-home pay first, then cap the payment near 10% of monthly net income if you need room in the budget. A broader ownership limit of 15% to 20% of take-home pay is more realistic once insurance, fuel, maintenance, and registration are included.
How much car can I afford based on annual salary?
Annual salary is a starting point, not the final answer. Divide gross pay into monthly take-home pay, then test whether the payment, insurance, and fuel fit comfortably. Salary alone can mislead you if taxes and deductions take a big bite out of cash flow.
How much car can I afford based on net income?
Net income is the better number for budget planning because it reflects what actually reaches your account. A safe approach is to keep the payment near 10% of monthly take-home pay and the full ownership cost within 15% to 20%, depending on other obligations.
How much car loan can I afford with my salary?
The loan amount depends on your salary, loan rate, term, down payment, trade-in, and sales tax. A higher salary can support a larger loan, but only if your other monthly costs leave room. A lender may approve more than you should comfortably borrow.
How much car can I afford on a 50k salary?
That budget usually works best if insurance is moderate and the loan term is not stretched too far.
How much car can I afford on a 65k salary?
If your other bills are heavy, stay below those numbers instead of pushing to the top.
How much car can I afford on a 100k salary?
On a 100k salary, the payment ceiling can move into the high-$500s to mid-$600s, with a fuller ownership budget around the high-$800s to roughly $1,300. Even at that income, insurance, fuel, taxes, and debt can make a lower-priced car the smarter move.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.