Carvana Auto Loan Review: Rates, Terms, Pros and Cons
Carvana financing makes sense only when its APR beats your bank or credit union quote. If it does not, you usually pay more for the same used-car loan. Bad terms can add thousands in interest and lock you into fewer repayment choices. This guide compares Carvana’s rates, term lengths, approval hurdles, and where its loan fits against credit unions, banks, and online lenders.
This guide is part of our Car buying, financing, and selling guide series.
Carvana auto loan review: verdict, rates, and who should use it
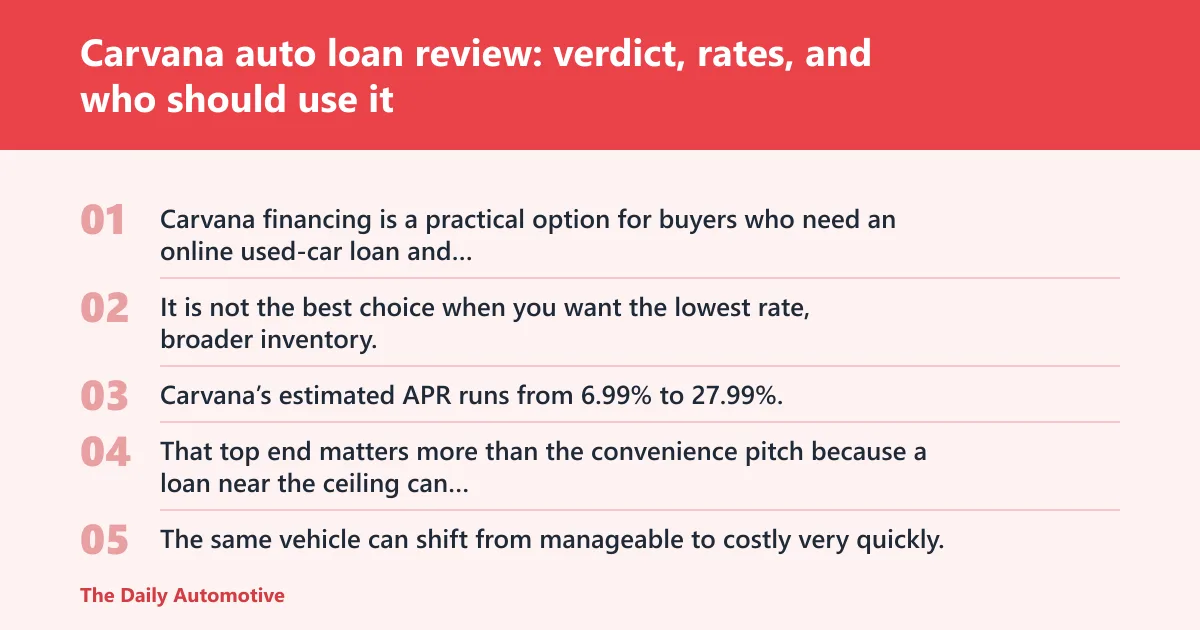
Carvana financing is a practical option for buyers who need an online used-car loan and can accept a wide APR spread, vehicle limits, and no deferred-payment start. It is not the best choice when you want the lowest rate, broader inventory, or a loan that works outside Carvana’s catalog with a co-borrower.
How the rate range affects total loan cost
Carvana’s estimated APR runs from 6.99% to 27.99%. That top end matters more than the convenience pitch because a loan near the ceiling can cost far more than a credit union or prime bank offer. The same vehicle can shift from manageable to costly very quickly.
Here is the practical gap. On a $20,000 loan over 60 months, a rate near 7% can keep the payment in a middle range, while a rate near 28% can push the payment sharply higher and add substantial interest over the life of the loan. The longer the term, the more that gap matters.
Bottom line for fair-credit, thin-credit, and budget-focused buyers
Fair-credit borrowers may find Carvana workable if the rate is competitive and the vehicle is a Carvana listing they already want. Thin-credit buyers can still qualify, but the loan will usually price risk into the APR. Budget-constrained buyers should watch the payment first, not approval alone.
📊 Carvana used auto purchase loans show an estimated APR of 6.99-27.99%. Source: Carvana Review: Financing, Buying, Selling.
What is Carvana financing and how does it work?
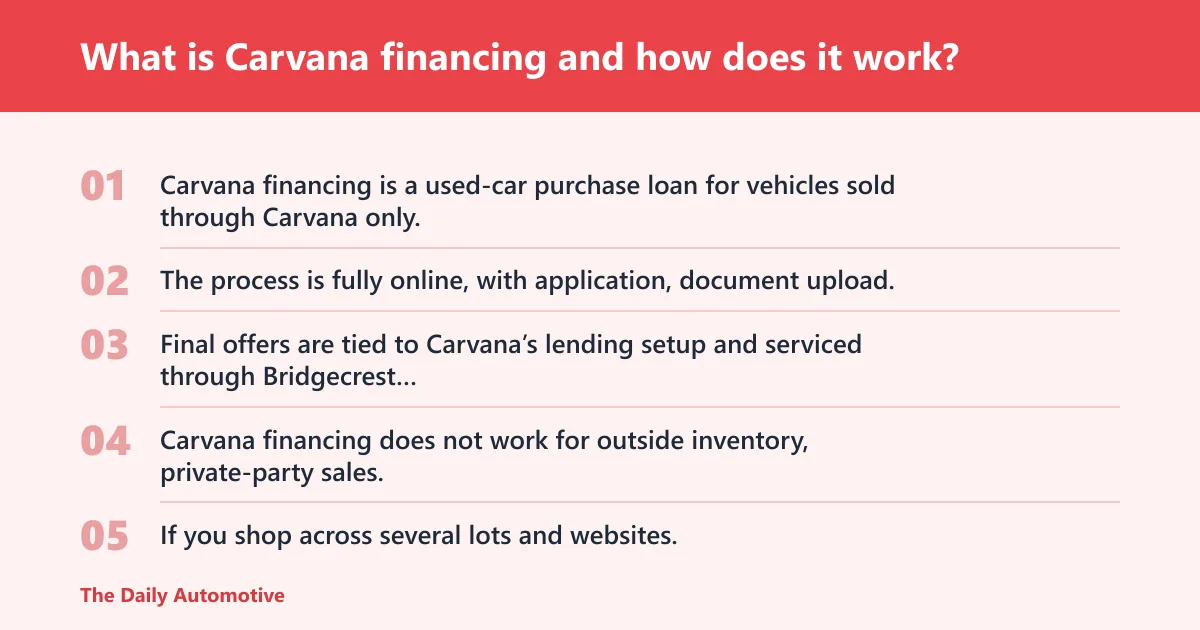
Carvana financing is a used-car purchase loan for vehicles sold through Carvana only. The process is fully online, with application, document upload, and pre-qualification handled through a soft credit check. Final offers are tied to Carvana’s lending setup and serviced through Bridgecrest Acceptance.
Used-car financing only for Carvana inventory
This is the biggest limit to remember. Carvana financing does not work for outside inventory, private-party sales, or a dealer car listed elsewhere. If you shop across several lots and websites, Carvana’s loan can cut down your options before you even compare rates.
100% online application, document upload, and soft-check pre-qualification
Carvana lets buyers pre-qualify with a soft credit check, so early shopping usually does not trigger a hard inquiry. That helps with rate shopping at the start. Once you move forward, you still need income and identity documents that match the file.
Bridgecrest Acceptance and loan servicing
Carvana’s loan offers go through Bridgecrest Acceptance and servicing. That matters because your day-to-day experience after closing is not just about the purchase flow. It affects billing, payment changes, late-fee handling, and any support request after the car is delivered.
What are Carvana loan rates, terms, and fees?
Carvana’s estimated APR range is 6.99% to 27.99%, with the final rate driven by credit and vehicle. Loan terms can include 12, 24, 36, 48, and 60 months, though the maximum term varies by customer and vehicle. Carvana does not charge an application fee or document processing fee.
Estimated APR range from 6.99% to 27.99%
The upper end is high enough to matter even for used-car shoppers with average credit. That is why Carvana can fit some borrowers and be poor value for others. A lower advertised payment can hide a steep interest cost if the loan stretches to 60 months at a high APR.
Term options from 12 to 60 months and how the final term is set
Carvana may offer 12, 24, 36, 48, and 60-month terms. The maximum term depends on the deal, and the customer can choose less than the maximum term if a shorter payoff makes more sense. Shorter terms usually mean higher monthly payments and less total interest.
No application or document fee, $5 late fee, and 15-day grace period
Carvana does not charge an application fee or document processing fee. It does charge a $5 late payment fee and gives a 15-day grace period. There is also a $10 monthly payment discount with automatic payment, which helps a little but does not offset a high APR.
What do you need to qualify for Carvana financing?
Carvana appears to list some basic eligibility requirements, and does not appear to specify a minimum credit score or credit history. That makes the lender accessible to some thin-file borrowers, but affordability still depends on income, documents, vehicle fit, and the price of the loan.
Income, bankruptcy, and credit minimums
Carvana requires at least $10,000 in annual gross income and says no active bankruptcies are allowed. It also lists no minimum credit score and no minimum credit history. Those rules can open the door for borrowers that traditional lenders reject, but they do not guarantee a low-cost approval.
Why thin credit can still qualify but often at a higher cost
A borrower with little credit history may still get an offer if the income and vehicle pass review. The tradeoff is usually a higher APR. That is how the lender prices uncertainty. Approval is one question; affordability is a second, more important one.
Common approval failure points: income pressure, document mismatch, and vehicle fit
Many applications fail for simple reasons: income that is too tight relative to the payment, missing or inconsistent documents, or a vehicle that does not fit the lender’s criteria. Say your monthly gross income is barely above the threshold and the payment rises after insurance and gas are included. The file may be approved on paper and still be too tight in practice.
Pros and cons of Carvana financing
Carvana’s financing can help borrowers who need an online approval path and can live with a Carvana-only inventory. The drawbacks are just as clear: a high APR ceiling, no deferred-payment start, and limited flexibility if you need a co-borrower or a non-Carvana vehicle.
Pros
- Soft credit check for pre-qualification.
- No minimum credit score listed.
- Low stated income floor at $10,000 annually.
- No application fee or document processing fee.
- Autopay discount of $10 per month.
- Support available seven days a week.
Cons
- Only applies to vehicles sold through Carvana.
- Estimated APR can reach 27.99%.
- No deferred-payment start option.
- Late fee applies after the grace period.
- Due date changes appear to be limited during the loan term.
- Not available in Alaska or Hawaii.
Who is Carvana financing best for?
Carvana financing is best for buyers already committed to a Carvana vehicle, especially if they want an online process and their credit profile is not strong enough for a prime-bank rate. It is a weaker fit for shoppers who need outside inventory, a co-signer-friendly structure, or a lower APR.
Fair-credit buyer buying a Carvana car
This is the strongest use case. If the vehicle price is fair and the rate lands near the lower end of the range, Carvana can be a workable option. Still compare the full cost, because a slightly lower APR from a bank or credit union can save real money over 48 or 60 months.
Thin-credit buyer who needs a possible approval path
Carvana can be one of the few lenders willing to look at thin credit and limited credit history. That does not mean the offer will be cheap. Picture a first-time buyer choosing between a 36-month loan with a high payment and a 60-month loan with more total interest; the difference changes the budget quickly.
Budget-constrained buyer comparing payment size against total interest
Budget-focused shoppers need to compare the monthly payment with the total interest over the full term. The $10 autopay discount helps, but it is small compared with the cost of a high APR or a stretched-out term. If cash flow is tight, the loan can become expensive fast.
Decision table: Carvana fit by credit profile and budget
The table below turns the approval rules into buyer-level decisions. The biggest differences are not convenience points. They are rate, term length, vehicle limits, and whether the loan fits the rest of your budget.
| Buyer profile | Likely Carvana fit | Key friction points | Feature that changes monthly cost most |
|---|---|---|---|
| Fair credit | Often possible if the car is on Carvana and the rate is acceptable | Rate may still be higher than a credit union; term choice can raise total interest | APR and term length |
| Thin credit | Possible path to approval if income and documents line up | Higher APR risk; payment-to-income pressure; no deferred-payment start | APR, due date timing, and loan length |
| Budget-constrained buyer | Only if the monthly payment stays realistic after insurance and fuel | Long term can cut payment but raises total interest; late fee hurts tight budgets | Term length, autopay discount, and late-fee exposure |
What should you know before you accept a Carvana loan?
Before you accept, check three things: the payment date, the total interest, and what happens if cash flow slips. Carvana lets you change the selected due date after the first payment, but only twice during the loan term. That small detail matters if your pay cycle changes.
Autopay discount and due-date changes
The $10 monthly autopay discount is useful, but the real benefit is smoother payment handling. The due date can be changed after the first payment, yet only twice during the loan term. If your paycheck timing is uneven, that limit can become a problem later.
What happens if you miss a payment
Carvana charges a $5 late fee and gives a 15-day grace period. After that, the account can move into late status, which can add stress to a budget that was already tight. If a payment looks at risk, contact support before the grace period ends.
Why the lack of a deferred-payment start matters
Some lenders offer a delayed first payment, which can help when a buyer has moving costs, insurance deposits, or repair expenses right after purchase. Carvana does not offer that start. That makes the first month more demanding, especially for budget-constrained buyers.
How does Carvana compare on customer experience and flexibility?
Carvana’s customer experience is strong on digital workflow and weaker on flexibility. Support is available seven days a week by phone, email, text, and live chat during application, and Spanish-speaking agents are mentioned. That is helpful, but it does not replace better pricing or a broader loan structure.
Support and servicing basics
Seven-day support is useful when you need help with documents, payment timing, or delivery questions. Still, loan servicing matters more than chat availability when the APR is high. A friendly support channel does not lower your monthly payment.
Vehicle limits and borrower limits
Carvana financing is only for vehicles sold through Carvana, with no maximum vehicle age and mileage that aligns with the current highest-mileage vehicle on the site, typically over 100,000 miles. That can suit shoppers looking at older inventory, but it does not help if the right car is elsewhere.
Frequently asked questions
Are Carvana loans good?
Carvana loans are good only for a narrow buyer profile: shoppers buying a Carvana vehicle who cannot get a better rate elsewhere or who need a soft-check path first. If a bank or credit union offers a lower APR, that loan is usually the better deal.
Does Carvana do auto loans?
Yes. Carvana offers used-car purchase loans for vehicles sold through Carvana. The application is online, pre-qualification uses a soft credit check, and the loan is serviced through Bridgecrest Acceptance. It does not finance vehicles outside Carvana’s inventory.
What are Carvana loan rates?
Carvana’s estimated APR is 6.99% to 27.99%. Your rate depends on credit quality and the vehicle. That wide spread means the offer can be reasonable for some buyers and very expensive for others, especially on longer terms.
Does Carvana affect your credit score?
Pre-qualification uses a soft credit check, which generally does not affect your score. A completed loan application and financing process can involve additional credit review. As with any lender, the exact impact depends on where you stop in the process and how many lenders you apply with.
What loan terms does Carvana offer?
Carvana loan terms can include 12, 24, 36, 48, and 60 months. The maximum term varies by customer and vehicle, and a borrower may select a shorter term than the maximum. Shorter terms usually reduce total interest but raise the monthly payment.
What fees does Carvana charge on financing?
Carvana does not charge an application fee or document processing fee. It does charge a $5 late payment fee and gives a 15-day grace period. There is also a $10 monthly discount for automatic payment, which can trim a little from the bill.
Can I finance a car from another lender through Carvana?
Yes, if you mean buying a Carvana car with outside financing. Carvana financing itself is only for vehicles sold through Carvana. That means you can finance elsewhere and still buy from Carvana, but Carvana’s own loan will not cover a non-Carvana vehicle.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.