LightStream Auto Loan Review: Rates, Terms, and Worth It?
LightStream fits good-credit borrowers who need private-party, refinance, lease buyout, or older-vehicle financing, but dealer offers or credit unions can be cheaper when subsidized APRs are available. Pick the wrong option and you can pay more interest, lose rate discounts, or miss fast funding. This review explains costs, speed, eligibility, and where LightStream beats dealer financing, banks, and other online lenders.
LightStream auto loan review: verdict first
LightStream makes the most sense for strong-credit borrowers who value flexibility more than the lowest advertised APR. Its unsecured structure, wide vehicle rules, and online process help when dealer financing does not fit, but the lack of prequalification means you get only one shot at the rate screen.
Bottom line for good-credit borrowers
If you already know you have good-to-excellent credit and you want to finance a private-party car, an older used car, a lease buyout, or a refinance, LightStream is worth a close look. If you need softer underwriting, a dealer’s subsidized promo APR, or a lender that lets you shop with a preapproval first, start elsewhere.
Where LightStream can beat dealer financing
LightStream can win when the vehicle or transaction type falls outside dealer finance rules. That includes classic cars, private-party purchases, and cars with high mileage or older model years, because LightStream does not set maximum age or mileage caps on used-car purchase loans.
Where a different lender may cost less
A secured auto lender or a credit union can be cheaper if the dealership is offering a low promotional APR tied to the manufacturer, or if your credit profile is solid but not pristine. LightStream also loses ground if you want to compare several offers through prequalification before applying.
What LightStream offers and how the loan works
LightStream’s auto loan is an unsecured, fixed-rate, simple-interest, fully amortizing installment loan. LightStream says it has no fees and no prepayment penalties, and its quoted rate includes an AutoPay discount built into the advertised pricing.
Unsecured, fixed-rate, simple-interest structure
Because the loan is unsecured, the vehicle is not the collateral the way it is with a traditional dealer auto loan. That gives you more freedom with vehicle type and age, but it also means the lender takes more credit risk, which is one reason strong credit matters so much here.
No fees and no prepayment penalty
LightStream says there are no fees and no prepayment penalties. That matters if you plan to pay the loan off early or refinance later, because you do not have to worry about a payoff charge erasing part of the savings.
AutoPay discount and price effect
LightStream quotes rates with an AutoPay option discount. The invoicing option is 0.50% points higher than AutoPay, so skipping AutoPay can raise the loan’s cost before you even factor in term length or credit tier.
Picture a borrower financing a $20,000 car over 60 months. A 0.50-point pricing difference can move the monthly payment enough to matter, especially if the borrower is comparing LightStream to a lender whose best rate already assumes autopay enrollment.
Who is LightStream best for?
LightStream is best for borrowers with good-to-excellent credit, stable enough income, multiple account types, and a clean enough payment history to satisfy a stricter underwriting screen. If you need a lender willing to work with thin files, recent delinquencies, or shaky income, this is probably not your first stop.
Credit profile and income signals LightStream wants
LightStream says it only approves good-to-excellent credit profiles and lists credit history, assets, income versus debt, and payment history as key approval factors. NerdWallet also lists a 660 minimum credit score for LightStream auto loans, but that should not be treated as a promise of approval.
Best-fit borrower profiles by use case
Good fit: a well-qualified buyer purchasing a used sedan from a private seller, a lessee buying out a car, or an owner refinancing a vehicle that a dealer lender will not touch. Also good fit: buyers of older or specialty cars who need financing beyond standard dealer inventory rules.
Who should probably skip it
If you need prequalification, want several quotes before committing, or expect a secured loan to beat the rate, LightStream is a weaker match. First-time buyers with thin credit files and shoppers who need the easiest approval path should compare credit unions and dealer financing before applying.
What can you finance with LightStream?
LightStream covers a wider set of auto uses than many conventional lenders. Its site includes Auto, Auto Refinance, Classic Car, New Car, and Used Car categories, and it also lists lease buyout and private-party auto purchase as allowed auto uses.
New and used cars
LightStream can finance new car and used car purchases. For used vehicles, its no maximum vehicle age and no maximum mileage policy is a practical advantage, especially when you are shopping outside dealer lots or looking at cars that are otherwise hard to finance.
Auto refinance and lease buyouts
LightStream also works for auto refinance and lease buyout transactions. That makes it useful if you want to replace a high-rate existing loan, or if a lease buyout is simpler than turning in the vehicle and starting over.
Private-party and classic car purchases
Private-party purchases and classic car financing are where LightStream stands out most clearly. Those deals often run into lender restrictions, title-process friction, or age limits elsewhere, while LightStream’s stated vehicle rules are looser.
How much can you borrow, and what terms are available?
LightStream loan amounts run from $5,000 to $100,000, according to NerdWallet’s review. LightStream’s site shows loan terms from 24 to 240 months depending on loan type, while competitor review pages commonly frame auto purchase and refinance terms in the 24 to 84 month range.
Loan amount range
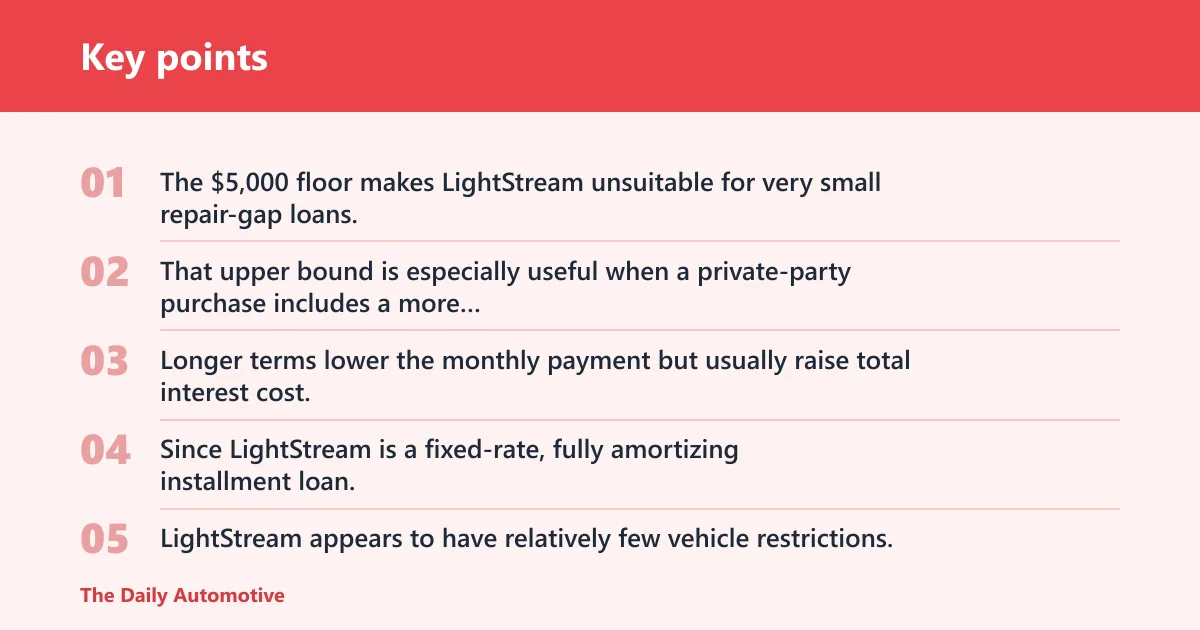
The $5,000 floor makes LightStream unsuitable for very small repair-gap loans, but the $100,000 ceiling is high enough for many new cars, higher-end used cars, and some specialty vehicles. That upper bound is especially useful when a private-party purchase includes a more expensive collectible or classic car.
Term range and how term choice changes cost
Longer terms lower the monthly payment but usually raise total interest cost. Since LightStream is a fixed-rate, fully amortizing installment loan, the payment stays the same each month, so term choice has a direct effect on both affordability and total payoff cost.
Vehicle age, mileage, and type rules
LightStream appears to have relatively few vehicle restrictions, including no stated maximum vehicle age or mileage. That is a meaningful difference from lenders that limit older cars, specialty vehicles, or high-mileage units.
| Loan feature | LightStream | Why it matters |
|---|---|---|
| Structure | Fixed rate, simple interest, fully amortizing installment loan | Payment stays level and the balance declines on schedule |
| Fees | No fees | No origination charge to add to the balance |
| Prepayment penalty | None | Early payoff is less costly |
| AutoPay pricing | 0.50% discount | Skipping AutoPay raises the price by 0.50% points |
| Credit profile | Good-to-excellent only | Weak or thin files are less likely to qualify |
| Vehicle rules | No age, mileage, or type restrictions | Older, high-mileage, and specialty vehicles stay in play |
How fast does LightStream fund an auto loan?
LightStream says funds may be available as soon as today, and same-day funding requires completed steps by 2:30 p.m. Eastern time. That can be fast enough for a closing deadline, but only if your paperwork is ready and the transaction clears before the cutoff.
Same-day funding timing and the cutoff
The 2:30 p.m. Eastern cutoff is the key timing detail. Miss it, and same-day funding may not happen, which matters if you are trying to pay a seller, close a refinance, or leave a dealership with a timed transaction.
Why funding can miss the same-day window
Funding can slip if the application is incomplete, if documents are missing, or if verification is not finished early enough. That is a real process risk for buyers who assume “funds as soon as today” means automatic same-day cash with no friction.
What documents and timing friction to expect
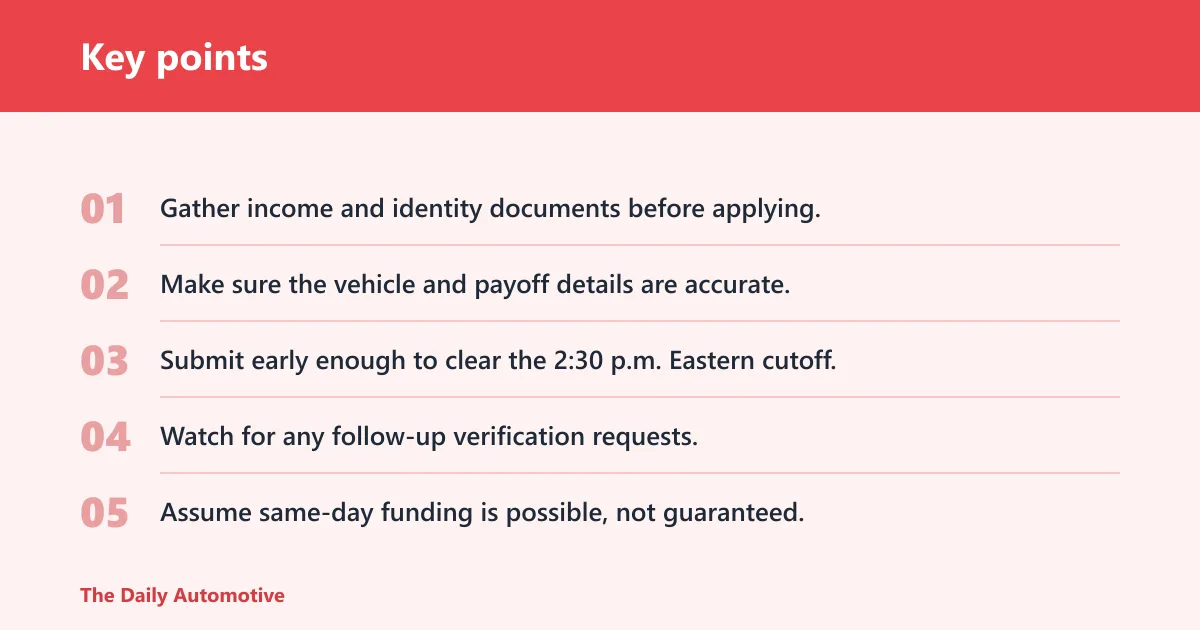
- Gather income and identity documents before applying.
- Make sure the vehicle and payoff details are accurate.
- Submit early enough to clear the 2:30 p.m. Eastern cutoff.
- Watch for any follow-up verification requests.
- Assume same-day funding is possible, not guaranteed.
A common first-timer mistake is starting the application late in the afternoon, then assuming the loan will still fund the same day. If a private seller is waiting in a parking lot and the title work is incomplete, the deal can slide to the next business day.
Borrower-fit matrix: when LightStream wins and when it does not
LightStream is not a universal best buy. It is strongest when the borrower has good credit, the vehicle is outside standard lender rules, and speed matters less than flexibility. It is weaker when you need a preapproval first or when a secured lender offers a lower APR on similar terms.
| Credit tier | Vehicle type | Purchase channel | Funding urgency | Likely LightStream outcome |
|---|---|---|---|---|
| Excellent | Used car under 10 years old | Private party | Same-day if paperwork is ready | Strong fit; flexibility can outweigh dealer financing friction |
| Good | Classic car | Private seller | Flexible | Strong fit if the seller needs non-dealer financing |
| Good | Used car | Dealer lot | Moderate | Mixed fit; dealer promo APR or credit union may be cheaper |
| Good | Lease buyout | Lease-end payoff | Fast | Good fit if you want to avoid a new dealer contract |
| Fair or thin file | Any | Any | Urgent | Poor fit; approval odds drop and no prequalification is a problem |
Monthly-payment example and failure-case notes
Suppose a borrower finances $20,000 over 60 months. The exact payment depends on the final APR, but the borrower with AutoPay will usually get a lower monthly payment than the borrower who takes the invoicing option, because rates without AutoPay are 0.50% higher. If that borrower also needs prequalification, LightStream is the wrong lane because it does not offer prequalification or preapproval.
When LightStream loses on cost
LightStream can be more expensive if a dealer advertises a subsidized APR, or if a credit union gives a lower rate on a secured loan. That is the main tradeoff: LightStream buys flexibility, not always the cheapest headline APR.
Pros and cons of LightStream auto loans
LightStream’s appeal is clear for borrowers who value access and speed without giving up a fixed payment structure. Its downside is equally clear: strong credit is required, the application is a hard-commitment process, and the best rate depends on AutoPay.
Pros
- Works for new cars, used cars, refinancing, lease buyouts, private-party purchases, and classic cars.
- No fees and no prepayment penalties.
- 0.50% AutoPay discount.
- No maximum vehicle age or mileage.
- Funding may be available as soon as today.
Cons
- Good-to-excellent credit only.
- No prequalification or preapproval.
- Rates without AutoPay are 0.50% higher.
- Same-day funding depends on a 2:30 p.m. Eastern cutoff.
- Secured lenders or dealer promos may cost less.
Frequently asked questions
how does lightstream auto loan work
LightStream auto loans are fixed-rate, simple-interest, fully amortizing installment loans. You apply online, the lender reviews credit and income factors, and approved borrowers can use funds for eligible auto uses such as purchases, refinance, or lease buyouts. The quoted rate assumes AutoPay enrollment.
Is LightStream good for used car financing?
Yes, especially if the used car is older, has higher mileage, or comes from a private seller. LightStream has no maximum vehicle age or mileage limits, which gives it an edge over lenders that only want late-model inventory. It is less useful if you need prequalification first.
Does LightStream offer auto loan preapproval?
No. LightStream does not appear to offer prequalification or preapproval for its auto loans, and the application is handled online. That means you cannot shop a tentative offer the way you can with many banks, credit unions, or marketplace lenders.
What credit score do you need for a LightStream auto loan?
LightStream says it only approves good-to-excellent credit profiles, and NerdWallet lists a 660 minimum credit score for LightStream auto loans. Score alone is not enough, though. LightStream also considers credit history, assets, income versus debt, and payment history.
Can you use LightStream for a private party car purchase?
Yes. LightStream lists private-party auto purchase as an eligible use, which makes it useful when the seller is not a dealer. That can be a major advantage for older used cars, collector vehicles, and local deals that do not fit normal dealer financing.
What are LightStream auto loan rates and terms?
Rates are quoted with an AutoPay option discount, and the invoicing option is 0.50% points higher than AutoPay. LightStream’s site lists terms from 24 to 240 months depending on loan type, while auto purchase and refinance review pages commonly cite 24 to 84 months.
Can you refinance an auto loan with LightStream?
Yes. LightStream lists auto refinance as one of its loan uses, and that can be helpful if you want to replace a higher-rate existing loan with a fixed-rate unsecured loan. It is most compelling for borrowers with good credit and a clean payment record.
Is LightStream good for lease buyouts?
Often yes, if you have strong credit and want to buy the vehicle without going through a dealer’s financing desk. LightStream lists lease buyout as an eligible use, so it can work well when the car’s residual value is attractive and the lease-end timing is tight.
What are the drawbacks of LightStream auto loans?
The biggest drawbacks are the good-credit-only gate, no prequalification, and the 0.50% pricing penalty if you skip AutoPay. It can also lose on price to a subsidized dealer loan or a lower-rate secured credit union offer, especially for standard new-car purchases.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.