Does Car Insurance Cover Death of Owner: Key Insights
No, a car insurance policy does not pay a death benefit when the owner dies; coverage stays tied to the vehicle and the policy terms, and the insurer usually needs to be told right away. If this is handled badly, claims can be delayed, denied, or expose the estate and driver to liability. This guide explains who can keep the car insured and driven, how ownership changes through the estate, and what insurers usually require.
What happens to the policy after death
When the policyholder dies, the insurance contract does not usually end right away, and it does not automatically transfer to the next of kin by default. The policy may continue briefly while the insurer waits for notice and estate documents, then the insurer may be able to rewrite, cancel, or transfer it depending on its rules and the car’s legal status.
Policyholder death versus vehicle ownership
The policyholder, the registered keeper, and the legal owner can be different people. Death affects the policyholder’s authority, but the vehicle itself becomes part of the estate unless it was jointly owned or already transferred. That split matters because insurance follows the contract, while ownership follows probate or another transfer process.
When coverage may continue briefly
Many insurers allow the policy to remain in force for a short period after death, especially if premiums are current and the car is still being kept safely. That does not mean anyone can drive it freely. Coverage questions turn on who is named on the policy, whether the car is kept on the road, and whether the insurer has been told.
When the insurer may end or rewrite the policy
Once the insurer learns of the death, it may ask for proof and then decide whether to continue the policy for the estate, move it into another name, or cancel it and refund any unused premium. Late notice can matter. If a renewal date passes or a premium is overdue, the risk of lapse rises quickly.
Who can contact the insurer?
The executor is the best person to notify the insurer because the executor has authority to deal with estate property once that authority is documented. If there is no executor yet, the insurer may still speak to a surviving spouse or another relative about urgent protection steps, but that person may not be able to change the policy or authorize a transfer.
Executor authority and estate papers
An estate executor should contact the insurer as soon as practical and be ready to identify the deceased policyholder, the vehicle, and the claim status. The insurer may ask for a death certificate and, later, grant of probate or letters of administration. If the vehicle was involved in a crash, keep the claim records together from the start.
What a surviving relative can ask
A surviving relative can usually ask the insurer what happens next, whether the car remains insured for storage or limited driving, and which documents are needed. That relative should avoid assuming they can cancel or continue the policy unless they are the executor or otherwise authorized by the estate.
Information the insurer will usually need
Expect the insurer to ask for the policy number, vehicle registration details, the death certificate, and proof of authority. If the car was damaged, accident records matter too. The insurer may also need to know whether the car will be sold, transferred, kept on the road, or taken off the road while probate is open.
Owner death checklist
Use this as a practical order of operations after the owner dies. It keeps the insurance question separate from the probate question, which helps prevent a coverage gap.
| Task | Who should do it | What to gather or ask | Why it matters |
|---|---|---|---|
| Notify the insurer | Executor first; a surviving relative may start the call | Policy number, death certificate, contact details | Prevents confusion about continued cover and renewal |
| Check who is allowed to drive | Executor with the insurer | Named-driver list, usage limits, current premium status | Stops unauthorized driving and possible uninsured use |
| Preserve paperwork | Executor | Registration papers, policy documents, payment records | Supports any transfer, sale, or claim |
| Decide whether to keep the car on road | Executor | Whether probate is open, whether a legal driver is available | Avoids a lapse if the car stays in use |
| Ask about cancellation or rewrite | Executor | Unused premium, renewal date, insurer rules | Clarifies whether the policy can continue for the estate |
| Plan sale or transfer | Executor | Authority documents and title or registration requirements | Connects ownership change to insurance change |
Can you keep driving the car?
Maybe, but only if the insurance terms and legal authority line up. A named driver may still be covered if the policy allows it and the insurer has not restricted the car after the owner’s death. If nobody has authority to keep the policy active, driving can become a coverage problem very quickly.
Named-driver rules after death
If a household member was already listed as a named driver, that is helpful but not automatic permission to keep using the car forever. The insurer may still treat the deceased owner’s policy as needing review or rewrite. Named-driver status matters most when the policy language allows a surviving driver to continue the vehicle under the same cover terms.
When driving becomes unsafe from a coverage view
Driving becomes risky if the insurer has not been told, if premiums are overdue, if the policy has lapsed, or if the driver is not listed and no one with authority has approved the arrangement. A crash under those conditions can leave the estate facing uninsured loss or a disputed claim.
When the car should be parked instead
If there is doubt about authority, premium status, or the insurer’s consent, park the car and keep it secured until the situation is clear. That is especially important if probate is not complete and no one can confirm who may drive. A short pause is better than creating a coverage gap that is hard to fix later.
What to do with the car during probate
During probate, the executor should choose one path and document it: keep the car insured and roadworthy, store it, sell it, or transfer it. The right choice depends on whether the estate needs the vehicle used, whether a lawful driver exists, and whether the insurer will continue the policy or require a rewrite.
Keep, store, sell, or transfer
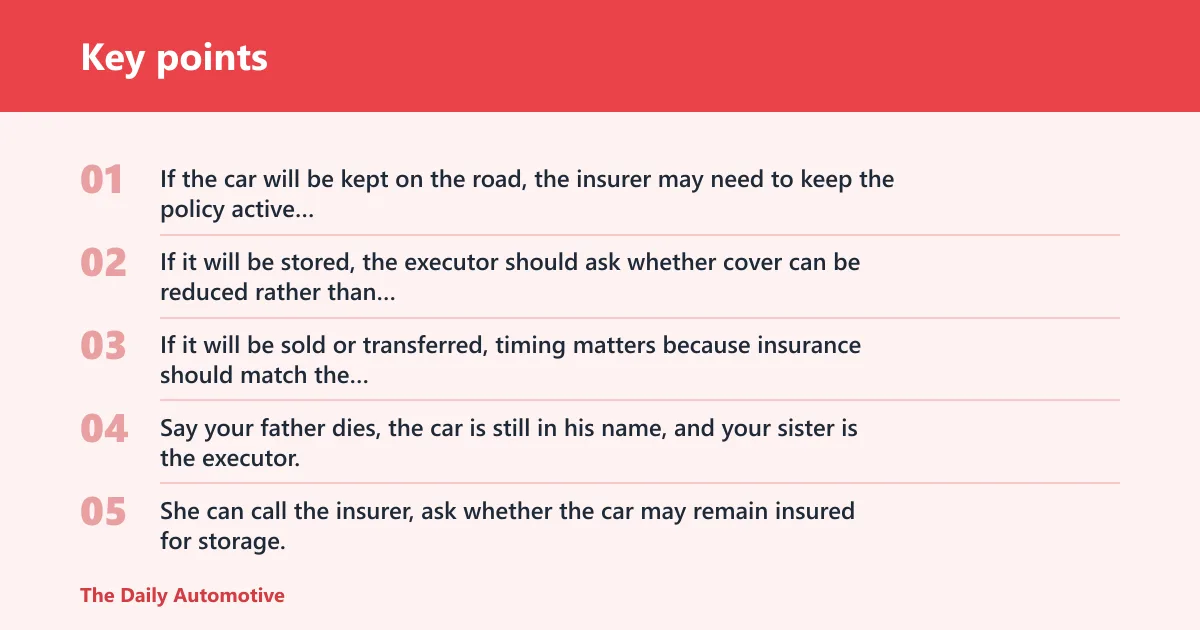
If the car will be kept on the road, the insurer may need to keep the policy active under estate authority or issue a new policy in another name. If it will be stored, the executor should ask whether cover can be reduced rather than cancelled outright. If it will be sold or transferred, timing matters because insurance should match the change in ownership.
Say your father dies, the car is still in his name, and your sister is the executor. She can call the insurer, ask whether the car may remain insured for storage, and confirm whether a named driver may keep it on the road until probate is settled. That avoids guessing about who has authority.
Registration and title updates
Insurance does not change title by itself. The estate still needs the correct registration or ownership update before the car is fully transferred. The insurer may accept temporary estate handling, but the legal owner on paper must still be updated through the proper process.
How cancellation timing can affect value and risk
If the policy is cancelled too early, the car may sit uninsured while probate is still open. If it is left active without authority, the estate may pay for cover that no longer matches the real use of the vehicle. The executor should ask the insurer whether continuation, rewrite, or cancellation is the cleanest option for the estate’s next step.
If there is a crash while the estate is open
A crash involving a deceased owner’s car should be handled like any other claim, but with extra care about authority and documentation. The insurer should be told promptly, and the estate should preserve records that show what happened, who was driving, and whether the driver was permitted to use the car.
Accident report details to collect
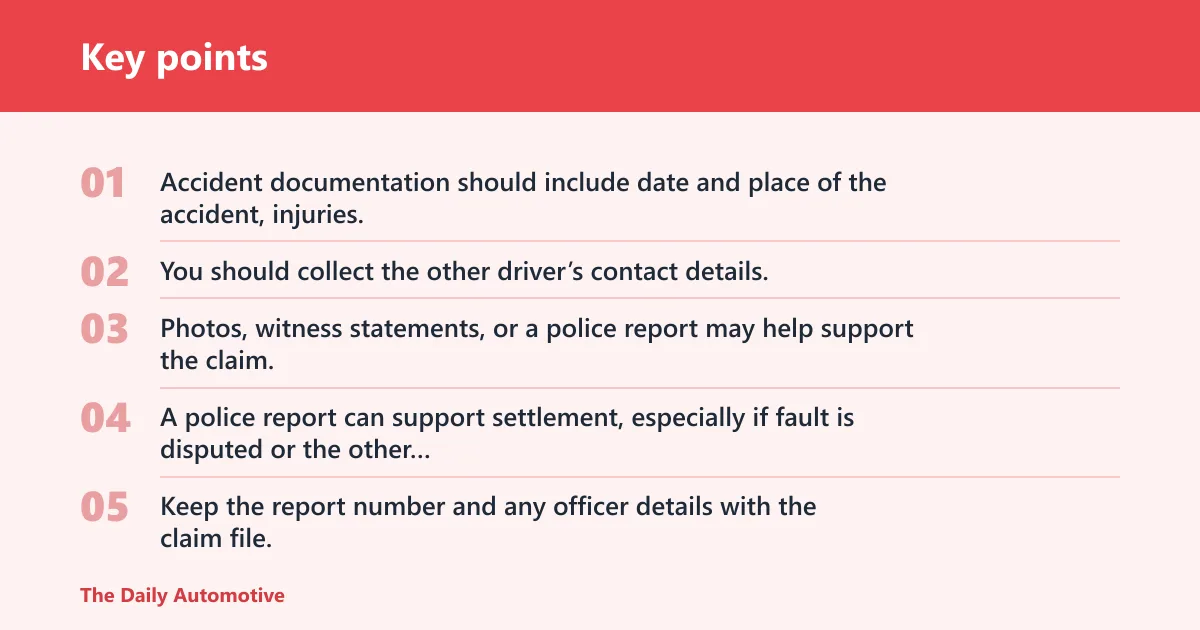
Accident documentation should include date and place of the accident, injuries, material damage, and witness details. You should collect the other driver’s contact details, insurance company details including policy number, and the vehicle registration number and country of registration. Photos, witness statements, or a police report may help support the claim.
Police report and claim support
A police report can support settlement, especially if fault is disputed or the other driver leaves the scene. Keep the report number and any officer details with the claim file. If there is no police report, the insurer may still handle the claim, but the evidence burden can be heavier.
When to avoid admitting liability
You should not admit liability at the scene. A simple apology can be read as an admission, and the facts may still be unclear. Stick to the essentials, exchange information, and let the insurer assess responsibility from the report, photos, witness accounts, and any police record.
Suppose the estate’s car is sideswiped in a supermarket lot while the executor is still sorting probate. The driver should note the date and place, photograph the damage, collect the other driver’s insurer and policy number, and avoid saying who caused it until the insurer reviews the facts.
What if the other driver is uninsured or unidentified?
If the other vehicle is uninsured or cannot be identified, the national compensation body can intervene in some cases. Cross-border claims may also involve a green card bureau or information centre that can help identify the insurer or the right contact point. The exact route depends on where the crash happened and which country’s rules apply.
National compensation body routes
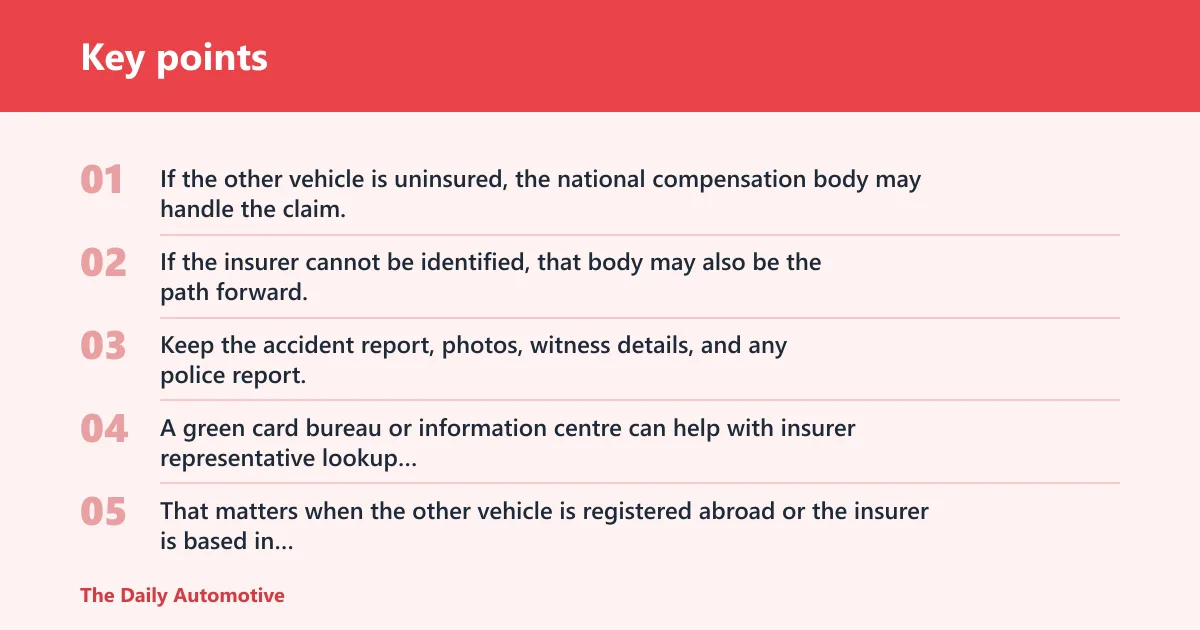
If the other vehicle is uninsured, the national compensation body may handle the claim. If the insurer cannot be identified, that body may also be the path forward. Keep the accident report, photos, witness details, and any police report, because those records can support the claim file.
Green card bureau and information centre help
A green card bureau or information centre can help with insurer representative lookup and cross-border claims support. That matters when the other vehicle is registered abroad or the insurer is based in another country. These offices can point the claimant toward the right representative or claims channel.
Cross-border claims after returning home
You can often file a claim abroad or after returning home, but the law of the country where the accident took place is applied. You must not leave the scene after an accident abroad. If there is a common European Accident Statement available, it can help settle the claim, but it does not replace the need to collect the key details at the scene.
Picture a car from the estate being hit in another country by a vehicle with no obvious insurer details. The driver should stay at the scene, gather witness names, and take down the other vehicle’s registration and country of registration. The green card bureau or information centre can then help locate the right contact path.
Frequently asked questions
Does car insurance cover the death of the owner?
No. Car insurance does not pay a death benefit simply because the policyholder died. It may continue for a short period under the policy terms, but the insurer usually needs notice and estate documents. Coverage depends on the contract, premium status, driver authority, and what the estate decides next.
What happens to car insurance when the policyholder dies?
The policy usually does not vanish instantly, but it should be reviewed right away. The insurer may continue it briefly, request probate papers, or cancel and refund unused premium. The estate executor should ask whether the car can remain insured, be rewritten in another name, or be taken off the road.
Can you keep driving a deceased person’s car?
Only if the policy, driver status, and estate authority all line up. Being a named driver helps, but it is not enough by itself if the insurer has not been told or the policy has lapsed. If there is doubt, park the car until the insurer confirms the position.
Who notifies the insurer after the owner dies?
The executor should notify the insurer first because the executor has estate authority once that authority is documented. A surviving spouse or relative can make an initial call, but may not be able to change the policy. The insurer will usually want the policy number, death certificate, and proof of authority.
Does the insurance transfer to the estate or next of kin?
Not automatically. The insurer may continue the policy for the estate, rewrite it, or cancel it, depending on its rules and the documents provided. Next of kin can inherit the car through probate, but that does not automatically transfer the insurance contract without the insurer’s agreement.
What documents do I need to claim after a car accident abroad?
Gather the date and place of the accident, injuries, material damage, witness details, the other driver’s contact details, insurance company details including policy number, and the vehicle registration number and country of registration. Photos, witness statements, or a police report may help. Also notify your insurer even if you do not plan to claim.
Should I report an accident if I do not want to make a claim?
Yes. You should report the accident to your insurance company even without a claim. That protects you if the other side later reports damage, and it gives the insurer a record of what happened. Keep the basic facts, witness details, and any police report in case the situation changes.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.