Is Auto Repair Insurance Worth The Money? Honest Answer
Auto repair insurance is worth the money only when your annual premium plus deductible is lower than the repair risk you would otherwise pay, often after a $1,500 to $3,000 claim gap. Skip that math, and you can pay extra for coverage that never beats your likely repair bill. This guide breaks down the break-even test for new-car low-mileage drivers, used-car high-mileage owners, and warranty-gap shoppers.
How to figure out if auto repair insurance saves you money
Sometimes. Mechanical breakdown insurance, or MBI, makes financial sense when the covered repair risk is high, your car qualifies, and the premium plus deductible stays below what you would expect to pay yourself. For many drivers, the answer changes with mileage, age, and how long they plan to keep the car.
The quick answer by ownership type
Low-mileage new-car drivers can come out ahead if they own a model with expensive covered failures and a modest premium. High-mileage used-car drivers usually lose on the math because many policies limit older vehicles or price them for higher risk. Warranty-gap drivers sit in the middle and need the cleanest break-even check.
MBI is an optional auto insurance add-on that covers specific mechanical failures standard car insurance does not pay for, such as engine, transmission, drivetrain, and electrical breakdowns. It is often sold by insurers, and sometimes by banks or credit unions, but eligibility can be narrow. Some policies require the vehicle to be relatively new; one example is under 15,000 miles.
When the math favors paying cash
If the likely repair is small, intermittent, or more likely to be wear than failure, paying out of pocket usually wins. A $120 sensor on a car with a low annual premium may still not justify coverage once you add the deductible and the chance that the claim gets denied for maintenance or exclusion reasons.
Suppose a driver pays about $240 per year for MBI with about a $100 deductible. If the likely covered repair is a $2,400 transmission repair, the expected value can be favorable only if the claim is realistic and the policy accepts the failure. If the same car is more likely to need about $300 in brake work, the policy loses on value.
What does auto repair insurance cover?
Most MBI policies cover major mechanical systems, especially engine, transmission, drivetrain, and electrical systems. Some plans also include brakes and air conditioning. The exact list depends on the contract, so the policy form matters more than the sales pitch.
Major systems usually included
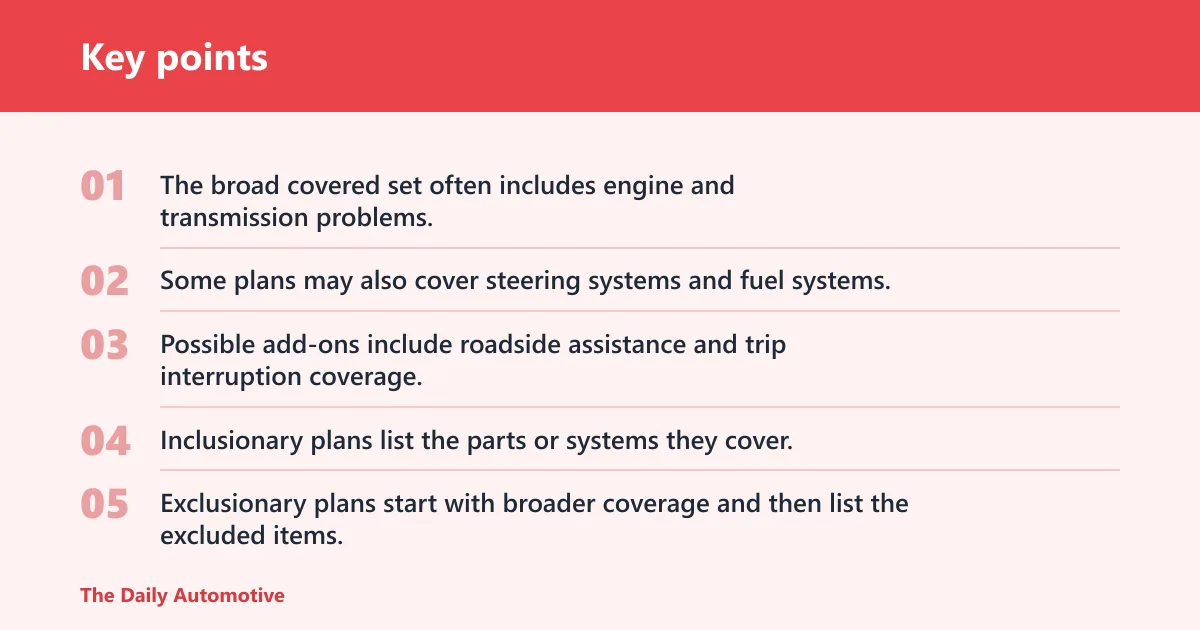
The broad covered set often includes engine and transmission problems, plus drivetrain and electrical issues. Some plans may also cover steering systems and fuel systems. Possible add-ons include roadside assistance and trip interruption coverage, but those extras do not change whether the repair coverage itself is a good deal.
| Ownership profile | Annual premium | Deductible | Likely covered repair cost | Claim probability | Math favorable? |
|---|---|---|---|---|---|
| Low-mileage new-car lease | $180 | $100 | $2,500 | Moderate | Yes, if the policy covers the failure and the car qualifies |
| High-mileage used-car owner | $360 | $250 | $1,200 | Moderate | No, the premium plus deductible is too close to the repair bill |
| Warranty-gap driver | $228 | $100 | $3,000 | Low to moderate | Usually yes, if the vehicle is eligible and the old warranty is ending |
How inclusionary and exclusionary plans differ
Inclusionary plans list the parts or systems they cover, so anything not named is outside the policy. Exclusionary plans start with broader coverage and then list the excluded items. Exclusionary wording can look better on paper, but claim documentation, policy limits, and exclusions still control the result.
What does mechanical breakdown insurance not cover?
MBI is usually reported to exclude routine maintenance, wear items, rust, corrosion, preexisting damage, neglect, and accident damage. That means the policy is built for mechanical failure, not normal service needs or damage from poor upkeep. If a repair comes from wear or missed maintenance, a denial is common.
Wear, neglect, rust, and preexisting damage
Wear-and-tear items such as worn brake pads are typically excluded. Routine maintenance like oil changes or tire rotation is also excluded. If the car had a problem before the policy started, or if corrosion caused the failure, the claim can be denied under the contract.
Why maintenance records matter
Claims often require proof that the vehicle was maintained on schedule. Missing oil-change records, skipped coolant service, or vague receipts can give the insurer a reason to question the cause of failure. That matters most on engine and transmission claims, where maintenance history is often part of the review.
A common first-timer mistake is assuming every warning light means a covered claim. Suppose a car shows a check-engine light after two overdue oil changes and then develops bearing noise. The insurer may treat that as maintenance-related damage, not a covered mechanical breakdown.
Repair coverage worksheet
Use this simple break-even check: annual premium plus deductible should be lower than the repair cost you would otherwise expect to pay. That is the cleanest way to separate a rational buy from an expensive guess. The claim also has to be eligible and properly documented.
- Estimate the covered repair you are trying to insure against.
- Add the annual premium to the deductible you would pay on a claim.
- Check whether your vehicle meets age, mileage, and maintenance requirements.
- Ask whether the likely failure is covered or excluded.
- Compare the total out-of-pocket cost with the likely repair bill.
If the premium is $240 a year and the deductible is $100, your break-even threshold is $340 before any claim denial risk. A $3,000 engine repair can justify the policy; a $600 AC repair often cannot. The deductible is paid out of pocket on a claim, so it materially changes the math.
How much does it cost?
Premiums vary by vehicle, coverage level, and deductible, but cited examples start as low as $12 per month and as little as $19 per month. That does not mean those prices are common for every driver. A car’s age, mileage, repair history, and covered systems can move the quote a lot.
Typical premium and deductible ranges
Deductibles generally range from $50 to $250. A lower deductible raises the monthly price, while a higher deductible can make the premium look cheaper but weaken the break-even case. If the deductible is too close to the repair you are trying to insure, the policy loses value fast.
Why quotes vary by vehicle
Insurers price risk by model, age, mileage, and expected failure cost. A late-model vehicle with limited miles may get a low quote if the insurer is comfortable with the risk. A used car with uncertain service records often gets a higher quote or no offer at all.
Who can buy it?
Eligibility depends on the insurer. New or leased vehicles are more likely to qualify, and low-mileage limits are common. Some plans also require maintenance records and may refuse older cars. A car that looks affordable to insure can still fail the age or mileage screen.
Age and mileage limits
Some insurers require the vehicle to be fairly new; one example is under 15,000 miles. That means a high-mileage commuter may not qualify even if the car still runs well. Eligibility varies by insurer, and the policy contract controls whether the car can be added.
New, leased, and used-car eligibility
New and leased vehicles are the easiest fit because the risk profile is clearer and the service history is cleaner. Used cars can qualify, but older models are less likely to pass underwriting or may carry tighter exclusions. Drivers with warranty overlap should also check whether they are paying for duplicate coverage.
Should you buy an extended warranty instead?
Sometimes, but only if you want dealer- or manufacturer-sold repair protection rather than insurance-regulated MBI. Extended warranties and vehicle service contracts are not the same product as MBI, even though both aim to offset repair bills. Warranty-gap drivers should compare the fine print, not the label.
MBI versus service contracts
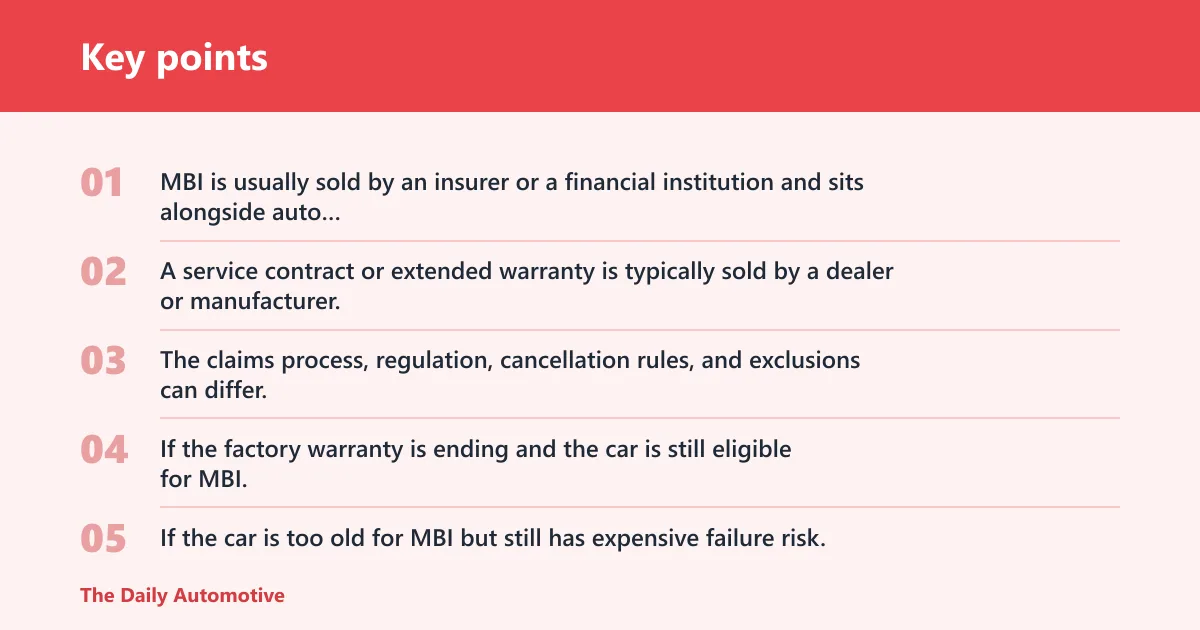
MBI is usually sold by an insurer or a financial institution and sits alongside auto insurance. A service contract or extended warranty is typically sold by a dealer or manufacturer. The claims process, regulation, cancellation rules, and exclusions can differ, so one product can fit a buyer even when the other does not.
Which product fits warranty-gap drivers?
If the factory warranty is ending and the car is still eligible for MBI, that can be the cleaner buy when the insurer’s price is lower and the contract is easier to compare. If the car is too old for MBI but still has expensive failure risk, a service contract may be the only repair-protection option left. Compare the covered systems, deductible, limits, and denial rules before choosing.
Frequently asked questions
Is auto repair insurance worth the money?
It is worth the money only when the annual premium plus deductible is lower than the covered repair risk you would otherwise bear. Newer, low-mileage cars with expensive failure exposure are the best candidates. Older cars with routine wear issues usually are not.
How much does car repair insurance cost per month?
Some cited premiums start as low as $12 per month, and another cited plan starts as little as $19 per month. Actual quotes vary by vehicle, age, mileage, deductible, and coverage level. A low monthly price does not guarantee a good deal.
What is the deductible on auto repair insurance?
Deductibles generally range from $50 to $250. You pay that amount out of pocket when a covered claim is approved. A higher deductible lowers the premium but can erase the savings if the repair is not large.
How do I know if repair coverage is cheaper than paying out of pocket?
Add the annual premium to the deductible and compare that total with the repair you are trying to protect against. If the total is lower than the likely covered repair cost, the math can work. Then confirm the vehicle qualifies and the likely failure is not excluded.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 Car Fuel Pressure Gauge - Auto Repair Tester with 6.3, 7.89, and 9.49 Connectors for Gasoline Injection Testing
 Auto Car Dent Repair Puller Head Paintless-Dent Repair Removal Kit for Slide Hammer Pulling Tab Adapter Pulling Tabs Car Aluminum-alloy Puller Head Adapter Screw Glue-tabs for Slide Hammer and