How Long Does Insurance Take To Fix A Car? Real Timelines
Most insurance-backed car repairs are commonly said to take about 1 to 3 weeks after the claim is approved, but simple jobs can finish in a few days, and shop backlogs, parts delays, or added repair steps can stretch the timeline to a month or more. Slow approval or missed paperwork can leave your car stuck at the shop and your payout delayed. This guide breaks down each step: insurer review, shop queue time, parts ordering, repair work, inspections, and final payment.
Why your claim is taking time
The timeline does not move in one straight line. An insurer has to open the claim, verify coverage, inspect the damage, decide who pays, and then authorize repairs or issue payment. Until those steps are done, the body shop may not be able to start structural work.
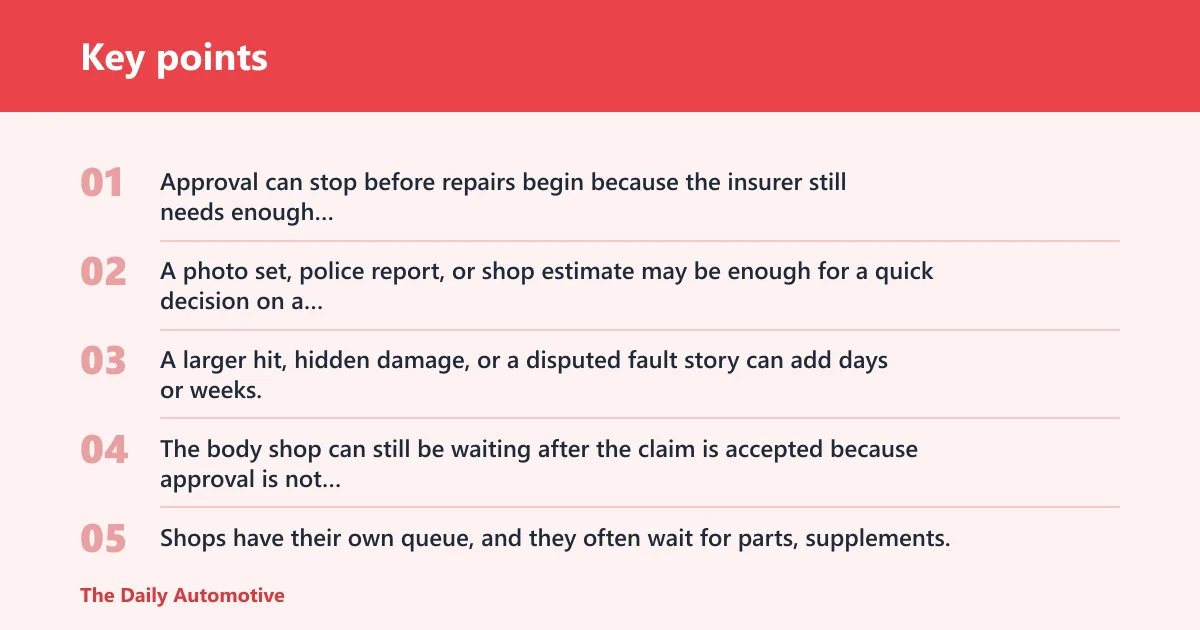
Approval can stop before repairs begin because the insurer still needs enough information to confirm the loss and the estimate. A photo set, police report, or shop estimate may be enough for a quick decision on a minor bump. A larger hit, hidden damage, or a disputed fault story can add days or weeks.
The body shop can still be waiting after the claim is accepted because approval is not the same as repair start. Shops have their own queue, and they often wait for parts, supplements, or a final authorization from the insurer before opening the vehicle. A claim can be “approved” while the car still sits in line.
Repair timeline
| Stage | Who controls it | Typical delay triggers | What you can do |
|---|---|---|---|
| Crash report and claim opening | You and the insurer | Missing claim number, late notice, incomplete facts | Report the loss quickly and give clean contact details |
| Initial review | Insurer | Coverage checks, fault questions, policy review | Send photos, driver info, and any police report |
| Inspection and estimate review | Adjuster and shop | A vehicle inspection and estimate can add multiple business days | Book the inspection fast and share the shop estimate early |
| Approval and shop authorization | Insurer | Estimate disputes, missing photos, supplement questions | Respond quickly to request letters or questions |
| Parts ordering and queue time | Body shop | Backorders, shipping delays, queue backlog | Ask whether the shop can order visible parts now |
| Repairs, supplements, and reinspection | Body shop and insurer | Hidden damage, extra damage found after teardown, supplement estimate review | Stay reachable if the shop finds new damage |
| Final invoice review | Insurer | Labor changes, completed work verification, pricing checks | Confirm the shop has sent the final paperwork |
| Payment to shop or driver | Insurer | State deadlines, lienholder issues, missing signatures | Ask whether payment goes to the shop, you, or both |
A rear-end claim can resolve in under two weeks in some cases when fault is clear, the car needs only light body work, and the shop has parts on hand. Add hidden bumper damage or a slow estimate review, and that same claim can stretch well past the first quote.
First-party vs third-party claims
First-party claims are filed with your own insurer. They are often covered by prompt-payment rules and usually move faster because the carrier already has your policy on file. Third-party claims are filed against the at-fault driver’s insurer, and they are often slower because fault must be established first.
That fault step matters. Fault investigation can take days or weeks, especially when stories conflict or more than two vehicles are involved. In a third-party claim, the insurer may not authorize repairs until it is comfortable with liability. Prompt-payment rules may not apply in the same way they do for a first-party claim.
How fault changes the pace
When the insurer already owes you under your own policy, the process is usually simpler. When the other driver’s insurer has to decide whether its customer caused the crash, repair money often waits for that decision. If fault is disputed, the repair timeline slows before the shop even gets full authorization.
Suppose a car is clipped in a parking lot and both drivers blame the other. The shop may have an estimate within a day, but the insurer may still need statements, scene photos, and a review of any camera footage before paying. The repair itself may be quick; the decision to pay is what drags.
When prompt-payment rules may matter
State insurance regulations set deadlines for acknowledgment, acceptance or denial, and payment, but those deadlines vary by state. Department of Insurance rules are the authority here, not a national average. First-party claims are the place where prompt-payment rules often matter most.
Which coverage pays for the repairs?
The coverage path changes the timeline. Collision coverage pays for your own vehicle repairs and often applies regardless of fault in many cases. Comprehensive coverage is for theft, weather, vandalism, and other non-crash losses where fault is irrelevant, and it often resolves faster than injury claims. Liability claim timing depends on proving the other driver caused the damage.
Uninsured motorist coverage comes into play when the at-fault driver lacks insurance. That may require a separate claim process, and timing depends on state and policy terms. In practice, it can move more like a first-party claim in some states, but the exact path depends on the policy language.
Collision coverage
Collision coverage is usually the direct route for a damaged car that needs body-shop work. Because it is your own policy, the insurer can often begin review faster than a third-party carrier waiting on fault confirmation. That does not remove the inspection, estimate, or parts delays, but it can shorten the front end.
Comprehensive coverage
Comprehensive claims are often more straightforward than injury claims because the insurer is dealing with a vehicle loss, not medical treatment and future care. A cracked windshield, hail damage, or theft-related loss may still need inspection, but the claim may resolve faster than a liability case tied to bodily injury.
Liability claim timing
Liability claims pay for damage you caused to others. They require fault determination, so they can be delayed by investigation even when the repair estimate is already complete. If the insurer is still sorting out who caused the crash, payment can wait while the body shop sits idle.
Uninsured motorist coverage
Uninsured motorist coverage can fill the gap when the at-fault driver has no insurance. That can keep the repair claim from depending on a useless third-party file, but the process may still involve policy checks and extra paperwork. Timing depends on the state and your policy terms.
What slows approval and payment?
Several issues can stall a claim after the crash report. The most common are inspection delays, estimate changes, missing paperwork, and state-specific deadlines that the insurer has to follow. Some of these are fixable by you. Others are controlled by the insurer or the shop.
Adjuster inspection delays
An adjuster inspection can add multiple business days. Photos may be enough for small damage, but an in-person look can slow the file if the adjuster is booked out. If the insurer wants a second look, the repair clock pauses again until that review is complete.
Repair estimate changes and hidden damage
The first estimate is often not the last one. Once the shop removes a bumper cover, wheel liner, or trim piece, hidden damage can appear. That usually means a supplement estimate, which has to be reviewed and authorized before the next stage starts.
Missing paperwork or slow replies
Missing paperwork can halt a claim entirely. Police report, photos, contact info, and repair estimates are the basics, and gaps in any of them can stall payment. If the insurer asks for more documentation and you wait days to answer, the file simply sits.
State insurance deadlines
State deadlines vary and are set by each state’s insurance rules. Some states require quick acknowledgment, while others give more room for investigation or payment review. The Department of Insurance in your state is the authoritative source for those deadlines.
How to speed up the claim
You cannot control every delay, but you can remove the ones tied to missing information and slow responses. The fastest files usually have clean documentation, a reachable claimant, and a repair shop that stays aligned with the insurer.
- Send the police report, photos, driver contact details, and shop estimate as soon as you have them.
- Reply the same day to adjuster requests for extra photos, signatures, or clarifying facts.
- Keep the body shop updated on who is paying and whether the insurer has approved teardown.
- Ask the adjuster what is still pending before the claim stalls for another business day.
- Check whether the insurer needs a supplement review before ordering more work.
A common first-timer mistake is assuming the repair clock starts when the car enters the shop. In reality, the clock often starts earlier, with the report and the first estimate, then pauses again if the insurer still needs fault information or a supplement review.
Picture a sedan with front-end damage after a low-speed crash in a grocery lot. The shop can quote the bumper, grille, and paint quickly, but if the insurer wants a second photo set and the owner leaves town for three days, the repair order stops until that reply comes back.
Does insurance pay the body shop directly or reimburse me?
It can do either, depending on the claim, the policy, and the shop arrangement. Many repair claims are paid directly to the body shop once the work is authorized and the final invoice is approved. In other cases, the insurer reimburses you, especially if you paid out of pocket first.
Direct payment is common when the shop and insurer are working from the same estimate and the claim is still open. Reimbursement is more likely when the driver already paid a deductible, chose a non-direct repair path, or had to advance money for part of the work. The key is to ask who is getting the check before repairs begin.
Frequently asked questions
How long does an insurance claim take to pay for car repairs?
Once a claim is approved, payment for repairs often follows the final invoice review and can move in days, not weeks. The longer delay is usually the front end: inspection, estimate approval, fault checks, and supplement review. If paperwork is missing, payment can wait until the file is complete.
How long does it take insurance to approve car repairs?
Approval can happen in a few days on a simple first-party claim with clear photos and a clean estimate. It can take longer when the insurer needs an in-person inspection, a fault decision, or a supplement review. A vehicle inspection and estimate can add multiple business days.
Why is my insurance claim taking so long to fix my car?
The delay is usually tied to one of four points: fault is still being decided, the estimate is incomplete, parts are backordered, or the claim file is missing something. Hidden damage is another common cause. The repair itself may be short; the authorization step is what slows everything down.
What slows down an auto insurance claim after an accident?
Inspection delays, disputed fault, hidden damage, missing documents, and part shortages are the main slowdown points. State deadlines also matter because insurers must follow local rules for acknowledgment and payment. If any required document is missing, the claim can stop until you provide it.
How long do third-party car insurance claims take?
Third-party claims often take longer because the other insurer must establish fault before paying. That investigation can take days or weeks, and prompt-payment rules may not apply the same way they do on your own policy. If liability is disputed, repair approval can wait even when the damage is obvious.
Products related to this article
Sponsored / affiliate links. As an Amazon Associate I earn from qualifying purchases. I may earn additional commission from eligible campaigns.
 4G GPS Tracker Car Anti-Theft Long Battery Life 20000mAh Real Time GPS Tracking Device Magnet No Geographic Restriction Car Tracker with Alerts, Geo Fence, History Playback TK905C
 Auto Car Dent Repair Puller Head Paintless-Dent Repair Removal Kit for Slide Hammer Pulling Tab Adapter Pulling Tabs Car Aluminum-alloy Puller Head Adapter Screw Glue-tabs for Slide Hammer and